
The Charlotte Cape Town: Prospekt CBD Aparthotel Review
The Charlotte: Prospekt's 35-unit boutique aparthotel at 20 Burg St, Cape Town CBD. R1.695m to R5.25m, Q4 2025 target, UDZ incentives, short and long let.
By Cape Town Invest Editorial · Updated September 3, 2026 · 9 min read
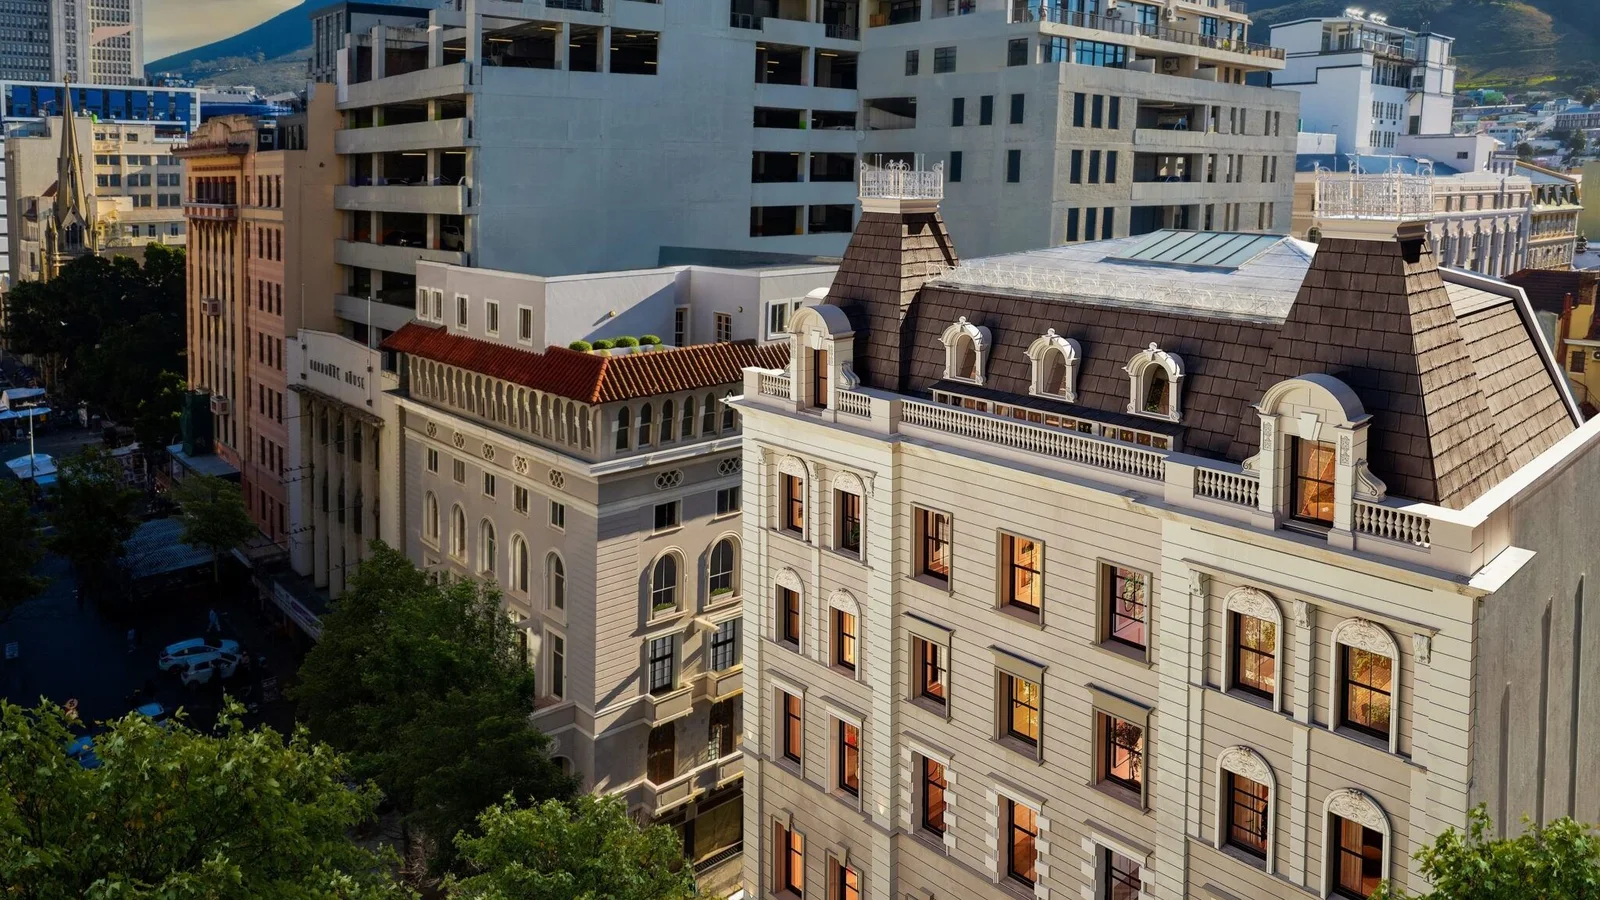
Quick answer: The Charlotte is a 35-unit boutique aparthotel by Prospekt Property Development at 20 Burg Street, on the corner of Hout and Burg in the Cape Town City Bowl. The mix runs from studios through one-bedroom apartments to two-bedroom lofts, priced R1.695m to R5.25m, with a Q4 2025 completion target. It pairs a managed hospitality front desk with both short-stay and long-let demand, and sits inside an Urban Development Zone that can carry meaningful tax depreciation. The developer’s marketing has cited net returns up to 13.44%, but that figure is DEVELOPER-CLAIMED and NOT guaranteed, so underwrite the deal on a conservative net base case instead.
How should you underwrite The Charlotte?
The Charlotte is one of the more interesting small-format launches in the Cape Town CBD because it combines three things that rarely sit together in one building: a genuinely central City Bowl address, an aparthotel operating model with a managed front desk, and Urban Development Zone tax mechanics. At 35 units it stays boutique rather than block-scale, which matters for short-letting because guests pay a premium for buildings that feel curated rather than mass-market. Entry at R1.695m for the smallest format is accessible for the area, and the R5.25m ceiling for the two-bedroom lofts keeps the building’s price band tight and coherent.
The single most important thing to understand before you read any further is that the headline 13.44% net return circulating in Prospekt’s marketing is DEVELOPER-CLAIMED and NOT guaranteed. It is a best-case projection from the developer’s own occupancy and rate model. We have not seen audited booking data behind it, and it sits well above what independent City Bowl apartments produce, which model closer to 7% to 9% gross and 5% to 7% net after levies, rates, management commission and vacancy. The gap between 13.44% and 7% is not a rounding difference: on a R1.695m studio it separates roughly R119,000 of annual net income from roughly R228,000. Ignore the headline, rebuild the deal on a conservative net base case, then treat anything above that as upside rather than the plan.
What is The Charlotte development and who is the developer?
The Charlotte is a 35-unit boutique aparthotel by Prospekt at 20 Burg Street in the Cape Town CBD, priced from R1.695m for a studio to R5.25m for a two-bedroom loft, with a stated Q4 2025 completion target. A managed hospitality layer runs the building rather than 35 separate owner listings.
Prospekt focuses on the Cape Town inner city, and the three formats split cleanly: studios for the smallest entry point and the highest gross yield per rand, one-bedroom apartments as the volume product, and two-bedroom lofts for owner-occupiers and premium short-stay guests. The managed layer standardises guest experience, smooths occupancy across the year, and gives owners a hands-off path to short-stay income.
The stated completion target is Q4 2025, which at the time of writing puts the project at or near completion. That is a meaningful detail for buyers: a near-complete building carries far less delivery risk than an early off-plan launch, but you still need to verify the actual handover date, the NHBRC warranty registration, and the first-year body corporate budget before you commit. For the wider context on buying before or around completion, see our off-plan property Cape Town guide.
Where is The Charlotte and why does the Burg Street address matter?
Burg Street at the Hout Street corner is one short block from St George’s Mall, a few minutes on foot from Greenmarket Square, and an easy walk from the Company’s Garden. That car-free arrival is the strongest driver of nightly rate in the CBD, where well-run stock models about 7% to 9% gross and 5% to 7% net.
For a long-let tenant the same address means walking to work in the financial district rather than commuting, which is what holds renewal rates up in a market with high churn.
Micro-location matters more in the City Bowl than in most Cape Town submarkets because the character of a street can change within two blocks. The Burg and Hout corner sits in the professional and retail core rather than on the nightlife strips, so evening noise profiles differ from Long Street or Bree. Walk the block yourself at three different times: a weekday morning, a weekday evening, and a Sunday. The CBD empties out on weekends in a way that residential suburbs do not, and that shapes both tenant experience and guest reviews.
Two practical checks belong in your due diligence. First, parking: central CBD schemes frequently sell bays separately or offer none, and a guest arriving with a hire car needs a solution. Confirm in writing what your specific unit includes. Second, aspect and floor level, since surrounding buildings in a dense historic grid can block light and views on lower floors. The City Bowl investment guide sets out how these street-level factors move achievable rent.
Floor plans and prices
The Charlotte prices run from R1.695m for a studio to R5.25m for a two-bedroom loft across 35 units in three formats. Studios carry the highest gross yield per rand and the highest short-stay turnover; one-bedrooms are the volume product; lofts serve owner-occupiers and premium guests. Model each on 5% to 7% net.
| Format | Indicative price | Best fit |
|---|---|---|
| Studio | from R1.695m | Highest gross yield, short-stay volume |
| One-bedroom | mid-range | Balanced short and long let |
| Two-bedroom loft | up to R5.25m | Premium short-stay, owner-occupier |
UDZ tax benefits (verify with an accountant)
The Charlotte sits inside Cape Town’s Urban Development Zone, so a South African taxpayer can claim accelerated depreciation on the building portion of the price against taxable income. The allowance is legislated, but it depends on your tax position, the building-versus-land split, and SARS rules. Depreciation cuts base cost, and CGT inclusion is 40% for individuals at exit.
For that reason the UDZ benefit MUST be verified with a qualified accountant or tax practitioner before you factor it into your return. Two cautions in particular: foreign buyers with little or no South African taxable income may capture little or none of the allowance, and the depreciation that reduces your base cost feeds capital gains at exit, where the inclusion rate is 40% for individuals and 80% for trusts and companies. Model the deal both with and without the UDZ benefit so you understand the floor.
Rental strategy and the 13.44% claim
The Charlotte is built for short-letting through its managed aparthotel layer, with a long-let fallback if regulation tightens or a season softens. Short-stay demand in central Cape Town is strong, and the building’s walkable location and front-desk model are exactly what command nightly premiums. For the operational side of running short-stay income in the city, our Airbnb investment Cape Town guide covers the City of Cape Town letting rules, occupancy patterns, and cost structure.
On returns, the discipline is simple. Prospekt’s marketing has cited net returns of up to 13.44%, and that number is DEVELOPER-CLAIMED and NOT guaranteed. It is the top of the developer’s own model, not a contractual or typical outcome. Independent CBD benchmarks are more conservative: a well-run unit more realistically models around 7% to 9% gross, compressing to roughly 5% to 7% net after levies, municipal rates, management and short-let commission, vacancy, insurance, and maintenance. Municipal rates are the line short-stay models forget most often, because the City bills them whether the unit is occupied or empty, exempting the first R620,000 of valuation and charging roughly 0.64 cents per rand a year above that. Underwrite the deal on the 5% to 7% net base case, treat any outperformance as upside, and never buy on the headline.
Insider tip: on an aparthotel, read the management agreement before the sale agreement. The term, the notice period, the commission split and whether the operator may pool your unit’s revenue with the rest of the building are what actually determine your income, and none of it appears on a price list. Ask specifically what happens if the operator walks away, because a 35-unit building with no front desk is a very different asset from the one you were shown.
What are the pros, cons, and realistic net yield for The Charlotte buyers?
Realistic net yield at The Charlotte is 5% to 7%, not the 13.44% in Prospekt’s marketing. Independent City Bowl stock models about 7% to 9% gross before levies, rates, management commission and vacancy. On an R1.695m studio that is roughly R119,000 of annual net income against roughly R228,000.
Pros
- Genuinely central Burg Street address with walkable access to the financial district and the Company’s Garden.
- Managed aparthotel layer gives hands-off short-stay income without self-running a listing.
- Boutique 35-unit scale supports a curated guest experience that mass blocks struggle to match.
- Entry from R1.695m keeps the studio format accessible for the City Bowl.
- UDZ depreciation can lift after-tax cash flow for a South African taxpayer.
Cons
- The DEVELOPER-CLAIMED 13.44% net return is not guaranteed and sits well above independent CBD benchmarks.
- Short-stay income is exposed to City of Cape Town regulation and seasonal swings.
- Management and hospitality commission sit between gross revenue and your net.
- Foreign buyers with no South African taxable income capture little or none of the UDZ benefit.
- CBD tenant churn is higher than in established residential suburbs.
On the number itself, build the model from the bottom. Independent City Bowl stock realistically models around 7% to 9% gross, compressing to roughly 5% to 7% net once levies, municipal rates, management and short-let commission, vacancy, insurance, and maintenance come out. That 5% to 7% net band is your base case. Rates alone follow the City schedule, with the first R620,000 of value exempt and roughly 0.64 cents per rand per year thereafter, and it is payable whether or not the unit is occupied. Work through the gross versus net mechanics before you accept any headline percentage.
Who should buy The Charlotte and who should skip the headline yield?
The natural buyer is someone who wants CBD short-stay exposure without becoming an operator. If you live offshore, cannot handle guest turnover from another time zone, and are comfortable paying a hospitality operator to run occupancy, the aparthotel structure does real work for you. The 35-unit scale and the front-desk model are the product you are paying for, and they justify accepting an operating fee that a self-managed owner would avoid.
The second good fit is a South African taxpayer with meaningful taxable income. The UDZ allowance is legislated rather than promotional, and accelerated building depreciation in the early years can change the after-tax picture materially. Verify it with an accountant, and remember that the allowance reduces your base cost, so some of the benefit reappears as capital gains tax at exit under the 40% inclusion rate for individuals.
Two buyers should walk away. Anyone underwriting on the 13.44% figure is buying a projection, not an asset: ask for actual booking data by month, and if it is not forthcoming, price the deal at 5% to 7% net or move on. And anyone who needs stable, predictable rent should look at long-let stock instead, because a CBD aparthotel’s income is seasonal by design. Before committing, confirm the handover date, NHBRC enrolment, the first-year body corporate budget, and the specific levy for your unit.
What red flags should Charlotte buyers treat as stop signals?
Four red flags are stop signals at The Charlotte: a yield quoted on furnished nightly lets with no winter occupancy stress test, parking and levy for your specific unit not confirmed in writing, net compared to Sea Point without a CBD churn adjustment, and the 13.44% headline used in place of a 5% to 7% base case.
- CBD yield quoted on furnished nightly lets without winter occupancy stress test.
- Parking and levy structure for the specific unit not confirmed in writing.
- Comparing Charlotte net to Sea Point apartments without adjusting for CBD tenant churn.
Which buyer profile fits The Charlotte cbd?
The Charlotte fits an offshore owner who wants CBD short-stay exposure without operating it, and a South African taxpayer who can use the UDZ allowance. Studios from R1.695m are the yield entry; two-bedroom lofts to R5.25m are owner-use stock. Buyers needing predictable monthly rent are better served by long-let suburbs.
| Buyer profile | Format | Entry | Base-case net |
|---|---|---|---|
| Offshore hands-off owner | Studio | From R1.695m | 5% to 7% |
| South African taxpayer using UDZ | One-bedroom | Mid-range | 5% to 7% plus UDZ relief |
| Owner-occupier | Two-bedroom loft | To R5.25m | Below 5% on owner-use |
| Predictable-rent investor | Long-let stock elsewhere | Varies | Compare Green Point |
Related reading:
Frequently Asked Questions
The Charlotte is a 35-unit boutique aparthotel by developer Prospekt at 20 Burg Street, on the corner of Hout and Burg in the Cape Town CBD. The mix spans studios, one-bedroom apartments, and two-bedroom lofts, with prices from R1.695m to R5.25m and a stated Q4 2025 completion target. It sits inside the City Bowl, a few minutes from St George's Mall, Greenmarket Square, and the Company's Garden, and is positioned for both short-stay and long-let income. The aparthotel format means a managed front desk and hospitality services, which suits owners who want hands-off short-letting rather than self-managed Airbnb.
Prospekt's marketing has cited net returns of up to 13.44%, but that figure is DEVELOPER-CLAIMED and NOT guaranteed. Treat it as a best-case projection from the developer's own model, not a contractual return. Independent City Bowl benchmarks are more conservative: well-run CBD apartments typically model around 7% to 9% gross and roughly 5% to 7% net once levies, rates, management fees, vacancy, and short-let commission are deducted. Before you offer, rebuild the numbers yourself on net using a verified rent, the specific unit's levy, and a realistic occupancy assumption, and ask for the developer's actual booking data rather than the headline percentage.
The Charlotte sits inside Cape Town's Urban Development Zone, which can allow a buyer to claim accelerated tax depreciation on the building portion of the purchase price against taxable income. For new builds the allowance has historically been generous in the early years, which can materially improve after-tax cash flow for South African taxpayers. The exact benefit depends on your tax position, the building-versus-land split, and current SARS rules, so the UDZ allowance MUST be verified with a qualified accountant or tax practitioner before you rely on it. Foreign buyers with limited or no South African taxable income may capture little or none of this benefit.
Yes. Foreigners can buy sectional title apartments at The Charlotte with very few restrictions and no foreign buyer surcharge, unlike the UK's 2% non-resident premium or Singapore's 60% additional stamp duty. Non-residents typically face tighter loan-to-value limits and often finance around half the price through a local bank, with the balance brought in as offshore capital. Record that offshore capital cleanly at entry through the South African Reserve Bank framework so funds and future gains repatriate without friction at exit. Note that foreign buyers usually cannot claim the UDZ depreciation unless they have South African taxable income.
The Charlotte suits a buyer who wants a managed, hands-off CBD aparthotel with both short-stay and long-let demand, plus potential UDZ tax upside for South African taxpayers. The location at 20 Burg Street is genuinely central and walkable, the 35-unit scale keeps it boutique, and entry from R1.695m is accessible for the City Bowl. The main caution is the developer-claimed 13.44% net return, which is NOT guaranteed and should be stress-tested against a more conservative 5% to 7% net base case. As an off-plan or near-completion purchase, also verify the completion date, the NHBRC warranty, the body corporate budget, and the levy before committing.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.