
City Bowl Cape Town: Property Prices by Altitude 2026
Every City Bowl suburb, Bo-Kaap to Vredehoek: modelled net yield from 6.0% down, why altitude sets the benchmark, and why Woodstock prices block by block.
By Cape Town Invest Editorial · Updated August 27, 2026 · 12 min read
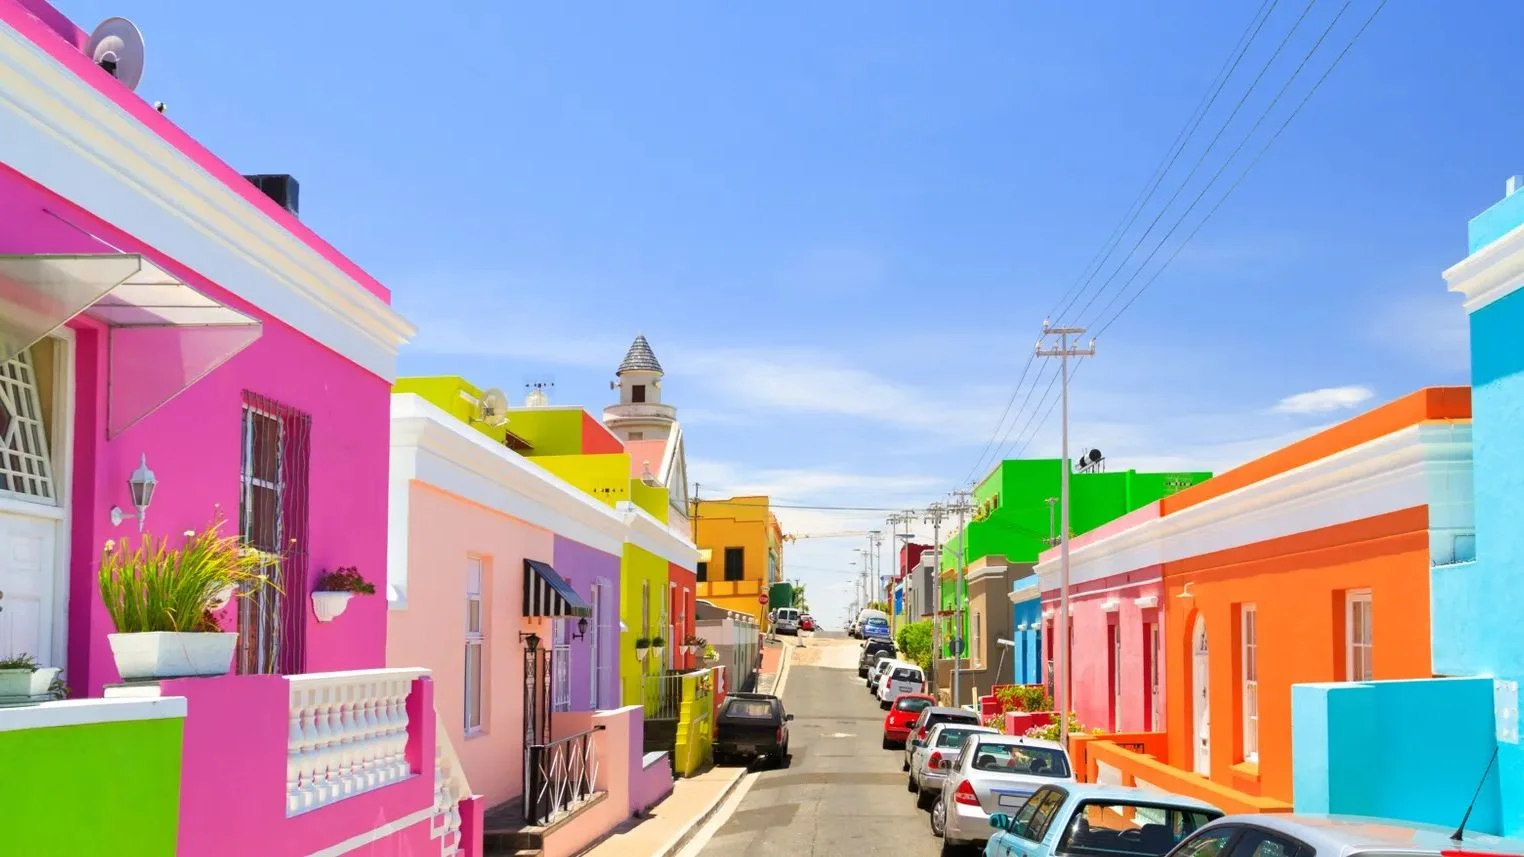
Quick answer: the City Bowl is sorted vertically rather than horizontally, and altitude decides what a property is for. The valley floor carries density, short-let demand and the strongest rental turnover; the upper slopes carry views, family tenants and growth instead of yield. The bowl models around 7.9% gross and 5.5% to 6.0% net, well above the Atlantic Seaboard, which is why the ridge line between them is the most consequential boundary in Cape Town property.
What counts as the City Bowl, and why does the boundary matter?
The bowl is a literal description rather than a marketing label. Table Mountain forms the back wall, Devil’s Peak closes the eastern side, Signal Hill and Lion’s Head close the west, and the harbour edge forms the open end. Everything inside that amphitheatre drains toward the CBD, which is why its suburbs stack vertically by altitude rather than spreading horizontally.
Two boundary calls decide which benchmark a listing should be underwritten against, and both are routinely blurred in marketing copy:
- Woodstock and Salt River sit east of Devil’s Peak and are outside the bowl geographically, but investors group them with it because the tenant pool and commute pattern are shared.
- Green Point and the V&A precinct sit west of Signal Hill and belong to the Atlantic Seaboard, even when agents describe them as city-adjacent.
That second call carries real money. Inside the bowl, long-let stock models 5.5% to 6.0% net; on the prime Seaboard the same capital models nearer 4.4%, as the Atlantic Seaboard guide sets out rung by rung. Cape Town Invest checks the ridge before the listing photographs, because a City Bowl description applied to a Green Point apartment is not a lie, it is a different investment.
How does altitude sort the market?
Altitude does the work that distance does in flatter cities. The bowl’s floor is dense, transit-served and rented hard; its upper slopes are quiet, view-led and held long. The gradient is steep enough that walking distance to Kloof Street is downhill in one direction and a workout in the other, and that shows up in what a tenant will pay.
| Zone | Suburbs | Investment character |
|---|---|---|
| Valley floor | CBD, Bo-Kaap fringe, De Waterkant | Density, compact buy-to-let, short-let demand |
| Lower slopes | Gardens, Tamboerskloof | Balanced income, deepest tenant pool |
| Upper slopes | Oranjezicht, Vredehoek, Higgovale | Views, family residential, growth led |
| Eastern extension | Woodstock, Salt River, Zonnebloem | Lower base, regeneration upside, uneven |
The consequence for an investor is that the bowl cannot be bought as a single market. Its internal spread is wider than the gap between the bowl and the Seaboard: Woodstock’s net sits about half a point above Gardens and a full point above De Waterkant, while its execution risk is several times higher. A buyer who picks the bowl and then picks a street has made two decisions, and the second one matters more.
A worked example puts numbers on it. Two R2.4 million apartments, one in Woodstock at 6.0% modelled net and one in De Waterkant at 5.5%, differ by R12,000 a year on paper. Give the Woodstock unit one extra month of vacancy from a street that has not turned, and the gap closes entirely; give it a R60,000 special levy for security upgrades the block deferred, and five years of the advantage disappears. The yield table ranks the suburbs correctly and predicts nothing about either unit, which is why the checks in the Woodstock section below are not optional extras.
What do the bowl’s suburbs yield, and why do they differ?
Yields inside the bowl cluster tightly on gross and separate on net, which tells you the differences are about cost and entry price rather than about rental demand. Gardens and Tamboerskloof both model near 7.8% gross on long lets, and the net figures below explain where that ends up.
| Suburb | Modelled net | What drives it | Suburb page |
|---|---|---|---|
| Woodstock | ~6.0% | Lowest entry price in the bowl’s tenant catchment | Woodstock |
| Gardens | ~5.7% | Deep tenant pool, mid-range levies | Gardens |
| Tamboerskloof | ~5.6% | Established residential, professional tenants | Tamboerskloof |
| De Waterkant | ~5.5% | Heritage stock above R3 million, lifestyle competition | De Waterkant |
| Oranjezicht and Vredehoek | mid range | Views priced in, family tenants on long leases | this page, altitude section |
Five more addresses complete the bowl and none of them behaves like the five above. The City Centre is the only part that trades as conversion stock rather than residential streets, and it carries the largest schemes: Zero2One at 624 units and The Charlotte at 35 sit within a few blocks of each other. Bo-Kaap and Schotsche Kloof are heritage-protected, which caps what an owner can change and keeps stock scarce. Higgovale sits above Tamboerskloof with the bowl’s largest erven and its thinnest transaction volume. Zonnebloem and University Estate are the eastern slope, closest to Woodstock in price and to the CBD in commute. Salt River is filed into the bowl by the City and into the Southern Suburbs by most agents, which is worth knowing before you compare two listings on the same street.
| Suburb | Position | Why it prices differently |
|---|---|---|
| City Centre | The flat, north of the ridge | Conversion and new towers, not houses |
| Bo-Kaap | West slope above the CBD | Heritage protection caps alteration |
| Schotsche Kloof | Above Bo-Kaap | Same heritage constraint, quieter streets |
| Higgovale | Above Tamboerskloof | Largest erven, thinnest volume |
| Zonnebloem and University Estate | Eastern slope | Woodstock pricing with a shorter commute |
Rental turnover is the variable most buyers underweight. The lower bowl re-lets in weeks because it serves professionals working in the CBD and students at the nearby campuses; the upper slopes re-let in months because the tenant pool is families choosing a specific school run and a specific view. A two-month void on the upper slopes costs more than the yield gap it was bought to capture, which is why our analysis of bowl stock underwrites vacancy by zone rather than applying one allowance across the market. The rental yield guide covers the modelling method.
Why is Woodstock priced block by block?
Woodstock produces the bowl’s firmest net yield and its widest dispersion, and both come from the same fact: it gentrifies street by street rather than uniformly. A regenerated road with secure blocks, cafes and a working body corporate can sit one or two streets from a road that has not turned at all.
That unevenness makes suburb-level averages actively misleading, so three checks replace them:
- Transacted comparables for the exact block, not the suburb, because a Deeds Office average across Woodstock spans stock that is not comparable.
- The street at different hours, since daytime and evening character diverge more here than anywhere else in the bowl.
- The body corporate financials and reserve fund, because building security and deferred maintenance vary far more than in the upper bowl.
Insider tip: in Woodstock, ask when the building last did a security upgrade and who paid for it. A block that funded access control and lighting from reserves has a body corporate that plans; one that raised a special levy for it has a body corporate that reacts, and the next repair will arrive the same way.
What does De Waterkant’s tourism premium actually buy?
De Waterkant carries the bowl’s softest modelled net at about 5.5%, and the reason is entry price rather than weak rent. Boutique heritage cottages and small schemes above R3 million draw lifestyle buyers and short-let operators competing for the same limited stock, so prices run ahead of what long-let rent supports.
What the premium buys is tourism depth. Proximity to the V&A precinct, walkable dining and business-travel demand hold peak-season occupancy high enough that short-let gross can exceed the 7.8% long-let benchmark. Whether that upside reaches a specific unit depends on two permissions rather than on the market: the City’s short-term letting requirements, now moving through a draft by-law, and the body corporate’s conduct rules, which can prohibit under the STSMA what the City allows. Rebuild the numbers on the long-let fallback near 5.5% net before offering, so the purchase still stands if either changes. The body corporate rules guide covers how a scheme restricts nightly letting and what binds an owner who bought before the vote.
Does the CBD conversion pipeline change the stock profile?
Conversion is the bowl’s only meaningful source of new supply, because a market closed by mountain on three sides cannot expand outward. Office-to-residential projects in the CBD therefore shape what a buyer can actually purchase here over the next decade, and they skew toward one product.
Converted floorplates deliver compact apartments aimed at renters rather than family homes, which reinforces the valley floor’s existing character: high density, high turnover, short leases and a tenant profile that follows employment rather than schools. For an income investor that is helpful, because it deepens the rental pool a compact unit competes in. For a growth investor it is a caution, since a floor of new compact stock arriving each year is the most direct competitor to an older compact unit at resale. Three questions separate a good conversion from a bad one, and none of them is about the finishes:
- What is the floorplate depth? Deep office floors produce apartments with poor natural light in the middle, which shows up as slower letting rather than lower rent.
- What happened to the parking? Office parking ratios rarely match residential demand, and a conversion short of bays competes badly in a city where most tenants drive.
- Who runs the body corporate in year one? A developer-controlled scheme sets the first budget, and an underfunded reserve becomes the buyer’s special levy in year four.
The new developments guide tracks what is in the pipeline, and the off-plan guide covers buying into it before completion.
What is the outlook for the bowl?
The bowl enters 2026 with the structural advantage that its supply cannot answer demand quickly, and the structural exposure that its income depends on a rental market rather than on trophy buyers. Prime at 10.5% still sets the hurdle every cash purchase is measured against, and a rate cut reaches the bowl through affordability rather than through prestige demand.
Two specific things are worth watching. The draft short-term letting by-law would land hardest on the valley floor, where nightly-let stock concentrates, and barely touch the upper slopes. The conversion pipeline works the other way, adding compact rental stock to exactly the zone the by-law would constrain. Cape Town Invest reads the combination as a reason to underwrite valley-floor purchases on long-let numbers and to treat any short-let upside as optional rather than as the case for the deal. For the market the bowl is most often compared against, see the Atlantic Seaboard guide; for the leafier alternative on the other side of Devil’s Peak, see the southern suburbs guide.
One central scheme worth reading before pricing a CBD resale is the Venice House review.
Sources: Sectional Titles Schemes Management Act 8 of 2011 for conduct rules and the special resolution threshold; City of Cape Town draft short-term letting by-law, August 2026; SARB repo rate and prime lending rate as at August 2026. Yields are modelled from listing and platform bands rather than audited accounts, and are directional. Verify levies, rates and achievable rent for the specific block before offering. Current as at 27 August 2026.
Frequently Asked Questions
The bowl is a literal amphitheatre: Table Mountain forms the back wall, Devil's Peak closes the east, Signal Hill and Lion's Head close the west, and the harbour is the open end. Inside it sit the CBD, Bo-Kaap, De Waterkant, Gardens, Tamboerskloof, Oranjezicht, Vredehoek and Higgovale. Woodstock and Salt River lie east of Devil's Peak and are outside the bowl geographically, while Green Point and the V&A sit west of Signal Hill and belong to the Atlantic Seaboard.
Because the ridge decides which yield benchmark applies. Inside the bowl, long-let stock models around 7.8% gross and 5.5% to 6.0% net. West of Signal Hill, on the Atlantic Seaboard, the same money buys a net yield closer to 4.4% in the prime suburbs. Agents market both as city-adjacent, so a listing described as City Bowl but sitting in Green Point should be underwritten against the Seaboard ladder, not the bowl's.
Around 7.9% gross across the bowl and 5.5% to 6.0% net after levies, rates, maintenance and vacancy. Gardens and Tamboerskloof model near 7.8% gross on long lets, Woodstock produces the firmest net near 6.0% because entry prices are lowest, and De Waterkant models the softest at about 5.5% because heritage stock above R3 million attracts lifestyle buyers competing with investors. All figures are modelled and directional.
It carries the bowl's strongest net yield and its widest execution risk, because Woodstock gentrifies block by block rather than uniformly. A regenerated street with secure blocks and cafes can sit one or two roads from a street that has not turned. That makes suburb-level averages close to useless: verify transacted comparables for the exact block, walk the street at different hours, and read the body corporate financials and reserve fund before anchoring on any Woodstock yield.
Because the bowl is closed on three sides by mountain and on the fourth by the harbour, so new stock arrives only by building upward or by converting existing buildings. That is why the CBD's office-to-residential conversion pipeline matters more here than anywhere else in Cape Town: it is the main source of new apartments in a market that cannot expand outward, and it tends to deliver compact units aimed at the rental market rather than family homes.
De Waterkant, Bo-Kaap and the CBD carry genuine tourism and business-travel demand, and short-let gross can exceed the 7.8% long-let benchmark there. Two permissions decide whether it is available on a specific unit: the City's short-term letting requirements and the body corporate's conduct rules, and the second can prohibit what the first allows. Underwrite the long-let fallback near 5.5% net so the deal survives either changing.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.