
Best Areas to Invest in Cape Town 2026 (By Buyer Goal)
Best areas to invest in Cape Town 2026 by buyer goal: Atlantic Seaboard, City Bowl, Century City, Southern Suburbs and Winelands, with modelled yields and fit.
By Cape Town Invest Editorial · Updated August 21, 2026 · 17 min read
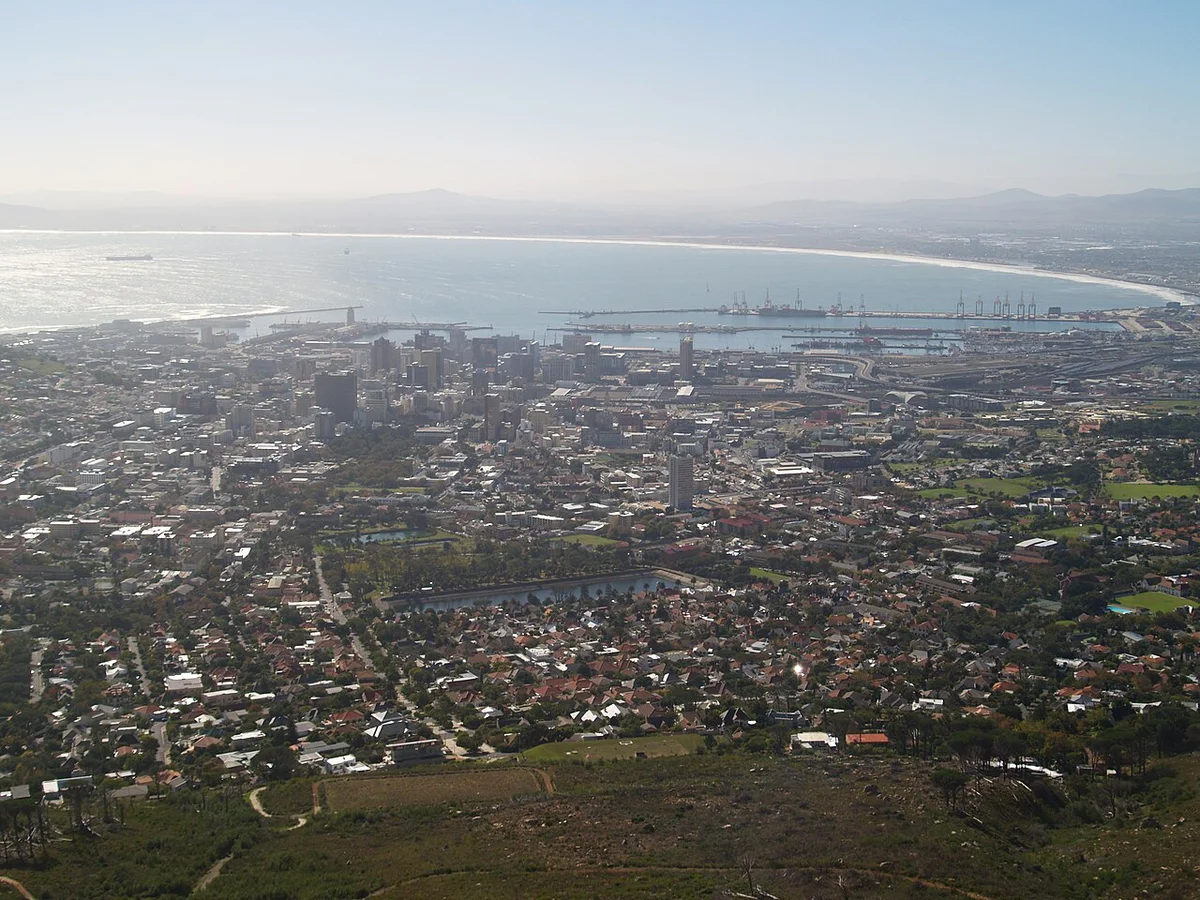
Quick answer: the best area depends on your goal
There is no single best area to invest in Cape Town in 2026. There is only the best area for what you want the money to do. An income-first buyer, a capital-preservation buyer and a lifestyle-and-semigration buyer should each end up in a different suburb, even with the same budget.
On a modelled basis, the pattern is consistent across the city. Sea Point, on the Atlantic Seaboard, models the strongest income, around 9.7% gross and 7.5% net on a one-bedroom apartment, because its entry price per unit is lower than the trophy suburbs while rental demand stays high. Camps Bay, a few minutes down the coast, models only about 6.8% gross and 4.4% net, because capital values are so high that rent cannot keep pace, so the return arrives as growth, scarcity and resale liquidity rather than cash flow.
Every yield figure in this guide is modelled and directional, built from typical prices and rents rather than a single live listing. Use the area table below as a framework to match your goal to a suburb, then read the deeper the metro investment guide for the city-wide market context.
| Area | Modelled yield profile | Investment character | Best buyer fit |
|---|---|---|---|
| Atlantic Seaboard, Sea Point | ~9.7% gross / ~7.5% net | Income node of the prestige strip | Income-first and hands-off foreign buyers |
| Atlantic Seaboard, Camps Bay | ~6.8% gross / ~4.4% net | Capital preservation, prestige, scarcity | Trophy, lifestyle and growth buyers |
| City Bowl | Mid yield, balanced | Walkable urban demand, deep rental pool | Balanced income-and-growth, urban tenants |
| Century City | Moderate, steady long-let | Secure managed estate, lock-up-and-go | Lower-entry, hands-off and foreign buyers |
| Southern Suburbs (Constantia, Rondebosch) | Moderate, growth-led | Family homes, schools, long-term tenants | Family-home and stable long-let buyers |
| Cape Winelands (teaser) | Emerging, lifestyle-led | Semigration, estate and lifestyle demand | Lifestyle, second-home and semigration buyers |
Atlantic Seaboard: Sea Point for yield, Camps Bay for capital
The Atlantic Seaboard is Cape Town’s prestige coastal strip, running from Green Point and Sea Point through Bantry Bay and Clifton to Camps Bay. It is also where the two clearest investment archetypes in the city sit side by side, which is why it deserves the most space.
Sea Point is the income engine. It combines higher density, lower entry prices per unit than the trophy suburbs, and strong year-round rental demand from locals, professionals and tourists. That mix lifts modelled yields to around 9.7% gross and 7.5% net on a one-bedroom apartment, the strongest income profile on the strip while still offering a coastal address with resale depth. For a hands-off foreign buyer who wants rand income with reliable management, Sea Point is usually the first place to look.
Camps Bay is the capital play. Entry prices are very high relative to achievable rent, so income compresses to a modelled 6.8% gross and 4.4% net. That is not a weakness, it is the point: Camps Bay buyers are paying for scarcity, brand recognition, a beachfront lifestyle and the resale liquidity that prime trophy stock holds through cycles. The return shows up as capital value and currency upside, not monthly cash flow.
For the full suburb-by-suburb breakdown, prices per square metre and trophy-sale records, read the dedicated Atlantic Seaboard property investment guide.
Combined Atlantic Seaboard and City Bowl sales reached R11.3 billion in 2025, up 26 percent year on year, with foreign buyers taking roughly 25 percent of value near R2.8 billion and luxury sales above R20 million hitting R4.2 billion, up 61 percent. On modelled one-bedroom stock, Sea Point shows roughly 9.7 percent gross and 7.5 percent net because entry prices per unit stay below Camps Bay while rental demand stays year-round, whereas Camps Bay models only 6.8 percent gross and 4.4 percent net because capital values compress income. Foreign buyers face zero foreign-buyer surcharge on transfer duty unlike Singapore’s 60 percent ABSD on foreign residential purchases, but must still route funds through an authorised dealer and secure the non-resident endorsement before transfer.
City Bowl: balanced urban demand under the mountain
City Bowl demand is the broadest in Cape Town: young professionals, hybrid workers, semigration arrivals and tourists compete for the same stock under the mountain. Modelled yields sit in the mid band, below Sea Point’s 9.7% gross but typically firmer than Camps Bay’s 6.8%, with growth from urban renewal and limited new supply.
That breadth keeps long-let occupancy steady and gives short-let stock a genuine tourist premium in season, with apartments near the cafes, galleries and the V&A Waterfront drawing the deepest pool on the slopes.
The City Bowl suits a buyer who wants one address to do two jobs: produce respectable rand income and participate in the capital growth of a supply-constrained, internationally recognised inner city. As with the rest of Cape Town, model a long-let fallback even if your plan relies on short-letting, because body corporate rules and short-term-rental regulation are tightening.
Century City: lower entry, managed, lock-up-and-go
Century City is a purpose-built precinct rather than an organic suburb: sectional title apartments with offices, retail and managed common areas behind estate security, off the N1. The format matters more than the address, because it removes the maintenance burden and trades away the view scarcity behind Camps Bay’s 4.4% net capital story.
Almost everything sits inside a professionally run body corporate, so the security, garden and maintenance burden that makes a Southern Suburbs family home hands-on largely disappears.
That suits two buyers in particular. The overseas owner who visits twice a year and needs the unit to look after itself, and the investor priced out of the Atlantic Seaboard who wants a defensible long-let rather than a trophy. Tenants are mostly professionals working in the precinct’s own offices and families buying security plus a short commute, which produces steadier occupancy than tourist-driven stock and no exposure to tightening short-term rental bylaws.
The trade-off is the growth ceiling. There is no view scarcity and new phases keep arriving, so appreciation tracks rental demand rather than fixed supply, and nothing here will behave like Camps Bay’s 4.4% net capital story. Levies also run higher than an equivalent older block because the security and common areas are extensive, so read the levy schedule and reserve fund balance before you model net. Weigh the profile against the Northern Suburbs alternative in Century City vs Durbanville.
West Coast corridor: Blouberg, Table View and Durbanville
The West Coast corridor north of Century City is coastal lifestyle at lower tickets than an Atlantic Seaboard where Sea Point models 9.7% gross. Blouberg leads on Table Mountain views and family semigration, Table View adds commuter-beach apartments, and Durbanville holds Northern Suburbs family stock with wine-route adjacency.
Rietvlei wetland access is part of the Table View draw for owner-occupiers. Use the Cape Town property prices by suburb 2026 table to compare R/m² bands before you shortlist.
False Bay: Kalk Bay lifestyle investment
Around the peninsula on the warmer False Bay side, Kalk Bay is the fishing-village alternative to the Atlantic coast. Stock is mostly heritage cottages and small village homes stacked above a working harbour, and the buyer is usually a semigration or European lifestyle owner rather than a pure yield investor. Modelled returns land near 6.5% gross and 5% net, which sits between Sea Point’s 7.5% net and Camps Bay’s 4.4% net, so the income is real without being the headline.
Two things separate Kalk Bay from the areas above. Demand is seasonal in a way the City Bowl’s is not: summer tourism and the Cape Point route fill short-let calendars, while winter occupancy thins, so a blended long-let and seasonal model underwrites more honestly than a peak-season projection. And the building stock is old. Heritage cottages carry damp, roof, and structural maintenance that a 2020-built Century City apartment does not, and that maintenance line is what usually separates the modelled net from the achieved one. Budget it explicitly rather than as a rounding error.
Kalk Bay works for a buyer who wants character, a genuine village, and a defensible income floor, and who accepts thinner liquidity and a longer sale timeline than the Atlantic Seaboard. It is a poor fit for anyone who needs to exit quickly or who is underwriting to a 7% net hurdle. See the Kalk Bay and False Bay area guide for stock types and price bands.
Trophy seaboard: Llandudno capital preservation
Llandudno is the far end of the risk-return spectrum from the value belt above. Fewer than 200 freehold homes share a single west-facing beach, there is no commercial strip, no hotel, and no through-traffic, and that absolute scarcity is the entire investment case. Modelled net yields sit near 3.5%, below even Camps Bay’s 4.4%, and nobody buys here for cash flow.
What you are buying is a wealth store denominated in rand but priced by global demand. The supply of Llandudno houses cannot expand: the suburb is boxed in by mountain and sea, and the homes that exist rarely trade. That produces resilient pricing through cycles, because a downturn does not create new inventory. The corresponding cost is liquidity. Transaction volumes are a fraction of Camps Bay’s, so an exit is measured in quarters rather than weeks, and the buyer pool for a R30m-plus enclave home is small and international.
Treat Llandudno the way you would treat an allocation to a scarce physical asset: size it as a portion of net worth you do not need to access, hold it for a decade or longer, and pair it with an income asset elsewhere in the city if the portfolio needs cash flow. It is the wrong first purchase in Cape Town and often the right third one. Read the Llandudno area guide alongside the Atlantic Seaboard guide before shortlisting.
Southern Suburbs: Constantia and Rondebosch for families and long lets
The Southern Suburbs run along the eastern side of Table Mountain, from Rondebosch and Newlands through Claremont to the Constantia estates, and the thesis is stability rather than tourist yield. Yields are moderate against Sea Point’s 7.5% net, and vacancy is lower, because schools and the University of Cape Town anchor demand.
Constantia is the green, low-density end: large plots, wine estates, and high-value family homes that hold their worth and draw affluent long-term tenants and semigration buyers relocating from Johannesburg or abroad. Yields are moderate because capital values are high, but the area offers strong capital preservation and a deep buyer pool on resale.
Rondebosch, Newlands and Claremont are the denser, school-and-university belt. Demand is anchored by some of the country’s top schools and by the University of Cape Town, which keeps a steady stream of family and student-adjacent tenants. That underpins reliable long-let occupancy and modest, dependable yield, with apartments and townhouses offering a lower entry point than Constantia’s estates.
The Southern Suburbs suit a buyer who prioritises tenant quality, low vacancy and hold stability over the higher gross yields of the high-density Atlantic Seaboard income suburbs. It is a long-term, family-tenant market, not a short-let tourist market, so model long-let income and a multi-year hold from the outset. Drill into the cluster via the Southern Suburbs hub and the Rondebosch area guide.
Cape Winelands: the emerging lifestyle and semigration teaser
The Cape Winelands around Stellenbosch, Franschhoek and Paarl is the area to watch rather than the area to anchor an income portfolio. Semigration and lifestyle demand are reshaping it quickly, but yields are lifestyle-led rather than optimised, and liquidity is thinner than in a city node modelling 7.5% net.
The driver is South Africa’s internal migration toward the Western Cape, plus a wave of remote and hybrid professionals who want space, security and scenery within reach of Cape Town. Estate living, vineyard lifestyle and strong schools in Stellenbosch support rising capital values and a growing rental pool. Yields are emerging and lifestyle-led rather than income-optimised, and liquidity is thinner than the city, so the Winelands suits a second-home, lifestyle or semigration buyer with a longer horizon rather than a yield-first investor. Treat it as a diversification or lifestyle allocation alongside a core Cape Town holding.
The inner-city value belt: where yield-hunters look next
Woodstock, Salt River and Observatory trade prestige for a stronger rent-to-price ratio, modelling gross yields near 7.8% in Woodstock and 7.8% to 9.2% in Observatory, on tickets from R2.5 million to R3.5 million for one-bedroom stock. Entry prices per unit are materially lower than Sea Point, the stock is older, and the levy audit does the real work.
These suburbs sit between the City Bowl and the Southern Suburbs, where rental demand from students, young professionals and the creative economy stays firm, so modelled gross yields can match or exceed the prime income suburbs at a fraction of the entry cost.
The trade-off is honest. Stock tends to be older, maintenance is heavier, tenant screening matters more, and capital-growth depends on continued urban regeneration rather than scarcity. These are working investor suburbs, not lifestyle ones, and they reward a hands-on owner or a strong local manager. For a first-time investor learning the market at a lower entry point, or an income-first buyer who does not need a sea view, the value belt is the logical complement to the headline areas above. Underwrite the rent conservatively and the levy carefully, because the gross-to-net gap is what separates a good buy from a tired one.
Woodstock, Salt River, and Observatory model gross yields near 7.8 percent in Woodstock and 7.8 to 9.2 percent in Observatory, on tickets from R2.5 million to R3.5 million for one-bedroom stock, but levies from R1,800 to R3,200 monthly plus rates near R900 to R1,400 compress net yield by 1.5 to 2.0 percentage points before vacancy at 8 to 10 percent and management at 8 to 12 percent. A R3 million Observatory flat at R24,000 monthly rent collects R288,000 a year and models 9.6 percent gross. Take off R38,400 of levies, R14,400 of rates, R28,800 of rent lost to a 10 percent vacancy allowance and R25,920 of management at 9 percent, and R180,480 is left: 6.0 percent net. A third of the headline yield goes to costs the listing does not mention, which is why a levy audit matters as much as the rent. Compare that to Sea Point at R4 million with stronger resale depth but similar net after costs, and choose the node that matches your hands-on capacity and hold period.
How to choose between these areas
Choosing well is less about picking a winner than matching the area to the job your capital must do, because the spread runs from Sea Point at a modelled 7.5% net to Llandudno near 3.5%. Work through the six steps below before you commit to a suburb or a budget.
- Define the goal first. Income, capital growth, lifestyle, or semigration. The goal, not the postcode, decides the area.
- Match the area to the goal. Income leans Sea Point and the City Bowl; capital and prestige lean Camps Bay; stability and family tenants lean the Southern Suburbs; convenience and low entry lean Century City.
- Underwrite the yield yourself. Treat every figure here as modelled. Build your own gross-to-net using the method in the Cape Town rental yield guide, with honest vacancy, levy, rates and management costs.
- Confirm the letting model. If your plan relies on short-letting, get the body corporate rules in writing first, and always model a long-let fallback.
- Sort the foreign-buyer setup early. Arrange the non-resident endorsement and authorised-dealer banking before you transfer funds, as detailed in the buying as a foreigner hub.
- Budget the full cost stack. Transfer duty, conveyancing and other acquisition costs change your effective entry price and therefore your yield, covered in the cost of buying property in Cape Town guide.
What are the pros and cons of each area at a glance?
No Cape Town area is one-sided, and every trade-off is priced: Sea Point buys 9.7% gross income at higher density, Camps Bay buys scarcity at 4.4% net, and Century City buys convenience with a growth ceiling. The table below sets the main advantage against the main trade-off in each area.
| Area | Main advantage | Main trade-off |
|---|---|---|
| Sea Point | Strongest modelled income on the prime strip | Higher density, less exclusivity than trophy suburbs |
| Camps Bay | Prestige, scarcity, resale liquidity | Lowest modelled net yield, capital-led only |
| City Bowl | Balanced income and growth, deep tenant pool | Short-let regulation, body corporate rules tightening |
| Century City | Low entry, secure, easy to manage | Limited capital-growth ceiling, no sea view |
| Southern Suburbs | Tenant quality, stability, family demand | Moderate yield, longer hold needed |
| Cape Winelands | Rising lifestyle and semigration demand | Thinner liquidity, emerging and lifestyle-led |
Head-to-head comparisons when two areas feel close
Two nodes that feel close on gross yield usually differ on tenant type and hold period, which is what the compare pages isolate. Sea Point models 9.7% gross against Camps Bay’s 6.8% on the same coastline, and a gap of that kind separates most of the pairs listed below.
- Century City vs Durbanville frames corporate sectional title against Northern Suburbs family homes.
- Somerset West vs Constantia contrasts Helderberg value yield against southern suburbs prestige.
- Paarl vs Stellenbosch splits Winelands towns on entry price and income.
- Cape Town vs Johannesburg and Cape Town vs Mauritius sit outside suburb choice, but help offshore buyers benchmark South Africa against other destinations.
The bottom line for 2026
The spread between the areas in this guide is wider than most buyers expect. On modelled numbers a Sea Point one-bedroom returns roughly 7.5% net while a Camps Bay apartment a few kilometres away returns about 4.4%, and Llandudno sits near 3.5%. Those are not better and worse suburbs. They are three different products, and the mistake that costs the most money is buying one while expecting the other’s return profile.
The demand backdrop is genuinely strong. Combined Atlantic Seaboard and City Bowl sales reached R11.3 billion in 2025, up 26% year on year, with luxury transactions above R20 million at R4.2 billion, up 61%, and foreign buyers taking roughly 25% of value near R2.8 billion. Semigration keeps adding domestic demand across the Southern Suburbs, Century City, and the Winelands. Nothing in that picture argues for waiting on the sidelines for a better entry point.
What it does argue for is discipline in three places. Rebuild every yield figure in this guide on net, using the actual levy and rates for the specific block rather than an area average. Confirm the letting model in writing before you underwrite short-let income, because City Bowl bylaws and body corporate rules are tightening. And if you are buying from abroad, arrange the authorised-dealer banking and non-resident endorsement before funds move, not after an offer is accepted. Foreigners pay no buyer surcharge here, which is a real advantage over the UK or Singapore, but the process still rewards preparation. Match the area to the job, underwrite honestly, and the suburb choice does most of the work.
Insider tip: do not pick a Cape Town suburb from gross yield alone
Levy spreads erase 2 or more net yield points between otherwise similar Atlantic Seaboard blocks, which is why a single gross-yield screenshot is the most expensive shortcut in Cape Town. Trophy buyers hunting a 6% net hurdle on R15 million stock rarely clear it, because modelled net there sits near 4.4%.
Foreign buyers took roughly 25 percent of Atlantic Seaboard and City Bowl value in 2025 near R2.8 billion, yet still need authorised-dealer banking and the non-resident endorsement with zero foreign-buyer surcharge on transfer duty. City Bowl short-let plans face tightening bylaws, so model long-let fallback before you underwrite Airbnb income on a R3.5 million Gardens apartment.
What area-picker red flags should pause your Cape Town shortlist?
Area-picker red flags are a suburb comparison built on gross rent while levy spreads erase 2 or more yield points, a trophy strip bought for income when the hurdle needs 6% net against a modelled 4.4%, and a City Bowl short-let model written before the bylaws are checked.
- Comparing suburbs on gross rent while ignoring levy spreads that can erase 2+ yield points.
- Buying Camps Bay or Clifton for income when your hurdle rate needs 6%+ net; trophy strips rarely clear that bar.
- Ignoring short-term rental bylaws in the City Bowl before you model Airbnb income.
- Skipping due diligence because the area “always performs.”
Which buyer profile fits which Cape Town area fits your goal?
Buyer profile, not a ranking, is what decides the suburb. Income-first buyers start with Sea Point and City Bowl apartments near a modelled 7.5% net, capital and prestige buyers accept sub-5% net in Camps Bay and Clifton, and semigration families weigh Southern Suburbs schools against lower vacancy.
Income-first buyer: Start with Sea Point and City Bowl apartments on net yield. Century City works if you want lower entry and sectional-title simplicity.
Capital and prestige buyer: Camps Bay, Clifton, and Bantry Bay trade liquidity and scarcity for sub-5% net. Accept that trade or move to a different area.
Semigration family: Southern Suburbs and Constantia win on schools and long-let depth; yields are moderate but vacancy is usually lower.
Winelands or coast lifestyle: Stellenbosch, Franschhoek, or Hermanus for a longer hold and lifestyle use; pair with a city income asset if you need cash flow.
Frequently Asked Questions
There is no single best area, only the best area for your goal. For income, Sea Point on the Atlantic Seaboard models the strongest yields, around 9.7% gross and 7.5% net on one-bedroom apartments. For capital preservation and prestige, Camps Bay leads but models lower yield near 6.8% gross and 4.4% net. For balanced urban demand, the City Bowl and Green Point work well, while Century City suits lower-entry, managed lock-up-and-go buyers and the Southern Suburbs suit family and long-term tenants. All yields are modelled and directional, not guaranteed.
On a modelled basis, Sea Point shows the strongest yield among prime areas, around 9.7% gross and 7.5% net, because its entry prices per unit are lower than Camps Bay or Clifton while rental demand stays high year-round. Mid-priced inner suburbs such as Observatory and Woodstock can model similar or higher gross yields at lower entry prices. These are directional models built from typical prices and rents, not promises.
Foreign buyers most often choose the Atlantic Seaboard for prestige and resale liquidity, the City Bowl for walkable urban demand, and Century City for managed, lock-up-and-go convenience. Foreigners pay no buyer surcharge in South Africa, unlike the UK or Singapore, and took roughly 25% of Atlantic Seaboard and City Bowl value in 2025. Whichever area you pick, set up the non-resident endorsement and authorised-dealer banking before you transfer funds.
It depends on your objective. Camps Bay is a capital-preservation and lifestyle play: very high entry prices compress income to a modelled 6.8% gross and 4.4% net, so the return arrives mainly as growth and scarcity. Sea Point is the income node of the strip, modeling around 9.7% gross and 7.5% net because units cost less per square metre while demand is strong. Income-first buyers lean Sea Point; trophy and growth buyers lean Camps Bay.
Century City suits buyers who want a lower entry price, a secure managed estate, and lock-up-and-go convenience near the N1 and Cape Town's commercial nodes. It models moderate yields with steady long-term tenant demand from professionals and families, and the estate format reduces maintenance friction for hands-off and foreign owners. It trades the sea view and prestige of the Atlantic Seaboard for affordability, security and rental stability.
The Southern Suburbs, including Constantia, Rondebosch, Newlands and Claremont, suit family-home and long-term rental buyers rather than short-term tourist yield. Demand is driven by top schools, the University of Cape Town, and leafy residential appeal, which supports stable long-let occupancy and capital growth. Yields are typically moderate, below the high-density Atlantic Seaboard income suburbs, but tenant quality and hold stability are strong.
No. Every yield figure in this guide is modelled and directional, built from typical purchase prices, rents and cost assumptions for each area. Actual returns depend on the specific property, the price you pay, occupancy, the levy on your block, and how the unit is managed. Treat the numbers as a planning framework for comparing areas, not a promise of return.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.