
Cape Town vs Stellenbosch 2026: Depth Against Concentration
Cape Town spreads demand across a metro economy. Stellenbosch concentrates it on one university and one small market, which changes both yield and exit risk.
By Cape Town Invest Editorial · Updated August 27, 2026 · 11 min read
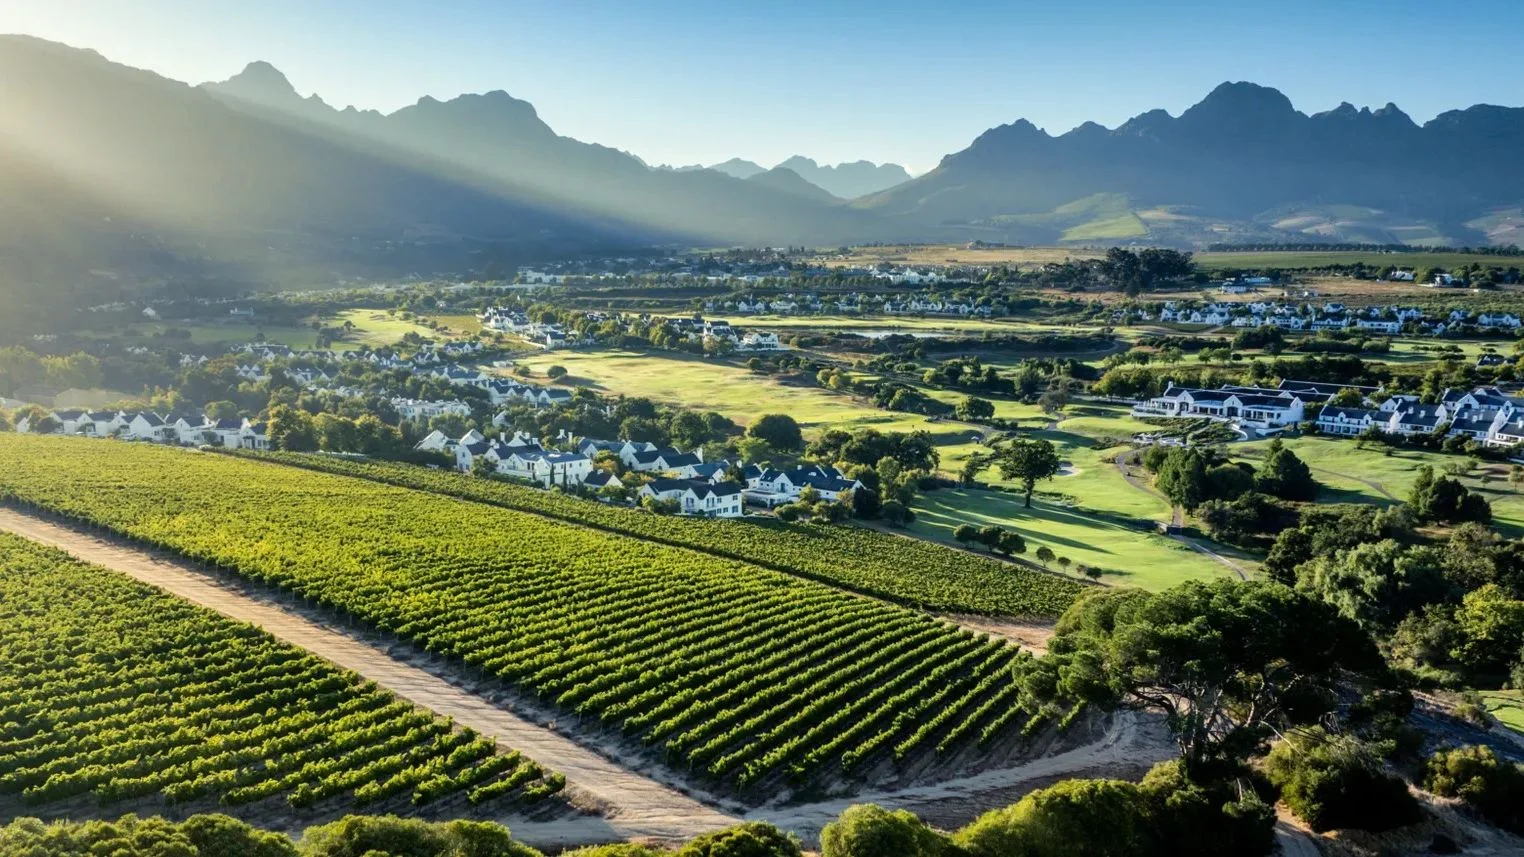
Quick answer: this is a comparison between a diversified market and a concentrated one. Cape Town spreads rental demand across a metro economy, so no single employer moves it, and transacts continuously enough that a seller has comparables and buyers. Stellenbosch concentrates demand on one university and its surrounding economy, which produces reliable seasonal tenancies and a market where one institution’s decisions matter more than the property cycle.
What does demand concentration actually change?
It changes what a landlord is exposed to. In a metro, rental demand comes from many independent sources, so the failure of any one of them is absorbed. In a university town, a large share arrives through a single institution.
| Dimension | Cape Town metro | Stellenbosch |
|---|---|---|
| Demand sources | Offices, tourism, services, public institutions | University, its staff, surrounding businesses |
| Letting calendar | Continuous, varies by suburb | Concentrated before the academic year |
| What moves the market | Employment and interest rates | Enrolment, residence policy, institutional decisions |
| Landlord visibility | Ordinary market information | Decisions made inside one institution |
The practical consequence is not that Stellenbosch is riskier in a general sense, it is that its risk has a different shape. A new university residence opening, a change in how the institution houses first-years, or a shift in enrolment moves a large slice of the rental market at once, and a landlord learns about it after the fact. A Cape Town suburb absorbs an equivalent shock because nothing supplies most of its tenants. The Rondebosch page covers what an academic calendar does to a letting year inside the metro, where the same effect exists at smaller scale.
Which municipality rates each property?
Different ones, and this catches buyers comparing the two on a single spreadsheet. Stellenbosch falls under Stellenbosch Municipality in the Cape Winelands District, which maintains its own valuation roll, sets its own residential tariff, runs its own rebate structure including a pensioner scheme, and publishes its own objection window.
Cape Town suburbs answer to the City of Cape Town instead, on a 2026/27 tariff near 0.0064 in the rand and a rates-free slice granted where a home is valued at R8 million or under. No City figure applies to a Stellenbosch property and no Stellenbosch figure applies in the metro. A buyer should obtain the actual rates account for the specific erf rather than an estimate carried across, and should track the correct municipality’s valuation cycle, because missing an objection window means carrying an incorrect valuation for the life of a roll. The rates and taxes guide covers the metro method.
What does not change at the municipal boundary is the national layer, and it is worth separating the two before building a cost model. Transfer duty follows the same SARS table in both places, rising through 3%, 6%, 8%, 11% and 13% by price band, the conveyancing tariff is national, and a non-resident seller disposing above R2 million faces the section 35A withholding at 7.5%, 10% or 15% depending on whether the seller is a natural person, a company or a trust. So the acquisition and exit arithmetic a buyer builds for a metro purchase carries across the boundary unchanged. Only the recurring rates line has to be rebuilt from the correct roll, and that is the line most often copied across in error.
How different is the liquidity?
Substantially, and it is the risk most often left out of the comparison. Cape Town transacts continuously across many suburbs and price points, so a seller has recent comparables to price against, several agents competing for the mandate and a deep pool of buyers.
Stellenbosch is a small market. In any given segment the number of genuinely comparable annual sales is modest, which means two things at once: pricing is harder because the evidence is thin, and exit depends more on finding the particular buyer who wants that property than on general market conditions. Our reading is that this argues for a longer intended hold rather than against the town: a ten-year owner is unaffected by thin liquidity, and a three-year trader is exposed to it twice, once on entry and once on exit. For the neighbouring winelands market under a third municipality again, see the Paarl versus Stellenbosch page.
Where does Stellenbosch win?
On entry price against demand, in the right stock. Student-oriented apartments and small houses cost less per unit than metro equivalents while meeting demand that renews every academic year, which produces a yield ratio that compares well with much of Cape Town.
Three conditions make that work rather than merely look good on paper:
- Proximity to campus that a tenant will actually walk, which is a route question rather than a distance one.
- Stock that suits a household rather than a single tenant, because two incomes covering one rent is more robust than one.
- Marketing on the academic calendar, which means a unit available before the year opens rather than in the middle of it.
Miss any of the three and the yield advantage disappears into vacancy. The Stellenbosch guide covers the town’s stock in more detail.
Where does Cape Town win?
On depth, on information and on optionality. A metro market gives a foreign buyer comparable sales to price against, competing agents, published municipal documents to research, and a range of suburbs that lets the buyer choose between income, growth and lifestyle rather than accepting one blend.
It also gives an owner a second use. A Cape Town apartment that stops working as a student or professional let can be repositioned toward a different tenant type, a short let where the rules allow, or an owner-occupied home. A Stellenbosch student property has fewer alternative uses, because the demand that supports it is specific. The pros and cons are therefore about flexibility as much as about return: the metro costs more per unit of income and gives more ways out.
Which should you buy?
The decision follows from horizon and from how much local knowledge the buyer has, more than from the yield comparison.
| Priority | Better fit | Why |
|---|---|---|
| Liquidity and a straightforward exit | Cape Town | Continuous transactions, deep buyer pool |
| Yield per rand in student stock | Stellenbosch | Lower entry against renewing demand |
| Diversified demand, absorbed shocks | Cape Town | No single institution moves the market |
| A specific reason to be in the town | Stellenbosch | Local knowledge is worth more here |
| Researching from abroad | Cape Town | Published City documents, more comparables |
| A ten-year hold either way | Both work | Thin liquidity matters least over a decade |
Whichever side the decision lands on, the exit is the part to plan first, because it is where the two markets differ most and where a foreign owner has least room to react. The pillar investment guide sets out the entry side in full.
Sources: Stellenbosch Municipality rates policy and pensioner rebate scheme for the jurisdictional position; City of Cape Town budget 2026/27 adopted 29 June 2026 for the metro rates position. Demand-structure and liquidity observations describe the two markets generally and are directional rather than measured. Obtain the correct municipality’s rates account and valuation for the specific property before offering. Current as at 27 August 2026.
Frequently Asked Questions
Concentration. Cape Town spreads rental demand across a metro economy of offices, tourism, services and public institutions, so no single employer or institution moves the market. Stellenbosch concentrates a large share of its demand on one university and the businesses around it, which produces reliable student and staff tenancies and a market that reacts to decisions made by one institution rather than by an economy.
No. Stellenbosch falls under Stellenbosch Municipality in the Cape Winelands District, with its own valuation roll, rates tariff, rebate structure and objection calendar, while Cape Town suburbs fall under the City of Cape Town, which sets a rates-free portion of R620,000 on homes valued at R8 million or less for 2026/27 and a residential rate in the rand of about 0.0064. No City figure applies to a Stellenbosch property.
Cape Town, by a wide margin, because it transacts continuously across many suburbs and price points. Stellenbosch is a small market where the number of comparable annual sales in any given segment is modest, so a seller depends more on finding the specific buyer than on market conditions. That is not a defect, it is what a concentrated market looks like, and it argues for a longer intended hold.
In student-oriented stock, often yes, because entry prices sit below metro equivalents while demand renews every academic year. The catch is that the demand is seasonal and institutional: it concentrates before the academic year opens, thins sharply afterwards, and depends on enrolment and residence policy decisions the landlord has no visibility into.
Single-source demand. A change in enrolment, a new university residence coming online, or a shift in how the institution houses students moves a large share of the rental market at once, and none of it is visible to a landlord in advance. A Cape Town suburb absorbs the equivalent shock because no single employer or institution supplies most of its tenants.
Cape Town, in most cases, on liquidity and on information. A metro market has more comparable sales to price against, more agents competing, a deeper pool at resale and municipal rules a foreign buyer can research in English from published City documents. Stellenbosch rewards a buyer who knows the town, has a specific reason to be there and intends to hold for a decade.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.