
Stellenbosch Property Investment Guide 2026, Winelands
Stellenbosch property investment guide: winelands lifestyle, university demand, estate living, semigration, modelled yields, and foreign buyer rules for 2026.
By Cape Town Invest Editorial · Updated September 3, 2026 · 28 min read
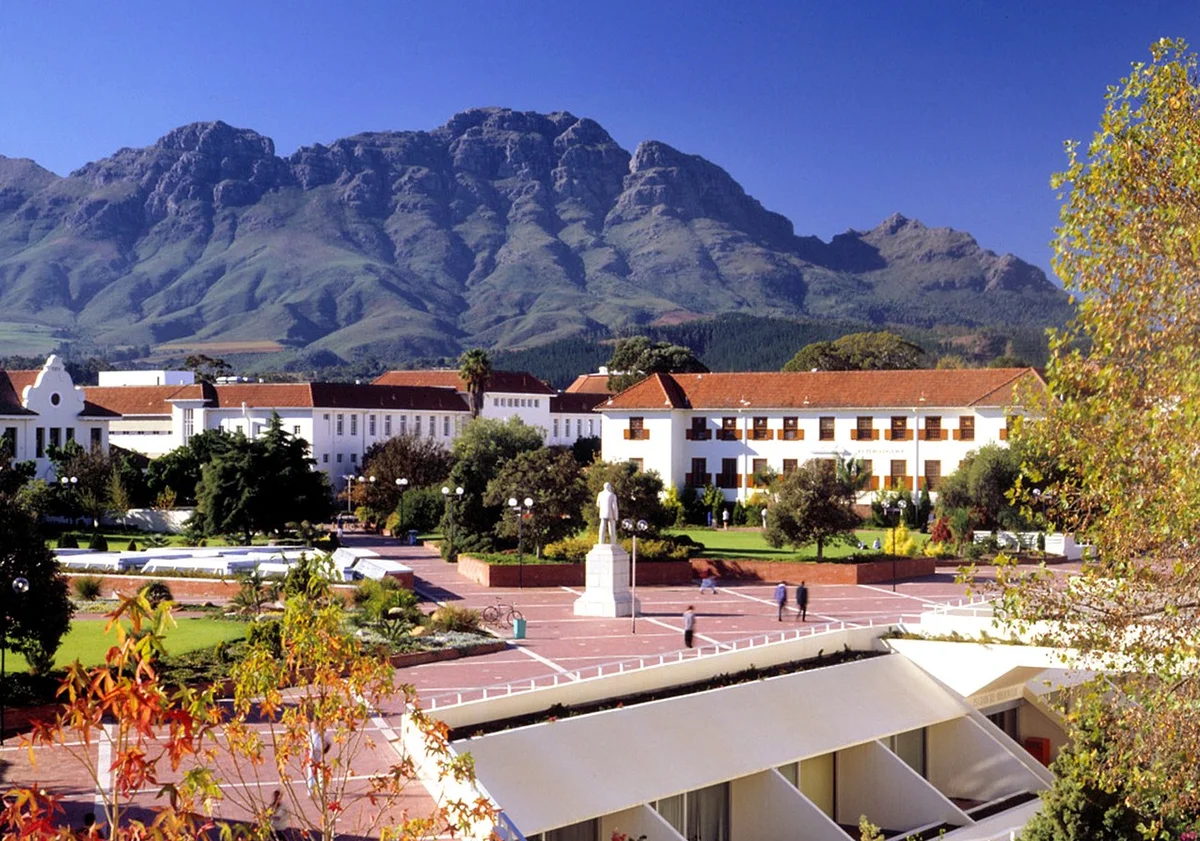
Quick answer: Stellenbosch is the anchor of the Cape Winelands for property investors who want lifestyle, semigration, and estate living over headline rental yield. Western Cape house prices rose 179.6% from 2010 to September 2025 versus 79.7% in Gauteng, and semigration keeps demand structural. Modelled gross yields in town stock run near 5% to 6%, below Sea Point’s 9.7%, so the case is long-hold growth and quality of life. Foreigners pay no buyer surcharge.
How should you underwrite Stellenbosch?
Read this guide as the Winelands companion to the broader the metro investment guide. The metro guide frames city-wide growth near 8.5%, the median near R1.9m, and income suburbs like Sea Point modeling 9.7% gross. Stellenbosch inverts part of that trade-off. You accept lower modelled yields and a smaller immediate tenant pool in exchange for estate security, school access, and a brand that sells itself internationally.
The macro case is semigration. Western Cape house prices rose 179.6% from 2010 to September 2025 while Gauteng rose 79.7%, and BetterBond-style commentary consistently ranks the Cape as the top semigration destination. Stellenbosch captures families who want winelands aesthetics with university and hospital employment nearby. That demand is structural, not seasonal, which supports resale even when gross rent looks modest.
What do the 2025 to 2026 numbers say about Stellenbosch?
| Metric | Figure | What it signals |
|---|---|---|
| WC house price growth 2010 to Sep 2025 | +179.6% | Long-hold tailwind for Western Cape |
| Gauteng same period | +79.7% | Semigration outperformance context |
| Cape Town annual price growth | ~8.5% to Jan 2025 | Metro liquidity benchmark |
| Cape Town median price | ~R1.9m | Entry comparison for town stock |
| Sea Point modelled 1-bed gross yield | ~9.7% | Yield benchmark Stellenbosch usually trails |
| Stellenbosch town stock modelled gross | ~5% to 6% | Income is secondary to lifestyle |
| Drive time to Cape Town CBD | ~45 to 60 min | Commute and remote-work reality |
| Foreign buyer surcharge | None | Same transfer duty scale as locals |
| Non-resident bond ceiling | ~50% | Plan offshore capital accordingly |
The table frames the investor question plainly. If your hurdle is net cash flow near 7%, Stellenbosch town stock will disappoint unless you buy at a sharp price. If your hurdle is a hard-currency lifestyle asset with Western Cape growth behind it, the town clears the bar for many semigration and foreign buyers.
Who buys Stellenbosch property and why does it anchor Winelands demand?
Three buyer types dominate Stellenbosch demand with distinct investment horizons and return expectations: semigration families leaving Gauteng or other inland provinces want schools, security, and outdoor space and often pay cash or use a partial bond holding for ten years or more making them price-resilient buyers during credit tightening; foreign lifestyle buyers from the UK, Germany, the Netherlands, and Scandinavia want a wine-country base without Portugal-style golden-visa complexity and benefit from South Africa offering no foreign buyer surcharge which keeps the entry ticket cleaner than many European markets; and university-linked professionals including academics, researchers, and hospital staff support rental demand in town creating a long-term tenant pool distinct from pure tourism that stabilises occupancy even when seasonal wine-route visitors thin out. The three profiles rarely compete for the same stock because semigrators bid for secure estates and large freehold, foreign second-home buyers target renovated cottages or managed estates with guaranteed rental programmes, and income-focused investors seek town apartments near the university where modelled 5 to 6 percent gross long-let yields marginally exceed estate houses that struggle to reach 4 percent gross.
Three buyer types dominate.
Semigration families leaving Gauteng or other inland provinces want schools, security, and outdoor space. They often pay cash or use a partial bond and hold for ten years or more.
Foreign lifestyle buyers from the UK, Germany, the Netherlands, and Scandinavia want a wine-country base without Portugal-style golden-visa complexity. South Africa offers no foreign buyer surcharge, which keeps the entry ticket cleaner than many European markets.
University-linked professionals support rental demand in town. Academics, researchers, and hospital staff create a long-term tenant pool distinct from pure tourism.
| Buyer profile | Typical stock | Primary return driver |
|---|---|---|
| Semigration family | Estate house or large freehold | Lifestyle, schools, space |
| Foreign second home | Estate or renovated cottage | Preservation, currency, prestige |
| Income-focused investor | Town apartment near university | modelled 5% to 6% gross long-let |
| Hybrid remote worker | Somerset West or Stellenbosch edge | Balance metro access and space |
Estate living versus town stock
Estates are the prestige format. Security, views, clubhouses, and architectural control attract buyers who want a managed environment. Yields are usually the lowest modelled segment because prices are high and tenants who can afford estate rents are a thin slice of the market.
Town apartments and cottages near the university and main street corridor offer the best income profile in Stellenbosch. They still rarely match Sea Point, but long-let demand is steadier than on a remote estate plot.
| Format | Pros | Cons |
|---|---|---|
| Secure estate house | Space, security, resale to semigration | Low modelled yield, levies and HOA rules |
| Town sectional title | Better tenant depth, lower entry | Body corporate rules, parking limits |
| Smallholdings and plots | Privacy, future build option | Infrastructure cost, weaker liquidity |
Insider tip: read estate conduct rules before you assume you can short-let or run a home office. Winelands estates often restrict both, which kills strategies that work in the City Bowl.
What rental yield and income reality does Stellenbosch property actually deliver?
Stellenbosch delivers modest income, and the honest planning number is lower than most brochures imply. Town stock near the university and the main street corridor models roughly 5% to 6% gross on a long let. Large estate houses, particularly at R8 million and above, often model under 4% gross, because achievable rent does not scale with land value, mountain views, or clubhouse access.
Net falls further below gross here for a reason specific to the Winelands. Estate levies can run 30 to 50 percent above municipal rates on large homes, covering security, internal roads, and landscaping that a town sectional title owner never pays for separately. Layer rates, insurance, management, and vacancy between leases on top, and an estate modelling under 4% gross can return very little in a year with one bad tenancy gap.
The tenant pool explains the split. Academics, researchers, and hospital staff sustain steady long-let demand for compact town stock. The market for a top-end estate rental is thin, and a vacancy there runs for months rather than weeks.
Underwrite the long lease first, using the method in our Cape Town rental yield guide, and treat wine-tourism short-letting as optional upside that estate conduct rules may prohibit outright. Against Sea Point’s 9.7% modelled gross, this is a growth and lifestyle allocation.
What satellite Winelands markets sit near Stellenbosch and how do they differ?
Somerset West on the Helderberg sits roughly 20 minutes from Cape Town International Airport versus Stellenbosch town at 45 to 60 minutes to the CBD, which shapes semigration bids on the same R3 million to R5 million budget segment. Transfer duty on a R4 million Winelands resale adds roughly R280,000 on current SARS bands before conveyancing near R45,000 to R55,000, which foreign buyers must fold into yield math alongside estate levies that can exceed municipal rates by 30 to 50 percent on large homes. Modelled gross yields on Helderberg town stock often run near 5 percent to 6 percent, slightly above remote Stellenbosch estates under 4 percent gross on R8 million plus houses. Non-residents face exchange-control cap near 50 percent local bond with balance through authorised dealer and non-resident endorsement on title for repatriation at exit.
How do foreign buyers finance and repatriate on Stellenbosch property?
Foreigners follow the same South African rules as Cape Town with no foreign buyer surcharge on transfer duty, exchange-control cap near 50 percent local bond for non-residents, FICA verification before transfer, and funds introduced through authorised dealer with non-resident endorsement on title for clean repatriation at exit. Stellenbosch adds no extra legal layer, only different liquidity at resale versus Sea Point apartments.
Foreigners follow the same South African rules as in Cape Town.
There is no foreign buyer surcharge on transfer duty. Non-residents typically face a roughly 50% local bond ceiling under exchange control, so plan offshore capital for the balance. FICA verification applies before transfer, and funds should enter through an authorised dealer with a non-resident endorsement on the title for clean repatriation later.
The practical path is documented in the buy Cape Town property as a foreigner hub, the exchange control guide, and the FICA requirements guide. Stellenbosch adds no extra legal layer, only a different liquidity profile at resale.
Off-plan and new stock in the Winelands
New sectional title and estate phases appear in Stellenbosch and Somerset West, especially near growth corridors. Off-plan purchases from VAT-registered developers carry 15% VAT inside the price instead of transfer duty, which changes the all-in cost stack.
Use the off-plan property Cape Town guide for OTP structure, NHBRC enrollment, deposit trust accounts, and snagging before registration. For active schemes and precincts in 2026, see the new developments hub. Statistics South Africa recorded building plans passed and buildings completed down almost 6% year on year in the fourth quarter of 2025, which constrains new supply and can support pricing on completed stock, but also raises execution risk on delayed schemes.
What belongs on your due diligence checklist?
| Check | Why it matters in the Winelands |
|---|---|
| Estate levy and HOA trend | Can exceed municipal rates on large homes |
| Short-let and business rules | Many schemes ban Airbnb-style letting |
| Water and borehole rights | Larger plots may depend on private supply |
| Commute test at peak hours | 45 min can become 75 min on the N2 |
| University rental seasonality | Academic calendar affects voids |
| Building plans on renovations | Estate design panels can block changes |
Run the same sectional title levy audit and title search described in the due diligence Cape Town guide. Winelands charm does not remove legal risk.
What are the pros and cons of Stellenbosch property investment?
| Advantages | Disadvantages |
|---|---|
| Premier Winelands brand and lifestyle | modelled yields below Cape Town income suburbs |
| Semigration and foreign lifestyle demand | Smaller tenant pool than the metro |
| Estate security attracts family capital | Estate rules can block your letting strategy |
| Western Cape long-hold growth context | Commute friction if you need daily CBD access |
| No foreign buyer surcharge | Rand volatility for hard-currency buyers |
| University supports long-term tenants | Liquidity slower than Sea Point apartments |
Who Stellenbosch suits, and who should look elsewhere
Stellenbosch fits semigration families, foreign lifestyle buyers, and long-hold investors who want Winelands exposure with university-town depth.
Look to Cape Town metro if you need modelled net yield above 6%, short-let scale, or fastest resale liquidity. Century City and Sea Point serve different income profiles.
Look to Somerset West if you want Helderberg schools and airport proximity with Winelands adjacency at a somewhat lower price per square metre.
What red flags should Stellenbosch buyers treat as stop signals?
Stop when the estate bans the letting strategy you modelled, when yield quotes use peak-week Airbnb only without long-let fallback, when special levies are pending on sectional title, when off-plan scheme lacks NHBRC enrolment, when purchase lacks non-resident endorsement with offshore funds, or when peak-hour commute to Cape Town is ignored for working households.
- An estate that bans the letting strategy you modelled.
- Yield quotes based on peak-week Airbnb only, with no long-let fallback.
- Special levies pending on a sectional title block.
- Off-plan scheme with no NHBRC enrollment or vague completion date.
- Purchase without non-resident endorsement when funding from abroad.
- Ignoring peak-hour commute time if the household still works in Cape Town.
How to build a Winelands position
A sensible sequence:
- Decide whether Stellenbosch is lifestyle, semigration, or modest income.
- Choose estate versus town stock accordingly.
- Model net yield with real levies, rates, vacancy at 8% to 10%, and management at 8% to 12%.
- Complete foreign-buyer paperwork and exchange control if applicable.
- Run full due diligence on estate rules and body corporate health.
- Hold for a long cycle aligned with Western Cape growth, not a quick flip.
Stellenbosch rewards patience and punishes yield fantasies. Used correctly it diversifies a Cape Town portfolio into the Winelands without pretending the town is another Sea Point.
Closing verification notes
Winelands buyers should match Lightstone deeds data with on-the-ground agent comps on the same road; spreads above 10% often mean stale asking prices, not a rising market.
Winelands buyers should match Lightstone deeds data with on-the-ground agent comps on the same road; spreads above 10% often mean stale asking prices, not a rising market.
When comparing Stellenbosch nodes, reconcile Winelands asking curves with recent sales in Paradyskloof and Die Boord. Transfer duty on a R4,000,000 home is R217,356, 5.43% of price. Non-resident buyers should model the commute to Cape Town International Airport and tenant depth from Stellenbosch University before they underwrite yield. Sectional title stock near town centre often carries higher levies than freehold plots in the Helderberg fringe. Always verify municipal water restrictions and borehole rights on larger plots before you offer.
Winelands buyers often underestimate insurance on vineyard-adjacent homes and security upgrades on larger plots. If you plan short-term letting, confirm municipal zoning and HOA rules in writing because Stellenbosch enforcement tightened after 2024 complaints. Compare Paarl and Franschhoek comps on the same ticket size before you anchor on a single Stellenbosch listing. Keep improvement invoices from day one for future capital gains calculations with SARS.
Foreign buyers should file exchange-control records cleanly when funding from abroad and keep three comparable sales printed for your conveyancer review. Model vacancy at four weeks on long-let Winelands stock even when university demand looks strong.
Confirm body corporate rules on short-term letting before you assume Airbnb income on Winelands apartments. Estate purchases need a full HOA reserve review; town apartments need levy history and conduct rules in writing before deposit.
Pair this guide with the Somerset West area page if you want winelands access with a shorter airport commute, and rerun net yield after security, garden, and insurance costs that estate agents often omit from headline prices. University letting demand helps town stock, but winter vacancy still needs a conservative allowance in your model. Compare your shortlisted erf against Paarl and Franschhoek stock at the same ticket size before you treat Stellenbosch as the only Winelands option. Keep improvement invoices from day one for SARS on exit, and verify borehole rights on larger plots.
Insider tip: in Stellenbosch the student rental market and the family market run on different calendars, and mixing them up wrecks a yield model. Cape Town Invest models town stock near 5% to 6% gross, well under Sea Point’s 9.7%, and the student segment only reaches the top of that band when the unit is walkable to campus and let by the room rather than by the unit. Family homes in the estates let annually to a much smaller pool at lower gross but with far less turnover and damage. Decide which business you are in before you offer, because the two need different stock, different management and different vacancy assumptions. The town sits roughly 45 to 60 minutes from Cape Town, so weekday commuter demand is real but limited, and foreigners pay no surcharge on either type.
Sources:National supply trend from Stats SA release P5041.1, buildings reported by local government, Q4 2025. Current as at 7 September 2026.
Frequently Asked Questions
Stellenbosch suits lifestyle and semigration buyers more than pure yield hunters. The town combines a top university, wine-country prestige, and estate living within commuting distance of Cape Town. Western Cape house prices rose 179.6% from 2010 to September 2025 versus 79.7% in Gauteng, and semigration keeps demand structural. Modelled gross yields are lower than Sea Point's 9.7%, so the return is mainly capital preservation, lifestyle, and long-hold growth.
Stellenbosch and the broader Winelands model lower gross yields than Cape Town's income suburbs. Compact town stock may reach roughly 5% to 6% gross on a modelled basis, while large estates often model under 4% gross because purchase prices are high relative to achievable rent. Net yields fall further after levies, rates, security, and vacancy. Investors should treat Winelands property as a lifestyle and growth allocation, not a cash-flow engine like Sea Point.
Yes. Foreigners can buy freehold homes and sectional title units in Stellenbosch with no foreign buyer surcharge, the same as anywhere in South Africa. Non-residents typically face a roughly 50% local bond ceiling and must introduce offshore funds through an authorised dealer bank. The title deed should be endorsed non-resident when purchase capital comes from abroad, which protects repatriation at exit.
Stellenbosch sits roughly 45 to 60 minutes from central Cape Town by car in normal traffic, depending on the route and time of day. The N2 and R44 corridors connect the town to the Cape Town metro, which is why many semigration families live in the Winelands while working remotely or commuting part-time. Somerset West on the Helderberg flank is closer to the airport and often suits buyers who want winelands access with shorter metro links.
Estates suit family buyers who want security, views, and space, and they dominate foreign and semigration demand at the top end. Town apartments and smaller homes near the university suit rental demand from academics, students, and young professionals, with somewhat better modelled yields than estate houses. Match the format to your goal: estates for lifestyle and preservation, compact town stock if income matters more.
Cape Town metro offers higher modelled rental yields, deeper tenant pools, and faster resale liquidity, with city-wide annual price growth near 8.5% and a median near R1.9m. Stellenbosch trades lifestyle, space, and wine-country prestige for lower yields and a smaller buyer pool. Many investors hold both: Cape Town for income and liquidity, Stellenbosch for lifestyle, semigration, or a long-hold Winelands allocation. See our Cape Town vs Stellenbosch comparison for a side-by-side table.
Somerset West on the Helderberg offers family-value semigration stock with better metro links. Paarl and Franschhoek attract estate and lifestyle buyers at various price points. Hermanus on the coast draws holiday-home and retirement demand. Industry commentary also points to secondary towns like Langebaan and George gaining semigration interest. Each satellite has a different yield-versus-lifestyle balance, so underwrite the specific town rather than the Winelands label alone.
Wine tourism supports short-term demand in peak seasons, but regulation, body corporate rules, and seasonality are sharper constraints than in Sea Point or the City Bowl. Many estates and sectional title schemes restrict or ban short-letting. Underwrite a long-term lease first at modelled gross near 5% to 6% on town stock, and treat tourism income as optional upside. Read the short-term rental rules guide before you assume Airbnb-style returns.
Verify estate levy trends, security costs, water rights on larger plots, and any building lines or estate architectural rules before you offer. For sectional title in town, audit body corporate reserves and special-levy history exactly as you would in Cape Town. Confirm approved building plans on any renovation intent, and read estate conduct rules on short-lets, pets, and sub-letting. Estate living trades flexibility for security, so the rules bind you after transfer.
We publish independent guides on Winelands strategy, foreign buyer eligibility, costs, yield math, off-plan purchases, and due diligence without developer commissions on editorial content. Use this hub together with the Somerset West area guide and the Cape Town vs Stellenbosch comparison to choose a town and format, then request a shortlist matched to your budget and hold period.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.