
Century City Investment 2026, 7.7% Yield, Corporate Rent
Century City apartments: 7.7% modelled gross, Rabie precinct, corporate tenants. Foreign buyers, 50% bond, no surcharge. 2026 guide.
By Cape Town Invest Editorial · Updated August 21, 2026 · 24 min read
Quick answer: Century City is Cape Town’s largest master-planned mixed-use precinct, developed by Rabie Property Group around Canal Walk in the Milnerton area, roughly 10km north of the CBD. For investors it is an income and convenience play built on sectional title apartments, deep corporate rental demand, and professional management. Yields are modelled at around 7.7% gross at the top of the rent range, with net landing near 4.2% after levies, rates, management and vacancy. Foreigners can buy freely, with no surcharge, and non-residents can typically fund up to 50% with a local bond.
What numbers define Century City in 2026?
Before evaluating a single unit, anchor yourself in the precinct’s character. The table below frames Century City against an investor lens. Pricing and yield figures are indicative and modelled, and should be verified against live listings for your specific block.
| Metric | Indicative figure | What it signals |
|---|---|---|
| Distance to Cape Town CBD | About 10km, 15 to 25 minutes | Commuter-friendly, not coastal premium |
| Developer | Rabie Property Group | Master-planned, consistent quality |
| Dominant ownership type | Sectional title apartments | Levy-based, body corporate managed |
| Modelled gross yield | About 7.7% | Income-led, strong for the quality |
| Modelled net yield | Mid 5% to low 6% | After levies, rates, management, vacancy |
| Core tenant base | Corporate and professional | Low vacancy, long-let depth |
| Retail anchor | Canal Walk Shopping Centre | Footfall, amenity, resale appeal |
| Connectivity | N1, MyCiTi bus, fibre, airport access | Practical daily convenience |
| Foreign buyer surcharge | None | Versus UK 2% and Singapore 60% |
| Non-resident bond ceiling | Up to 50% loan-to-value | Local leverage available |
The 7.7% modelled gross yield is the figure investors quote first, but the more important story sits in the tenant and connectivity rows. A precinct that combines a large employment base with fast transport links to the rest of the metro tends to keep vacancy low, and low vacancy is what converts a strong gross number into a dependable net return. Century City was built to generate exactly that demand, which is why it behaves more like an income asset than a speculative one.
Why Century City suits the corporate rental model
Century City suits the corporate rental model because it is a working precinct, not a dormitory suburb: an office and business park, Canal Walk, hotels, schools, and medical facilities sit inside its boundary, linked by Century City Connect fibre and the MyCiTi bus network. That employment base is what holds the 7.7% modelled gross yield together.
Corporate rental demand has three qualities that investors should value:
- Sticky. Company-linked tenants and professionals on multi-year postings sign longer leases and renew, which lowers turnover costs and void periods.
- Creditworthy. Salaried professional tenants and corporate lets carry lower arrears risk than transient short-let guests, which protects the vacancy allowance in your net-yield model.
- Predictable. Demand tracks the precinct’s employment base rather than the tourism season, so income does not swing the way coastal short-let income can.
For a deeper view of how tenant profile drives returns across the city, read our Cape Town rental yield guide.
This is also why Century City is a sensible first Cape Town purchase for many foreign investors. A long-let or corporate-let strategy is easier to manage remotely than a high-touch short-let operation, the income is steadier, and the regulatory exposure is lower. You can still consider short-letting select units, but in Century City the base case is a long-let to a professional tenant, with short-let treated as optional upside rather than the core thesis.
Sectional title: what investors must understand
Sectional title in Century City means you own your unit, the section, plus an undivided share of the common property, and you pay a monthly levy to the body corporate that maintains it. That levy is the single largest deduction between the 7.7% modelled gross yield and the roughly 4.2% net most units land in.
Common property covers corridors, lifts, parking, gardens, and security infrastructure. Sectional title is investor-friendly because it removes most of the direct maintenance burden, which suits an owner managing from abroad, but it also ties your net yield to the financial health of one body corporate.
The body corporate handles building insurance, common-area upkeep, and shared security. A scheme with a thin reserve fund or a history of special levies can quietly erode returns, because special levies are unbudgeted charges raised when reserves cannot cover major repairs. Four documents settle the question before you commit:
- Monthly levy and how it has moved over the last 24 months
- Reserve fund balance measured against the scheme’s maintenance plan
- Special-levy history, and what triggered each one
- What the levy actually covers: insurance, security, common-area upkeep
Confirm what the levy covers and how it has trended, because rising levies compress yield over time. Our due diligence guidance covers how to read these documents, and the body corporate review should sit at the centre of any Century City purchase. A well-run scheme with healthy reserves protects both your income and your resale value.
Modeling the 7.7% gross yield to a net figure
The 7.7% gross yield is the headline, but no investor should buy on gross. Gross yield is annual rent divided by purchase price; net yield is what remains after the real costs of ownership. The table below illustrates how a modelled 7.7% gross compresses to a net figure on a representative Century City sectional title apartment. Treat the inputs as directional placeholders to be replaced with live numbers for your specific unit.
| Line item | modelled assumption | Effect on yield |
|---|---|---|
| Gross yield | About 7.7% | Starting point |
| Body corporate levy | Recurring monthly charge | Reduces net materially |
| Municipal rates | Annual property rates | Reduces net |
| Rental agent fee | Around 8% to 10% of rent | Reduces net |
| Vacancy allowance | Allow for void periods | Reduces net |
| Maintenance and repairs | Annual reserve for the unit interior | Reduces net |
| Modelled net yield | Mid 5% to low 6% | What you actually keep |
The spread between gross and net in Century City is narrower than on the Atlantic Seaboard, where high entry prices relative to rent push net yields toward the low single digits. In Century City the entry price is more modest and the rental demand is deep, so a 7.7% gross holds a net near 4.2%, which is a modest but genuinely reliable income return for a managed, low-vacancy precinct. Compare that profile against the city’s strongest income suburbs in our guide to the highest rental yield suburbs in Cape Town before you decide where to deploy capital.
Two levers move your net the most: the levy and the vacancy rate. A unit in a well-reserved body corporate with a reasonable levy, let to a stable corporate or professional tenant, will sit at the top of the net range. A unit in a scheme with rising levies or one that you fail to keep occupied will drift to the bottom. This is why the body corporate review and the tenant strategy matter more than chasing the absolute lowest purchase price.
Rabie property group, the developer behind the precinct
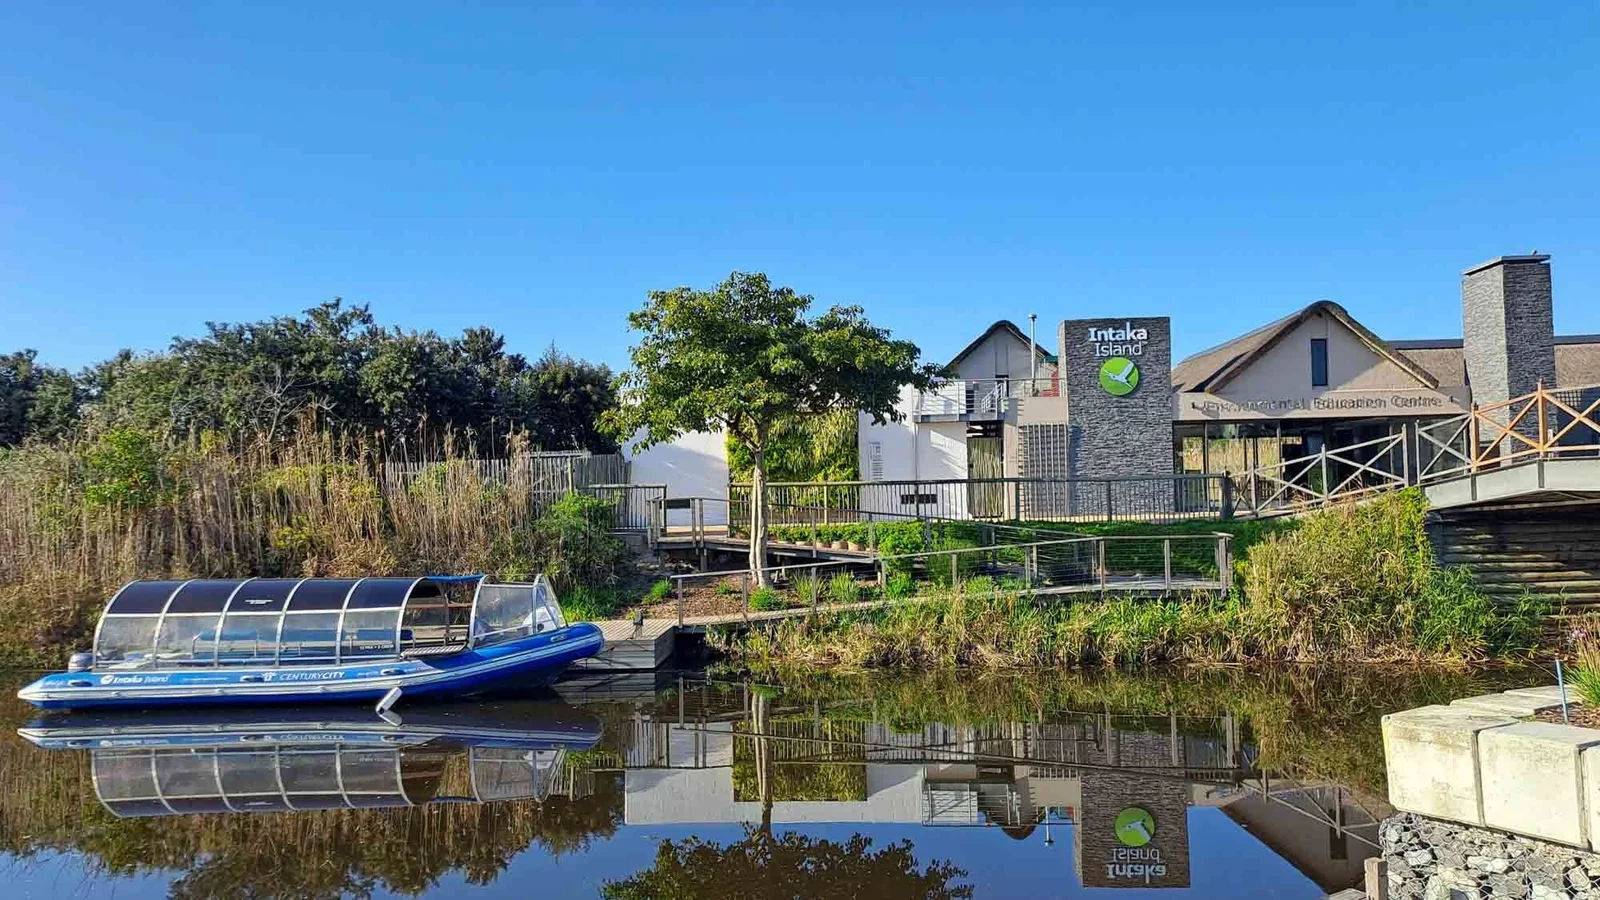
Rabie Property Group is the Cape Town developer that master-planned Century City and has shaped the precinct since the late 1990s, building the mixed-use template of apartments, offices, retail anchored by Canal Walk, and the Intaka Island wetland that underpins the 7.7% modelled gross yield. Precinct management now runs through the Century City Property Owners’ Association.
- Master plan. A mixed-use precinct combining apartments, offices, retail, hotels, schools, and medical facilities inside one boundary.
- Retail anchor. Canal Walk Shopping Centre, which generates part of the rent roll through its retail and hospitality staff.
- Green infrastructure. The Intaka Island wetland, which separates the precinct from a generic apartment cluster.
- Ongoing management. The Century City Property Owners’ Association at precinct level, with each block run by its own body corporate.
Developer pedigree explains the precinct; it does not set your return. Levies differ enough between blocks to move net yield by a full percentage point around that 4.2% midpoint, so read the body corporate financials of the specific scheme rather than the developer’s track record. Our Rabie Property Developers profile covers the wider portfolio.
Who rents in Century City?
Underwriting rent in Century City means knowing exactly who signs the lease, because the 7.7% modelled gross yield rests on tenant depth rather than on a scarce address. The on-site office park, Canal Walk and the precinct hotels generate their own tenant pipeline, so demand is created inside Century City rather than imported from the rest of the metro. Five groups dominate the rent roll:
- Corporate tenants and company-linked lets from the on-site offices and business park, often on longer leases
- Relocating professionals and skilled staff who want quality accommodation near their workplace
- Young professionals and couples who value walkability, security, and amenity over a coastal address
- Semigration families and remote workers drawn to the managed, low-friction environment
- Retail and hospitality staff working at Canal Walk and the precinct’s hotels and restaurants
This mix is deliberately broad, which is itself a strength. A precinct that depends on a single tenant type is fragile; Century City spreads demand across corporate, professional, and lifestyle renters, which cushions vacancy if any one segment softens. The common thread is that these tenants want convenience, security, and proximity to work, exactly what the precinct is engineered to deliver, and they are willing to pay a steady rent for it.
For positioning your unit, match the apartment to the dominant tenant. One and two-bedroom units let most readily to professionals and couples and tend to model the strongest yield. Furnished, well-presented units aimed at corporate lets can command a premium and lower vacancy, provided you price against live comparables rather than aspiration.
Foreign buyers: eligibility, the 50% bond, and costs
Foreign buyers face no surcharge in Century City: South Africa places very few restrictions on non-resident ownership, and no additional acquisition tax applies. The binding constraint is finance. A non-resident who introduces funds cleanly can usually borrow up to 50% of the purchase price locally, with the other 50% funded from offshore capital.
That contrasts with the UK, with its non-resident stamp-duty surcharge, or Singapore and its additional buyer’s stamp duty. Our guide on buying Cape Town property as a foreigner walks through the eligibility rules in full. Budget four cost lines beyond the price:
- Transfer duty on the SARS sliding scale, 0% below R1,210,000 and stepping to 13% at the top
- Conveyancing fees, payable to the transferring attorney
- Bond registration costs, if you take the 50% local loan
- Levies and municipal rates from the transfer date onward
The financing rule that most affects foreign buyers is the loan-to-value ceiling. A non-resident who introduces funds into South Africa cleanly can usually borrow up to 50% of the purchase price from a South African bank, with the remaining 50% funded from offshore capital. South African residents and some foreigners with local income may qualify for higher leverage. The practical consequence is that a foreign buyer should plan for a 50% cash component, and should record the offshore funds correctly so that the capital and any future gains can be repatriated under South Africa’s exchange control framework. For the lending mechanics, read our non-resident mortgage guide for Cape Town.
Budget for the full cost stack, not just the price. Transfer duty applies on a sliding scale, with conveyancing fees, bond registration costs if you finance, and ongoing levies and rates layered on top. Modeling these correctly is what separates a realistic net yield from an optimistic one. Get the transfer duty and total acquisition costs confirmed in writing by a conveyancer before you make an offer, and remember that no foreign surcharge applies, which keeps the entry cost competitive against comparable global cities.
Century City versus other Cape Town investment zones
Choosing Century City is really a choice about what kind of return you want. The table below positions it against the city’s other main investment characters, using modelled yield bands and broad positioning rather than precise figures.
| Zone | Character | Best buyer fit | Yield vs growth (modelled) |
|---|---|---|---|
| Century City | Master-planned income precinct | Income-led, first Cape Town buy | Yield led, about 7.7% gross |
| Atlantic Seaboard | Prestige coastal strip | Capital preservation, trophy | Growth led, lower net |
| City Bowl | Urban, mixed demand | Balanced urban investor | Balanced |
| Sea Point | High-density coastal | Yield within the prestige strip | Yield led within prime |
| Outer suburbs | Value and yield | Budget-conscious income buyer | Yield led, variable |
The honest summary is that Century City and the Atlantic Seaboard are near-opposites. The coast offers scarcity, brand recognition, and resale liquidity at the cost of compressed net yield, often near 4.4% net in Camps Bay. Century City offers a designed-for-demand income profile, modeling around 7.7% gross, at the cost of the capital-growth ceiling that a beachfront address can reach. Neither is better in the abstract; the right choice depends on whether your priority is cash flow or long-run appreciation. Many investors hold both, using Century City as the income anchor and a coastal unit as the growth and lifestyle component.
What risks should you plan for with Century City Investment?
Century City’s risk set is structural rather than locational: body corporate finances, new supply in a master-planned precinct, and the yield-before-growth trade-off. Levy creep alone can move net yield by a full percentage point around that 4.2% midpoint, which is why the scheme review matters more than shaving the purchase price. Address each risk before you commit:
- Body corporate risk: a weak or under-reserved body corporate can impose special levies that erode net yield. Mitigate by reviewing financials, reserves, and special-levy history in full before buying.
- Supply risk: a master-planned precinct can add new apartment stock, which can pressure rents in oversupplied phases. Mitigate by checking the pipeline and underwriting on conservative rent.
- Yield-not-growth risk: Century City is built for income, so do not assume coastal-style capital growth. Mitigate by modeling returns on net yield, not speculative appreciation.
- Levy creep: rising levies compress net over time. Mitigate by checking the levy trend, not just the current figure.
- Vacancy risk: even strong precincts have voids between tenants. Mitigate with a realistic vacancy allowance and a clear corporate or professional letting strategy.
- Currency and repatriation risk for foreigners: mitigate by recording offshore capital correctly so funds and gains can be repatriated under exchange control.
The recurring theme is that Century City’s risks are manageable with documentation discipline. The precinct’s quality and demand are real; what undoes a deal is usually a skipped body corporate review, an over-optimistic rent assumption, or a misunderstanding of the 50% bond ceiling, not the precinct itself.
What belongs on your century city buyer’s checklist?
A Century City buyer’s checklist is short but non-negotiable: the body corporate financials, the levy trend, live rent comparables, and a net yield rebuilt from the 7.7% modelled gross down to the roughly 4.2% that survives management and vacancy. Foreign buyers add the 50% bond ceiling and an offshore funding record.
- Body corporate financials, reserve fund, and special-levy history reviewed in full
- Monthly levy confirmed and its trend over recent years checked
- Rent underwritten against live comparables for the same block and unit type
- Net yield rebuilt from the 7.7% modelled gross after levies, rates, management, and vacancy
- Tenant strategy defined as corporate or professional long-let, with short-let as optional upside
- Foreign funding mix planned around the 50% bond ceiling, offshore capital recorded for repatriation
- Transfer duty and total acquisition costs confirmed in writing, no foreign surcharge applies
- Developer pedigree and build quality verified, common areas inspected
- Connectivity and amenity confirmed for your target tenant, transport, fibre, retail, security
- Related guides read for city context, yield math, foreigner rules, and financing
What to verify next
Pull live listings and recently transacted prices for your shortlisted Century City block, then rebuild the yield on net, not gross, starting from the 7.7% modelled gross and deducting levy, rates, management, and a realistic vacancy allowance. Obtain the body corporate financials and read the reserve fund and special-levy history before anything else, because in a sectional title precinct that document decides your real return. Confirm your financing structure around the 50% non-resident bond ceiling and plan the offshore portion for clean repatriation. Read Buying Cape Town Property as a Foreigner and the Cape Town Rental Yield Guide before you make an offer. If the net numbers fail your hurdle rate after honest modeling, choose a stronger block or a different Cape Town income suburb rather than forcing the deal, because unit and scheme selection, not market timing, is where Century City is won.
Insider tip: in Century City the building matters more than the precinct, because levies vary enough to move your net by a full percentage point. Cape Town Invest models the precinct at about 7.7% gross with net landing near 4.2% once levies, rates, management and vacancy are all stripped out, and the spread inside that range is almost entirely a function of which scheme you buy into. Older blocks with thin reserve funds special-levy for lifts and waterproofing; newer schemes charge more monthly but surprise you less. Ask for the levy schedule and two years of financials on every shortlisted building, then compare those side by side rather than comparing asking prices. Corporate tenant demand from the office and retail core keeps vacancy low, so the risk here is cost creep, not an empty unit.
Frequently Asked Questions
Century City suits income-focused investors who want a managed, master-planned precinct rather than a coastal trophy address. Sectional title apartments model around 7.7% gross yield, supported by deep corporate and professional rental demand from the on-site business park, Canal Walk, and surrounding offices. Returns arrive mainly as steady rent and low vacancy rather than the high capital growth of the Atlantic Seaboard. Yield figures are modelled and directional.
Century City models around 7.7% gross yield on one and two-bedroom sectional title apartments, which is strong for a well-managed Cape Town precinct. Net yield lands materially lower once levies, rates, the rental agent fee, and a vacancy and maintenance allowance are deducted, typically modelling near 4.2%. The exact figure depends on entry price, levy size, and how you let the unit. All yields are modelled.
Century City was master-planned and largely developed by Rabie Property Group, the Cape Town developer that has shaped the precinct since the late 1990s. Rabie set the mixed-use template that combines residential apartments, offices, retail anchored by Canal Walk, and green infrastructure such as the Intaka Island wetland. Ongoing precinct management runs through the Century City Property Owners' Association.
Yes. Foreigners can buy sectional title apartments and freehold property in Century City with very few restrictions and no foreign buyer surcharge, unlike the UK or Singapore. Non-residents who bring funds into South Africa cleanly can usually finance up to 50% of the purchase price with a local bank bond and fund the rest with offshore capital, which should be recorded for future repatriation.
Non-resident foreign buyers can usually borrow up to 50% of the purchase price from a South African bank, with the remaining 50% funded from offshore capital introduced into the country. South African residents and some foreigners with local income may access higher loan-to-value ratios. Record the offshore portion correctly so the capital and future gains can be repatriated under exchange control.
Century City is a working precinct, not just a residential suburb. It hosts a large office and business park, retail at Canal Walk, hotels, and connectivity through Century City Connect fibre and the MyCiTi bus route, with fast access to the N1, the CBD, and Cape Town International Airport. That concentration of employers and relocating professionals creates steady corporate and long-term tenant demand, which supports low vacancy and reliable rent.
Most Century City apartments are sectional title, meaning you own your unit plus an undivided share of the common property, and you pay a monthly levy to the body corporate for shared upkeep, security, and reserves. Sectional title simplifies maintenance but makes the body corporate's financial health critical. Review the levy, the reserve fund, and any special-levy history before buying, because weak bodies corporate erode net yield.
They serve different goals. Century City is an income and convenience play, modeling around 7.7% gross yield with strong corporate rental demand and lower entry prices. The Atlantic Seaboard is a prestige and capital-growth play with lower net yields, often near 4.4% in Camps Bay. Income-led investors and first-time Cape Town buyers often favour Century City, while trophy and growth buyers favour the coast.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.