
Val de Vie: The Estate Is the Asset, Not the House
About R13,540 a month before bond service buys membership of a place. Whether that is expensive depends entirely on whether you are the one living there.
By Cape Town Invest Editorial · Updated August 27, 2026 · 11 min read
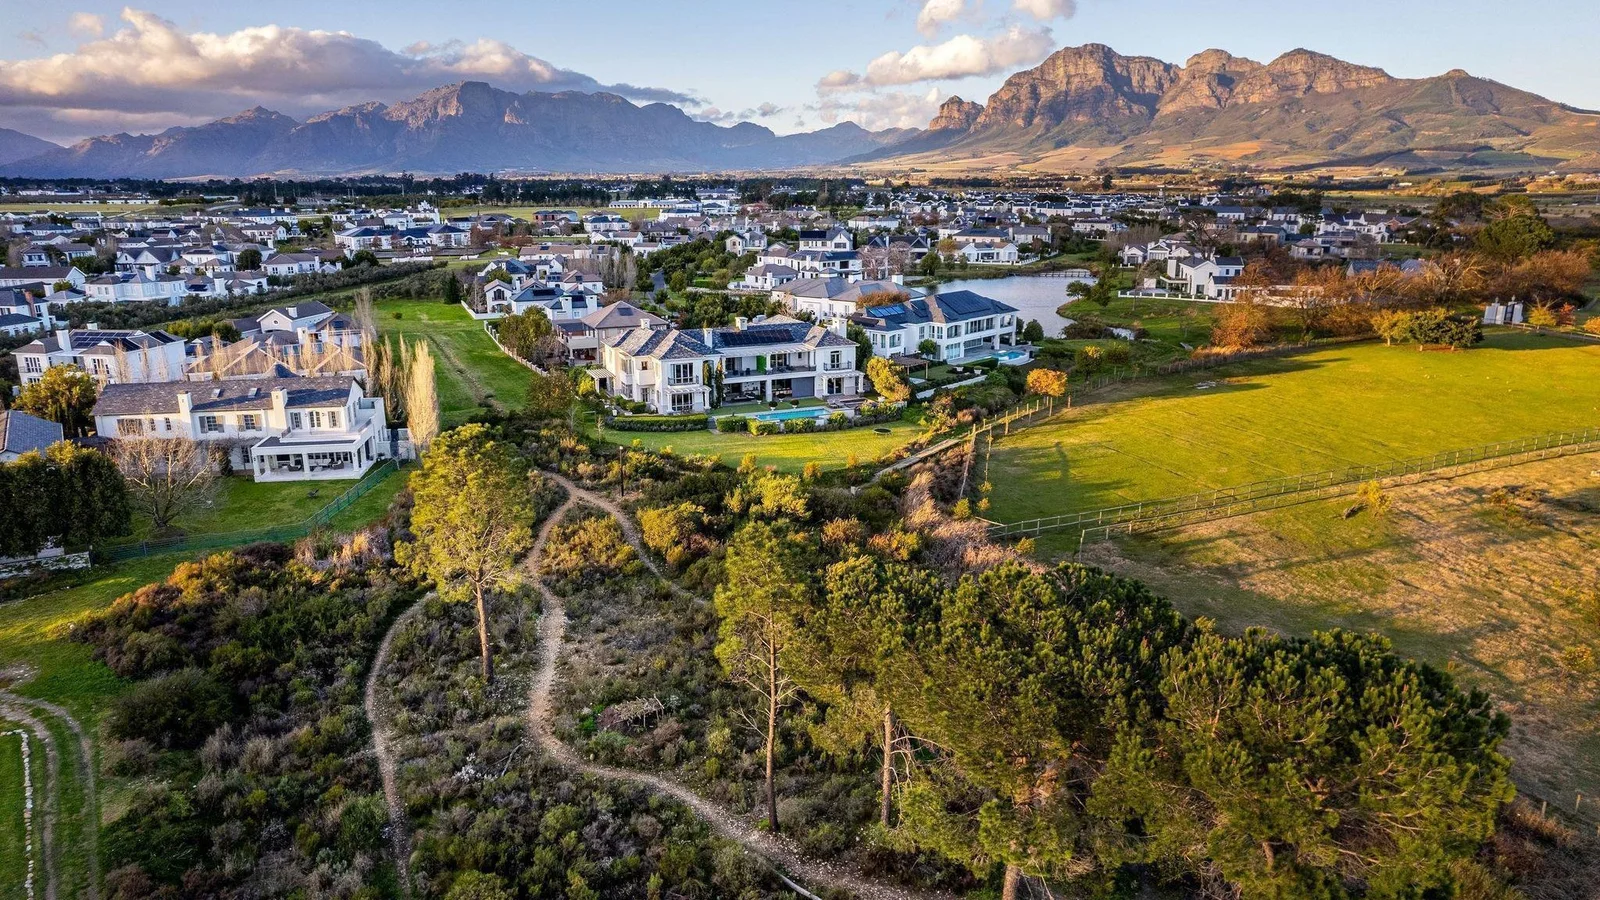
Quick answer: at Val de Vie the estate is the asset and the house is how you hold membership of it. Combined body corporate and estate charges on three-bedroom Vivante stock run near R11,710 a month, with Drakenstein rates around R2,750 on top, so an owner carries roughly R13,540 a month before bond service. Calling that a cost is only half right: it funds the security, the grounds and the facilities that are the reason to be there. Whether it is money well spent depends entirely on whether you are the one enjoying them.
What is actually being bought?
Access to a place, held in the form of a house.
That sounds like a distinction without a difference and it is not. On an ordinary suburban purchase, the property is the asset and the surroundings are context you did not pay for directly. On an estate like this one, a large share of what you are paying for sits outside your own boundary, the security infrastructure, the grounds, the sporting facilities, the river frontage, the maintained roads, and you pay for it every month, explicitly, for as long as you own.
So the honest way to read the monthly charge is not as a deduction from a return. It is the price of the thing that made you look in the first place. The regime that produces this arrangement, and how it differs from sectional title on the coast, is set out in the Atlantic Seaboard and Winelands comparison rather than repeated here.
What does it cost, precisely?
| Line | Three-bedroom Vivante stock, monthly |
|---|---|
| Combined body corporate and estate association charges | about R11,710 |
| Drakenstein municipal rates | about R2,750 |
| Total before any bond service | about R13,540 |
Those figures are observed on Vivante stock rather than a published tariff, and they should be confirmed for the specific unit, because charge structures differ between the estate’s product lines.
Two things are worth noticing about that table. It is a large number in absolute terms, comfortably more than the entire holding cost of a mid-market Cape Town apartment. And it is a known number, billed monthly, which is more than can be said for a freehold house where the equivalent spending on security, grounds and maintenance is real, irregular and mostly unbudgeted.
The test that decides whether it is expensive
One question, and it is about you rather than about the property: are you going to be there?
If you live there, you are buying a lifestyle at a stated monthly price. R13,540 a month for security you do not have to arrange, grounds you do not maintain and facilities you actually use is a proposition you can evaluate the way you would evaluate any other spending. Plenty of people conclude it is worth it, and they are not making an error.
If you let it and rarely visit, the same R13,540 a month is being spent so that a tenant can enjoy an estate you are not using. The rent covers it and not much else.
Put numbers on the second case. Optimistic long-let quotes on three-bedroom stock sit near R28,000 a month, which looks respectable against a R5,900,000 ticket until the carry comes out of it. What remains models roughly 3% net, a figure that is not wrong so much as it is a different kind of investment from the one most buyers think they are making. The specific scheme is covered on the Green Village page.
The pros and cons therefore turn on presence rather than on price:
- For a resident owner: a maintained, secure environment at a known monthly cost, facilities that are genuinely used, and a place that is what it advertises.
- For an absent owner: roughly 3% modelled net, a charge that runs whether or not the property is let, and a return that arrives as capital rather than income.
- For either: a smaller resale pool than a metro property, because the buyer has to want this estate specifically.
Vivante or Pearl Valley?
Two dwelling types holding the same membership, with different charge structures behind them.
Vivante is the apartment and retirement-oriented side. It carries a body corporate for the building on top of the estate association, so an owner there is funding two layers rather than one, which is where the R11,710 combined figure comes from.
Pearl Valley is the golf-oriented freehold side, where the house is yours entire and the association funds the estate around it.
A buyer choosing between them is not choosing between two estates or two levels of quality. They are choosing a dwelling type, a maintenance responsibility and a charge structure. What a body corporate levy has to fund, as distinct from what an estate association funds, is set out in the levies guide. The right question is not which is better but which arrangement you want to be inside for a decade, since the answer determines both what you maintain and what you are billed.
Which municipality, and why it matters
Drakenstein, not the City of Cape Town, and this catches buyers arriving from the metro.
Drakenstein Municipality maintains its own valuation roll, sets its own residential tariff, runs its own rebate structure and publishes its own objection window, and its 2026/27 budget proposed a cap on residential rate increases. None of the City of Cape Town’s figures apply here, not the rate in the rand, not the rates-free threshold, not the objection calendar.
Two consequences follow. A holding-cost model built on metro numbers will misprice the annual line. And the window in which a valuation can be challenged belongs to Drakenstein, so an owner tracking the wrong municipality’s calendar carries an incorrect valuation for the life of a roll. The surrounding Paarl market, under the same municipality, is covered on the Paarl page.
What about the exit?
Narrower and more committed, which is the same fact from two sides.
An estate home sells to somebody who wants that estate. That makes pricing harder, because the comparable evidence is thin, and it makes the pool smaller than a metro apartment’s. It also means the buyer is rarely comparing on yield: they are choosing a life, and a person choosing a life is a less price-sensitive counterparty than an investor running a spreadsheet.
The practical reading is about intended hold rather than about quality. A ten-year owner is barely affected by thin liquidity. A three-year holder is exposed to it twice, at entry and at exit, and should be honest about whether the estate is a home they want or an asset they are testing. The neighbouring Winelands market, where the same dynamics run under a different municipality again, is on the Franschhoek page.
What to establish before you offer
| Question | Get it in writing from | Why it matters here |
|---|---|---|
| Both charges, separately | The seller and the managing agent | Vivante carries two layers; the total is the real number |
| Three years of charge history | The body corporate and the association | It tells you the direction, not just the level |
| The Drakenstein rates account for the erf | The seller | No metro figure applies |
| Achievable rent from two live listings | A local letting agent | Brochure quotes and let quotes differ here |
| Whether you will actually be there | Yourself | It is the whole of the verdict |
The last row is not filler. Every other number on this page reads differently depending on the answer, and it is the one question a spreadsheet cannot settle for you.
Sources: Drakenstein Municipality 2026/27 budget proposals for the rating position, as reported by Paarl Post; Sectional Titles Schemes Management Act 8 of 2011 for the body corporate layer on Vivante stock, with the estate association constituted by its own founding documents rather than by that Act. Charge and rent figures are observed on Vivante three-bedroom stock rather than published tariffs or quoted rents, and the modelled net is built from them rather than from audited accounts. Confirm both charges and the rates account for the specific property. Current as at 27 August 2026.
Frequently Asked Questions
Because the carry is what you are buying. Combined body corporate and estate association charges on three-bedroom Vivante stock run near R11,710 a month, with Drakenstein municipal rates around R2,750 on top, so an owner is holding roughly R13,540 a month before any bond service. That money funds the security, the grounds, the sporting facilities and the river frontage that make the estate what it is.
That depends on who is standing in the house. An owner who lives there and uses the estate is buying a lifestyle at a stated monthly price, which is a fair exchange they can judge for themselves. An owner who lets it and rarely visits is paying that same amount for a tenant's lifestyle, and collecting a modelled net near 3% for the trouble. Same property, opposite verdicts.
Around 3% on a R5,900,000 three-bedroom, and it is worth arriving at that figure honestly. Optimistic long-let quotes near R28,000 a month look respectable against the price until the R13,540 of monthly carry comes out, at which point the income is largely funding the estate rather than the owner. Treat it as a lifestyle asset with a rental offset, not as an income property.
They are different products holding the same membership. Vivante is apartment and retirement-oriented stock with a body corporate on top of the estate association, so it carries two layers of charge. Pearl Valley is the golf-oriented freehold side. A buyer choosing between them is choosing a dwelling type and a charge structure rather than choosing between two estates.
Drakenstein, not the City of Cape Town, and no metro figure applies. Drakenstein runs its own valuation roll, tariff, rebates and objection calendar, and its 2026/27 budget proposed a cap on residential rate increases. A buyer carrying a Cape Town rates assumption across to a Winelands estate will misprice the annual line, sometimes badly.
It narrows the market and deepens the commitment of who is left in it. An estate home sells to somebody who wants that estate, which makes pricing harder and the pool smaller than a metro apartment's, and it also means the buyer is rarely comparing on yield. That argues for a long intended hold, because thin liquidity matters least to an owner who was not planning to sell.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.