
Growthpoint at the V&A: The Counterparty You Can Read
It is the one Cape Town development counterparty whose accounts are public and audited. That changes what off-plan due diligence can actually establish.
By Cape Town Invest Editorial · Updated August 27, 2026 · 11 min read
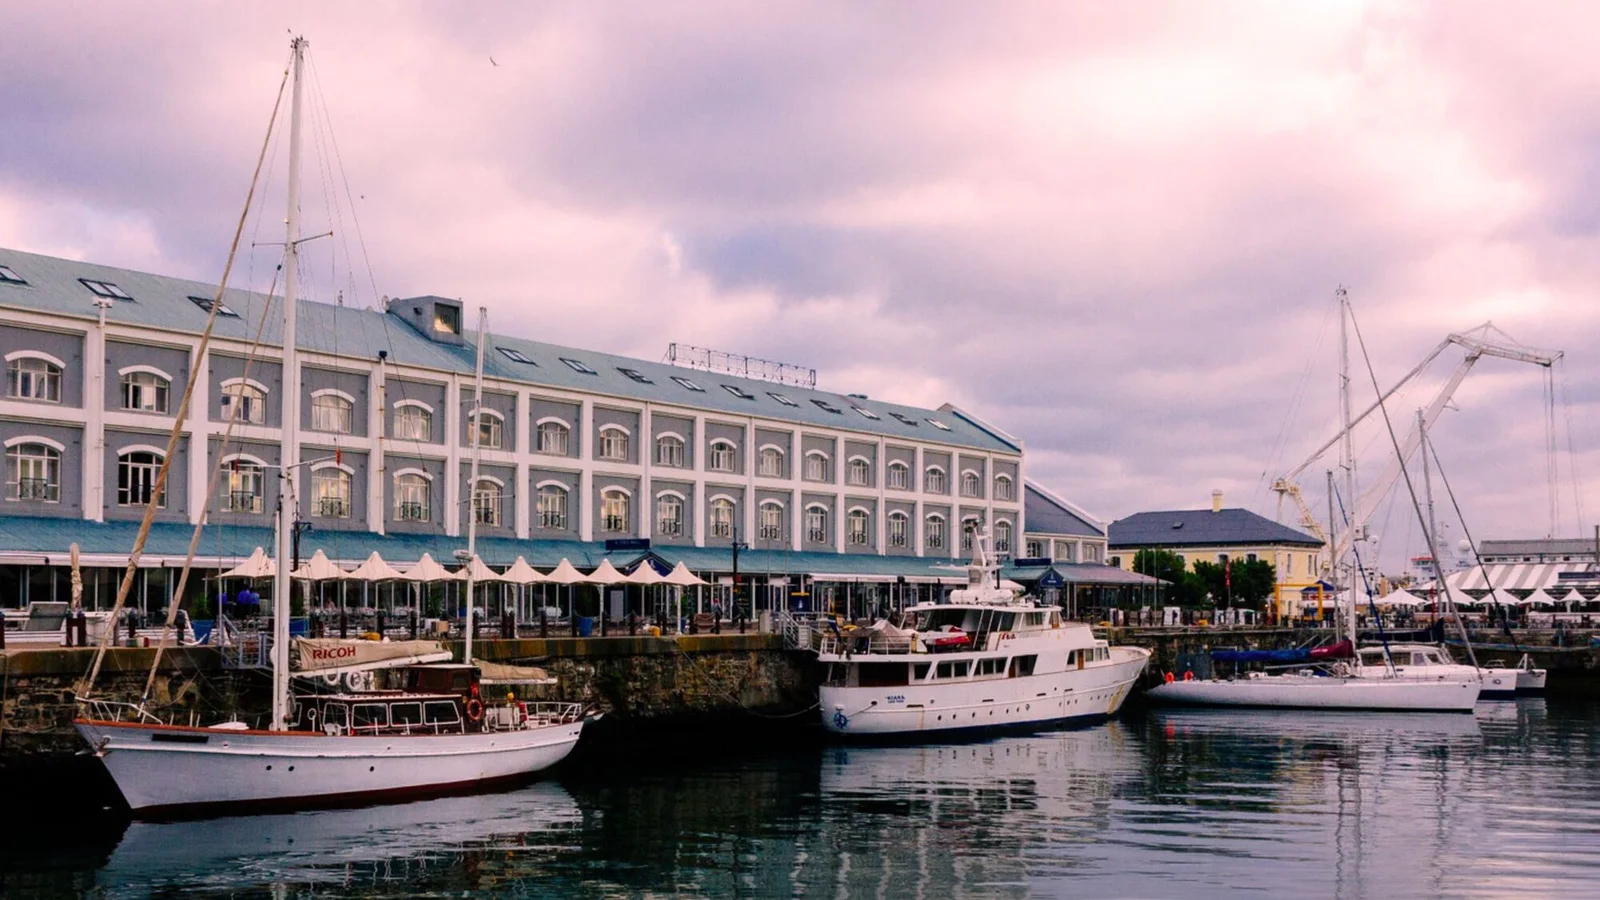
Quick answer: everything else about a V&A purchase is about scarcity and carry, and one thing about it is unique in Cape Town. Growthpoint is a listed real estate investment trust and a joint venture partner in the Waterfront, so its financial statements are public and audited. Every other developer covered on this site is a private company whose balance sheet a buyer simply cannot see. On off-plan, where you are underwriting a counterparty as much as a building, that is the difference between evidence and reputation.
Why does a listed counterparty change the analysis?
Because off-plan is not really a property transaction until the property exists. Until then it is a contract with a company, and the value of that contract depends on the company.
The standard way to assess a developer is a record of completed projects, and it is a reasonable proxy. It is also entirely retrospective: it tells you what the firm managed to finish in conditions that no longer apply. A private developer’s current financial position, its debt, its cash, its commitments across other sites, is not something a buyer can see at all.
A listed real estate investment trust reports publicly and on a cycle, with audited statements. That does not make a purchase safe. It makes the counterparty legible, which is a category of information most off-plan buyers in this market never get, and it is worth using rather than noting.
| A private developer | A listed counterparty | |
|---|---|---|
| Evidence available | Completed projects, reputation | The same, plus audited statements |
| What it tells you | What they finished before | What they are carrying now |
| When problems surface | Often at your scheme | On a reporting cycle, publicly |
| What it guarantees | Nothing | Nothing |
The last row matters as much as the others. Listing changes visibility, not outcome: a listed company can delay a scheme, revise a specification or conclude a phase is uncommercial, exactly as a private one can. What it cannot easily do is have that go unnoticed.
The general off-plan discipline that applies regardless of counterparty, why a launch levy is systematically the optimistic figure, what a developer’s own budget assumes, is set out in the off-plan versus resale comparison. Read this page as the counterparty layer on top of it, and the Rabie page for what a long private track record does and does not protect.
What the Waterfront is, as a place to own
An enclosed precinct with almost no capacity to grow, privately managed, inside a working harbour.
That combination produces the two forces that decide a V&A purchase, and they pull in opposite directions.
Scarcity supports the price. The precinct is bounded by working harbour, open sea and the city itself. Residential additions come from specific identified sites rather than from a development pipeline, which is why a scheme like the Granger Bay development draws the attention it does: here, new supply is an event, not a phase. An owner in an enclosed precinct is not competing with next year’s release, which is the risk that shapes ownership in a master-planned precinct still being built out.
Carry compresses the return. The precinct is privately managed rather than maintained by the City, and its residential levies rank among the highest in the metro. That is what the environment costs, and it is charged whether or not the unit is let.
What does that actually do to a yield?
It turns a respectable gross into a thin net, and the gap is larger here than almost anywhere in the city.
Silo District stock models roughly 4% to 6% gross on a long let. After levies at Waterfront levels, municipal rates at about 0.0064 in the rand for 2026/27, insurance, management and a vacancy allowance, that compresses to about 2.5% to 4.5% net. Both figures are modelled from listed prices against observed rents rather than audited returns, and the Silo District page works through the specific building.
Read honestly, that is not an income asset. It is capital preservation in an internationally recognised address, with a rental offset against the carry. A buyer who needs the property to pay for itself is reading about the wrong precinct, and a buyer who wants the address and understands the carry is reading about the right one. The V&A area page covers the precinct’s market in more detail.
The pros and cons therefore split cleanly:
- In your favour: a counterparty whose accounts you can read, a precinct that cannot easily be diluted by new supply, and an address with a genuinely international resale pool.
- Against you: the heaviest carry in the metro, a net yield that will disappoint anyone underwriting on gross, and a private management layer whose charges are not the City’s.
- Neither: listed status is information rather than protection, and should be used as such.
What to read before you commit
Two documents beyond the ordinary set, because the precinct is unusual in two ways.
The charges attaching to the unit, in full and in writing. The Waterfront is privately managed, so the shared environment is funded privately, and a buyer comparing a V&A levy against a suburb where the City maintains the streets is not comparing like with like. Establish what is charged, by whom, and what each charge funds.
Three years of the scheme’s financials and the reserve position. Where levies are already among the highest in the metro, a scheme that has nonetheless under-funded its reserve is telling you a special levy is coming on top of them. In a building at this price point that is a large number.
Then, if the purchase is off-plan, use the advantage this counterparty actually offers: read the published statements, or have an adviser read them. It is the only development on this site where that sentence is possible. What the same scarcity looks like from the other end of the Atlantic Seaboard, where the constraint is mountain and sea rather than a harbour wall, is on the Atlantic Seaboard guide.
What to establish before you offer
| Question | Where the answer is | Why here specifically |
|---|---|---|
| Every charge attaching to the unit | The seller, agent and managing agent | Private precinct management is not a City service |
| Reserve balance and its direction | Three years of financials | High levies plus a thin reserve means a special levy |
| The net, not the gross | Your own model | The gap between them is unusually wide here |
| The counterparty’s current position | Published financial statements | Uniquely available on this purchase |
| What is actually planned nearby | The precinct, in writing | Supply here is an event, so each one matters |
The instruction that carries most of it is the third. In most of Cape Town a gross yield is a rough guide to a net one. At the Waterfront it is not, and a buyer who underwrites on gross will be wrong by more than a percentage point.
For a developer whose master-planned work sits outside the Western Cape entirely, and what that says about reading a national record, see the Devmco review.
Sources: Growthpoint’s status as a listed real estate investment trust and joint venture partner in the V&A Waterfront is a matter of public record, and its financial statements are published on its own reporting cycle. City of Cape Town budget 2026/27 adopted 29 June 2026 for the rates figure. Sectional Titles Schemes Management Act 8 of 2011 for the levy and reserve fund regime; the precinct management layer is constituted separately. Yield figures are Cape Town Invest models built from listed prices against observed rents, not audited returns. Current as at 27 August 2026.
Frequently Asked Questions
Its accounts are public. Growthpoint is a listed real estate investment trust and a joint venture partner in the V&A Waterfront, so its financial statements are published and audited on a regular reporting cycle. Every other developer on this site is a private company whose balance sheet a buyer cannot see. On an off-plan purchase, where you are underwriting a counterparty as much as a building, that is a material difference.
Because off-plan is a promise, and a promise is only as good as whoever made it. Delivery risk is the chance a scheme is late, downscaled or never finished, and the usual way to assess it is a track record of completed projects, which is evidence about the past. A published balance sheet is evidence about the present, and it is the only form of it most buyers will ever get.
No, and it should not be read that way. A listed company can still delay a scheme, change a specification or decide a phase is uncommercial. What listing changes is your ability to look: reporting obligations mean poor performance surfaces publicly rather than privately, and a buyer can form their own view instead of relying on a brochure. It is better information, not a guarantee.
Less than most buyers expect, because the carry is heavy. Silo District stock models roughly 4% to 6% gross on a long let, compressing to about 2.5% to 4.5% net once levies among the highest in the metro and municipal rates at about 0.0064 in the rand come out. It is capital preservation in a recognised international address with a rental offset, not an income asset.
Very little, which is a large part of the case. The precinct is enclosed by working harbour, sea and the city, so residential supply is limited to specific identified sites rather than to a pipeline. That scarcity is what supports pricing, and it is also why the Granger Bay development attracts the attention it does: within this precinct, an addition is an event rather than a phase.
Two things beyond the ordinary. The precinct is privately managed rather than maintained by the City, so establish exactly what charges attach to the unit and what they fund. And because levies here are among the highest in the metro, the levy statement and the reserve position matter more to your net than the asking price does, read three years of financials before you accept any modelled yield.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.