
Silo District Residences: V&A Waterfront Investor Review
Silo District residences: No 2 and No 3 Silo at V&A Waterfront, 31+79 units, GBCSA green ratings, ultra-premium resale, foreign buyer guide.
By Cape Town Invest Editorial · Updated September 3, 2026 · 11 min read
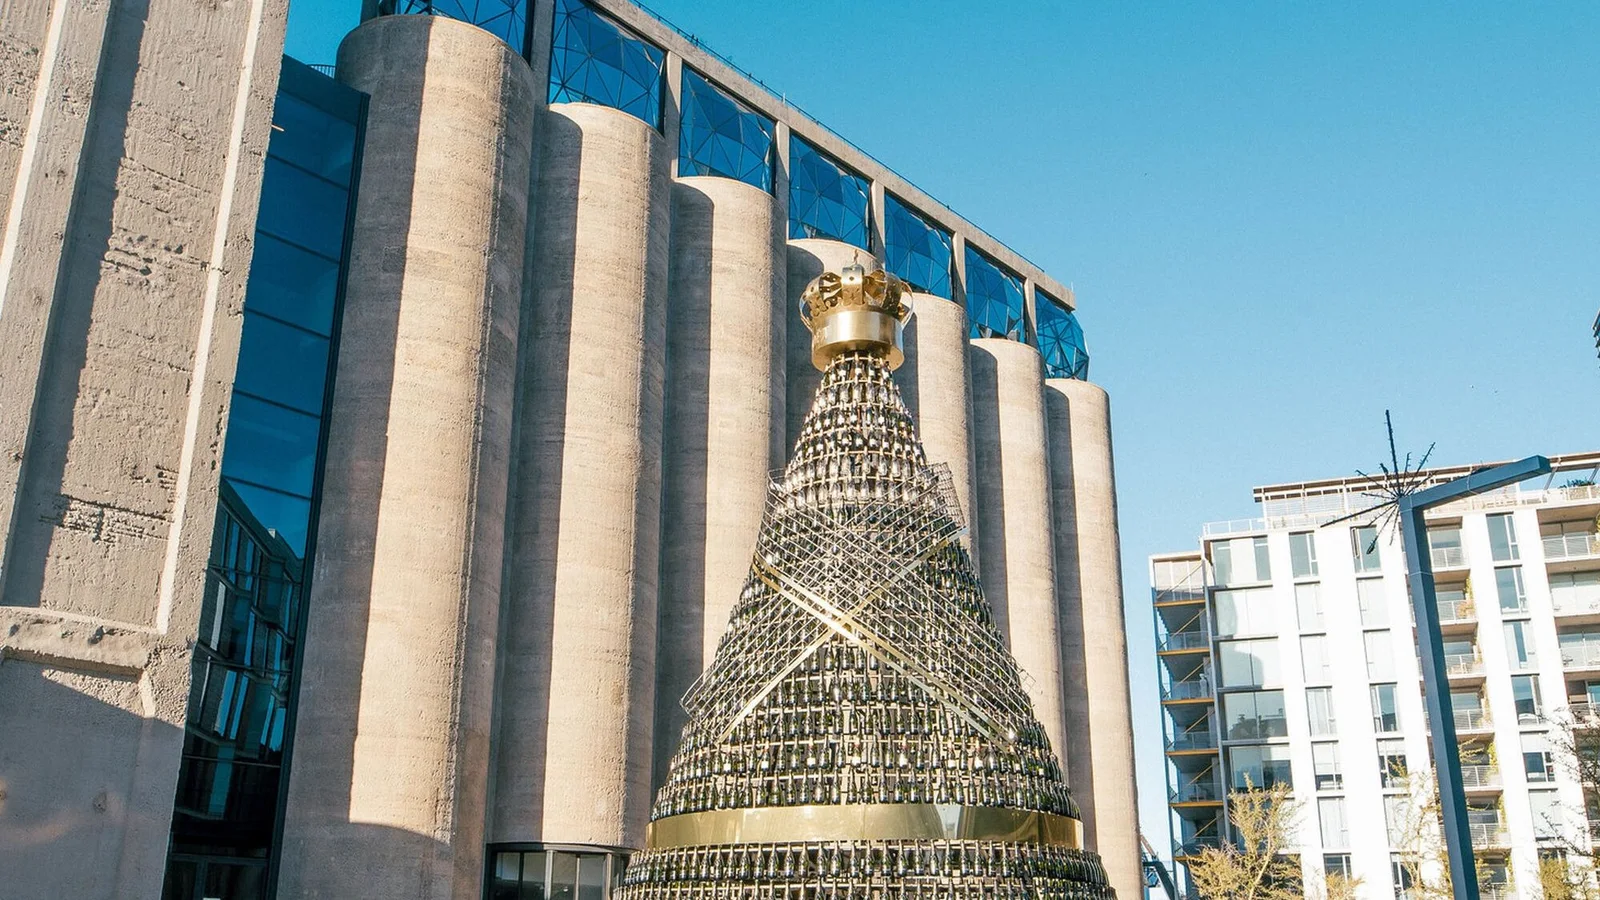
Quick answer: Silo District residences are the V&A Waterfront’s completed luxury towers, No 2 Silo (31 units, 2013, 4-star green) and No 3 Silo (~79 units, 2017), wrapped around Zeitz MOCAA. They are ultra-premium resale assets stewarded by Growthpoint Waterfront, not income plays like Century City Rabie stock.
How should you underwrite Silo District?
Silo District is completed trophy stock, not an off-plan launch: 31 units at No 2 Silo from 2013 and about 79 at No 3 Silo from 2017, wrapped around Zeitz MOCAA in the converted Grain Silo. Long-let models about 4% to 6% gross and 2.5% to 4.5% net after Waterfront levies and rates.
The surrounding towers, designed by VDMMA and allied teams, fragment public realm space to prioritise pedestrians over vehicles. Resale liquidity comes from international buyers who want museum precinct culture on their doorstep.
Growthpoint Waterfront and PIC stewardship matter because body corporate governance and precinct management stay institutional rather than boutique. That reduces surprise special levies relative to unknown developers, but it does not make the levies cheap. Waterfront sectional title often carries among the highest monthly charges in Cape Town, which compresses net yield even when gross rents look strong.
Pair this review with the V&A Waterfront area guide, Green Point spillover analysis, and the forward-looking Granger Bay Waterfront pipeline note.
What numbers define Silo District residences in 2026?
Silo District residences are two completed towers: No 2 Silo with 31 one and two-bedroom units from 2013, and No 3 Silo with about 79 apartments from one-bedroom to five-bedroom penthouses from 2017. Modelled long-let gross runs about 4% to 6%, net about 2.5% to 4.5%. Primary sales are closed.
| Tower | Units | Completion | Format | Green credential |
|---|---|---|---|---|
| No 2 Silo | 31 | 2013 | 1- and 2-bed, rooftop pool | 4-star GBCSA (early tool) |
| No 3 Silo | About 79 | 2017 | 1-bed to 5-bed penthouses | Sustainability core design |
| No 4 Silo | Commercial/gym | , | Virgin Active Collection | Non-residential |
| No 5 Silo | Mixed office/hotel | , | Business and leisure | Non-residential |
| Investor metric | Indicative band |
|---|---|
| modelled gross long-let | About 4% to 6% |
| modelled net long-let | About 2.5% to 4.5% |
| Buyer profile | Trophy, lifestyle, capital preservation |
| Foreign surcharge | None |
| Primary sales | Closed, resale only |
No 2 silo: the first residential silo
No 2 Silo is a 31-unit body corporate completed in 2013, which is very small by Cape Town standards. Each owner carries roughly 3.2% of every communal cost, so a lift replacement or harbour-exposure waterproofing lands hard rather than diluting across hundreds of quotas. Pull the arrears schedule and reserve fund balance, not the monthly levy alone.
One or two owners in arrears distort the whole levy roll at this scale, which is why the arrears age analysis matters more here than in a 200-unit block.
Completed in 2013 with one and two-bedroom formats and a rooftop pool, No 2 Silo was also among the first residential buildings in South Africa to carry a four-star Green Building Council rating. That was genuinely early, and it means the rating was awarded under a first-generation tool. Ask what the rating covered in practice: efficient services and envelope design usually translate to lower tenant utility bills, which supports retention when tariffs rise, but it says nothing about the levy itself.
For resale bidders, the practical constraint is supply. Thirty-one apartments produce very few transactions per year, so comparables are thin and pricing is set by whoever is in the market that month rather than by a deep run of recent sales. Ask the managing agent how many units transferred in the past 5 years. Expect to underwrite from precinct evidence and the V&A Waterfront area view rather than from a clean set of in-building comps, and build the body corporate review into your offer timeline before you waive conditions.
No 3 silo: scale and penthouse scarcity
No 3 Silo is a 79-unit scheme completed in 2017, running from one-bedroom apartments to five-bedroom penthouses. At more than twice the size of No 2 Silo’s 31 units, one owner in arrears carries roughly 1.3% of the levy roll rather than 3.2%, and small-format comparables are deep enough to price against.
At the penthouse end there is effectively no series: a handful of units, each with a different footprint, view line, and terrace area, means every sale becomes its own negotiation. Ask the managing agent how many units of your exact size have transferred in the past 5 years, and how long each sat before it sold.
Format range also decides which buyer pool you exit into. One and two-bedroom units at No 3 compete directly with the V&A Waterfront letting market and with Green Point stock a short walk away. Penthouses compete with nothing in particular, which cuts both ways on price.
What are the pros, cons and Silo District suits?
Silo District suits a buyer whose first objective is capital preservation in a recognised international address and whose second objective is income. Completed stock removes delivery risk entirely: both towers were handed over years ago, so there is no developer covenant to underwrite and no construction programme to police. What you take on instead is carry. Levies at the Waterfront rank among the highest in the metro, municipal rates run at roughly 0.64 cents per rand above the first R620,000 of value, and the two together are what pull a modelled gross long-let of about 4% to 6% down to a modelled net nearer 2.5% to 4.5%. Non-residents face no surcharge and can usually bond about half the purchase price locally, so the equity cheque is large and the income it earns is thin. Buyers who need the asset to pay for itself are reading about the wrong building.
Pros
- Museum and design precinct anchor with global recognition.
- Completed stock, no off-plan delivery risk.
- Institutional precinct management via Growthpoint and PIC.
- Strong foreign buyer liquidity at the top end.
- Pedestrian harbour lifestyle unmatched in Cape Town.
Cons
- Ultra-premium entry pricing.
- High levies and rates compress net yield.
- Sparse resale, thin comparables.
- Short-stay rules may limit Airbnb strategies.
- New Waterfront supply from Granger Bay pipeline eventually adds competition.
The trophy buyer accepts low modelled net for harbour-museum address.
The foreign capital preservation buyer diversifies into rand assets with liquidity on the Atlantic Seaboard fringe.
The income investor should stop here and read SkyWater Century City instead.
The pipeline tracker holds Silo today while monitoring Granger Bay for future supply impacts.
Waterfront levy reality check
The gap between gross and net at the Waterfront is wider than almost anywhere else in the metro, and levies do most of the damage. A Silo levy is not just building maintenance and insurance: it funds concierge, 24-hour manned security, precinct cleaning, plant and lift servicing on harbour-exposed equipment, and a share of the sustainability systems the towers were designed around. Salt air accelerates corrosion on façades, balustrades, and external plant, which shortens replacement cycles compared with an inland building of the same age.
Municipal rates compound it. City of Cape Town exempts the first R620,000 of value and then charges roughly 0.64 cents per rand per year, so an ultra-premium valuation produces an annual rates bill that a Century City apartment simply does not generate. That is a fixed cost independent of whether the unit is let.
Three checks before you bid:
- Ten-year maintenance plan and current reserve fund balance, since the STSMA requires the plan and its funding is what stands between you and a special levy.
- Special levy history for the past five years, including precinct-level charges raised before your ownership.
- Whether the levy is quoted inclusive or exclusive of utilities, parking bays, and storage.
Run the resulting number through the levies guide and rebuild net yield from it. A trophy Waterfront asset can still be the right purchase, but only when you have priced the carry honestly rather than assuming a percentage borrowed from cheaper stock.
Comparing silo towers for resale bids
Bidding on a Silo resale is a choice between two body corporates. No 2 Silo is 31 units with a design-led professional buyer pool and thin liquidity; No 3 Silo is about 79 units with a deeper format range and a trophy penthouse tier. Modelled net on either sits near 2.5% to 4.5%.
| Question | No 2 Silo | No 3 Silo |
|---|---|---|
| Body corporate size | 31 units | About 79 units |
| Typical buyer | Design-led professional | Trophy penthouse buyer |
| Green credential | 4-star GBCSA (2013) | Sustainability-led 2017 design |
| Liquidity | Very thin | Thin but deeper format range |
| View premium | Harbour and city | Broader port and mountain panoramas |
When a Silo unit lists, move quickly but never skip sectional title register review, Waterfront transfers sometimes involve special levies for precinct upgrades that predate your ownership.
Tourism, museums, and silo square events
Zeitz MOCAA is why this precinct reads as a cultural address rather than a harbour extension, and the effect is measurable in letting. Museum footfall holds Silo Square traffic through the shoulder season, supporting street-level restaurant and gallery tenancies. Trophy buyers pay for that narrative, but modelled net still lands near 2.5% to 4.5%.
The flip side is that you are buying a home inside a working visitor destination. Silo Square hosts events, and event days bring amplified sound, marquee build-up and strike, crowd flows, and restricted vehicle access. Lower floors and units facing the square carry more of this than upper units facing the port. Three things to collect before you bid:
- The events calendar and the precinct’s noise and vehicle access protocol from the managing agent.
- One ordinary weekday visit and one visit during an event or a peak summer weekend.
- Written confirmation of what the scheme permits on short-stay letting.
Tourism density also shapes letting strategy. High visitor volume makes short-stay economically tempting, but Waterfront precinct rules and body corporate conduct rules often restrict it more tightly than a suburban block would, and City of Cape Town short-term rental rules sit on top of that. Confirm in writing what the scheme actually permits before you underwrite any nightly-rate scenario. If short-stay is off the table, your model has to work on long-let alone, which at this price point means accepting a low single-digit modelled net.
Gbcsa credentials and operating cost
No 2 Silo’s four-star Green Building Council rating was pioneering for South African residential in 2013, and No 3 Silo extended it with harbour-tuned façade and systems design. Lower utility intensity is a tenant-retention tool, not a levy discount: security, concierge and precinct fees dominate the monthly charge on a R12 million unit.
Resale buyers should ask whether major plant replacements are scheduled in the next five years and whether the body corporate has funded them in reserves. A special levy on a R12m Silo penthouse can exceed R200,000 per owner in a single year when lifts or façade maintenance cycle.
Institutional buyers sometimes benchmark Silo resales against London or Lisbon trophy flats on a price-per-square-metre basis; when sterling or euro strength favours rand entry, liquidity improves, but repatriation planning must be documented from day one through authorised dealer banks.
No 2 versus No 3 buyer personas
The two towers attract different money for structural reasons. No 2 Silo is 31 one and two-bedroom units from 2013, the smaller ticket, lettable to professionals at a rent a salary can carry. No 3 Silo is about 79 units from 2017 running up to five-bedroom penthouses, where modelled net drops toward 2.5%.
No 2 suits a buyer who wants a genuine Waterfront pied-a-terre, uses it several weeks a year, and lets it long-term in between. There is an actual tenant pool of professionals and relocating executives at that size.
No 3 Silo spans a much wider format range. The one-bedroom end behaves like No 2. The penthouse end does not: at that size and price the tenant pool thins to corporate lettings and a handful of individuals, and the asset becomes primarily a capital-preservation and owner-use decision. Yield stops being the metric that governs the purchase.
That difference should change your due diligence emphasis. In No 2, the small body corporate is the main risk, so reserves and arrears dominate. In No 3, format liquidity is the main risk, so ask how many units of your specific size have transacted in the past 5 years and how long they sat. Neither tower is an income vehicle. If yield is the objective, the honest comparison is against inland stock such as SkyWater Century City rather than against each other.
What to verify next
Engage a Waterfront-experienced conveyancer, pull body corporate financials for the specific tower, and model transfer duty via the cost of buying guide. Rebuild net yield conservatively with the rental yield guide. Foreign buyers: confirm FICA and deal receipts per the foreign buyer hub. Do not pay off-plan deposits on any Silo marketing, primary sales are closed.
Frequently Asked Questions
Silo District residences are the V&A Waterfront's luxury apartment towers around the historic Grain Silo and Zeitz MOCAA museum. No 2 Silo completed in 2013 with 31 sectional title units, one and two bedrooms, rooftop pool, and a 4-star Green Building Council rating. No 3 Silo completed in 2017 with about 79 apartments from one-bedroom units to five-bedroom penthouses on Silo Square with harbour and mountain views.
No. Both No 2 Silo and No 3 Silo are completed and trade on the resale market only. Availability is sporadic and price-led. Treat each resale as a standalone transaction with full body corporate due diligence, transfer duty, and compliance certificate checks.
Ultra-premium Waterfront stock typically modelled low single-digit net yields on long-let, often roughly 2.5% to 4.5% net after high levies, rates, and management, despite stronger gross asking rents. Capital preservation, liquidity, and owner-use drive pricing more than income. All figures are modelled and directional, not guaranteed.
Yes. South Africa imposes no foreign buyer surcharge on sectional title at the V&A Waterfront. Non-residents usually finance up to 50% with a local bond and introduce offshore capital with exchange-control recording. Engage a conveyancer early because Waterfront transfers can involve complex body corporate approvals.
Silo District is completed, occupied ultra-premium stock beside a global museum anchor. Granger Bay is a proposed Growthpoint and PIC expansion with reclamation approvals expected around late 2027. Silo suits buyers who want a tangible asset today; Granger Bay suits investors tracking pipeline optionality without paying for unapproved land.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.