
Clifton Property, Cape Town: Structure Beats Yield
At a R30 million Clifton ticket the ownership name decides more than the yield: CGT inclusion of 40% or 80%, and section 35A withholding at 7.5% or 15%.
By Cape Town Invest Editorial · Updated September 7, 2026 · 11 min read
Quick answer: at a Clifton price point the ownership decision moves more money than the property decision. An individual includes 40% of a capital gain in taxable income against 80% for a company or trust, and section 35A withholds 7.5%, 10% or 15% of the sale price depending on the same choice. On a R30 million purchase those percentages become millions, while the difference between a good and a bad yield here is a rounding error.
Why does ownership structure dominate at this price?
Structure decides the outcome here because percentages applied to large numbers produce large differences. The choice between holding personally, through a company or through a trust changes both the capital gains inclusion rate and the section 35A withholding, and neither is adjustable after transfer without buying the property again.
| Holder | CGT inclusion | Effective CGT ceiling | Section 35A withholding |
|---|---|---|---|
| Individual | 40% | about 18% | 7.5% of price above R2 million |
| Company | 80% | about 21.6% | 10% of price above R2 million |
| Trust | 80% | about 36% | 15% of price above R2 million |
A worked example makes the gap concrete. A R30 million Clifton apartment sold years later at a R10 million gain produces roughly R1.8 million of capital gains tax in an individual’s hands and roughly R3.6 million in a trust’s, before the annual exclusion and any base cost refinements. The withholding follows the same ranking: R2,250,000 against R4,500,000, paid to SARS within 21 days of registration regardless of what the eventual assessment shows. Cape Town Invest treats the structure question as the first decision in a Clifton purchase rather than a formality for the conveyancer, and the capital gains tax guide sets out how base cost is built.
When does a trust or company still make sense?
Trusts and companies solve problems that are not tax problems, and buying one for tax reasons at this price point usually costs money. The reasons that survive scrutiny are about succession and control rather than about rates.
- Estate planning across jurisdictions. A trust can avoid a South African estate freezing while a foreign estate is administered, which matters when heirs are in another country.
- Multiple owners. Where several family members or partners hold together, a company gives a clean shareholding rather than undivided co-ownership.
- Succession without transfer. Shares or beneficial interests can pass without a property transfer and a second transfer duty bill.
Against those, the trust pays roughly double the effective capital gains rate and suffers 15% withholding on exit rather than 7.5%. Our reading of Clifton files is that the structure should follow the reason for holding: a buyer intending a long family hold across generations has a case, and a buyer intending to own for ten years and sell has a costly one. The ownership and tax hub compares the structures in full.
What does the exit look like in practice?
Selling a Clifton property runs the same machinery as anywhere in South Africa, with the numbers scaled up enough that timing choices become expensive. Section 35A takes its share at registration, and the balance follows the ordinary transfer sequence.
- Withholding at registration. The conveyancer holds back 7.5%, 10% or 15% of the price above R2 million and pays SARS within 21 days.
- A directive, if the real liability is lower. An NR03 lodged before registration reduces the withholding rather than leaving the excess with SARS until assessment, which on a R30 million sale can free millions months earlier.
- Repatriation clearance. Since late 2025 an authorised dealer requires a SARS Approval for International Transfer PIN or a Manual Letter of Compliance before remitting non-resident proceeds abroad.
Insider tip: at this price point the NR03 directive is worth lodging even when the gain is substantial, because the withholding is calculated on price and the tax on profit, and the two diverge most where base cost is high. A Clifton apartment bought at R24 million and sold at R30 million carries a R2.25 million withholding against roughly R1.08 million of actual capital gains tax for an individual. The section 35A guide covers the application and its timing.
What is actually scarce in Clifton?
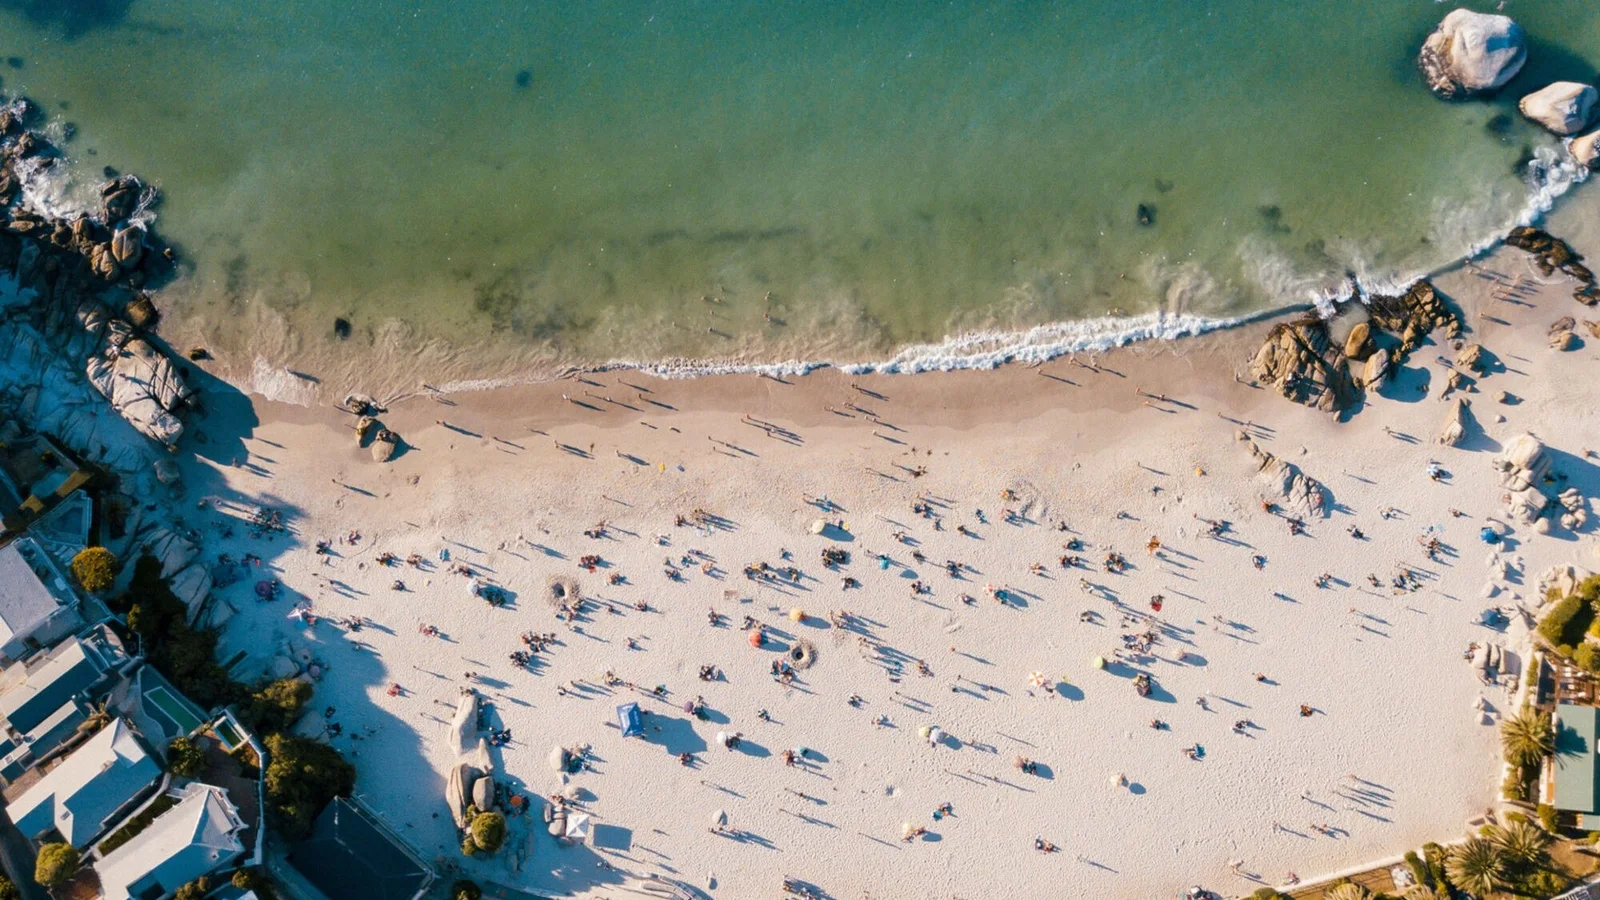
Scarcity in Clifton is physical and specific rather than general. The suburb is four small beaches with one access road above them, so buildable land is fixed and new supply appears only where an existing building is replaced.
Stock splits into two pools that behave differently. Terraced sectional title blocks above Victoria Road carry the bulk of the units and trade with reasonable frequency; the smaller number of bungalows below the road trade rarely enough that a single sale sets the perceived market for the whole tier. Per-square-metre pricing reaches roughly R120,000 to R200,000+ across the suburb, among the highest in South Africa, and the spread within one building between a full view line and a partial one is wide enough to matter more than the suburb average. The Atlantic Seaboard guide places Clifton against the strip’s other seven suburbs on both price and yield.
Do the four beaches differ as investments?
They differ enough that a Clifton address alone tells a buyer very little. The four beaches sit in sequence below Victoria Road, and each one carries a different mix of access, shelter and stock, which shows up in both price and how quickly a unit resells.
- First Beach is the most exposed to wind and swell, with the longest stair access from the road above, and it trades at a discount to the sheltered beaches for exactly that reason.
- Second and Third Beaches carry the bulk of the bungalow stock and the deepest buyer familiarity, which makes them the reference point most valuations are argued from.
- Fourth Beach has the easiest access, a Blue Flag designation and the most public activity, which raises amenity and lowers privacy at the same time.
The practical effect is that comparables must come from the same beach and the same tier, above or below Victoria Road, or they are not comparables at all. Our reading of Clifton sales is that the spread between a full and a partial view line inside one building routinely exceeds the spread between two beaches, so a buyer who anchors on a suburb average will misprice in both directions. Walk the specific unit at the time of day it would be used, and confirm what the stair access actually involves, because on this hillside it is a daily cost that a photograph never shows.
What should a buyer settle before offering?
Four decisions belong before an offer in Clifton, and three of them have nothing to do with the property. The order matters, because each constrains the next.
| Decision | Why it comes first | Cost of getting it wrong |
|---|---|---|
| Ownership name | Fixed at transfer, sets CGT and withholding | A second transfer and a second duty bill |
| Holding horizon | Determines whether structure costs pay off | Years of a higher inclusion rate |
| Funding route | Non-residents borrow to about 50% locally | Deal size capped after an offer is made |
| View line and tier | Sets both price and resale depth | A partial view priced as a full one |
With those settled the transaction becomes routine, since nothing in South African conveyancing treats a foreign purchaser differently at the point of entry. The duty scale, the transfer sequence and the exchange-control steps are set out in the pillar investment guide.
Resale pricing on the Ridge Road strip behaves differently from the bungalow blocks below it, and The Ridge is the reference scheme for that end of the suburb.
Sources: SARS capital gains tax guide for inclusion rates; section 35A of the Income Tax Act 58 of 1962 for withholding rates and the 21-day payment period; SARB exchange control circulars of late 2025 for the transfer clearance requirement. Worked examples are illustrative and ignore the annual exclusion and base cost refinements; obtain tax advice for your own structure before signing. Yields and per-square-metre bands are modelled and directional. Current as at 27 August 2026.
Frequently Asked Questions
For most foreign buyers, personally. An individual includes 40% of a capital gain in taxable income, giving an effective ceiling near 18%, while a company or trust includes 80%, pushing effective rates to roughly 21.6% and 36%. On a R30 million purchase later sold at a R10 million gain, that difference is measured in millions. Trusts and companies solve estate and succession problems rather than tax problems, so the structure should follow the reason for holding, not a general preference.
On a R30 million sale by a non-resident individual, the conveyancer withholds 7.5%, or R2,250,000, and pays it to SARS within 21 days of registration as an advance against capital gains tax. A company pays 10% and a trust 15%, which on the same price is R3 million and R4.5 million. Where the real capital gains liability is lower, an NR03 directive lodged before registration reduces the withholding instead of leaving the difference with SARS until assessment.
Because per-square-metre pricing reaches the national ceiling while rent does not follow. Clifton stock trades at roughly R120,000 to R200,000+ per square metre on a scarce, view-line supply, and net yields fall below 4%. The suburb is bought for what it stores rather than what it produces, and treating it as an income asset misreads it.
Geography and tenure. The suburb is four small beaches with a single access road above them, so buildable land is fixed and new supply arrives only as redevelopment of an existing site. Stock splits between terraced sectional title blocks above Victoria Road and a small number of bungalows below it, and the bungalow pool in particular is small enough that individual sales set the perceived market.
None on ownership. A non-resident may take freehold or sectional title in Clifton on the same terms as a citizen, with no surcharge and no residency requirement. The differences appear at exit rather than entry: section 35A withholding above R2 million, and since late 2025 a SARS clearance requirement before an authorised dealer will remit proceeds abroad.
Thinner than Camps Bay, and that is the trade for scarcity. Camps Bay cleared 29 prime sales in 2025 against a smaller count in Clifton, so exit timing depends more on finding the specific buyer than on market conditions. At this price point the buyer pool is global rather than local, which widens it, but a seller should plan a longer marketing period than the strip average.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.