
Sea Point vs Camps Bay 2026: Two Different Businesses
Sea Point models 7.5% net and re-lets in weeks. Camps Bay models 4.4% and earns in a six-week window. One is an investment, the other is a store of value.
By Cape Town Invest Editorial · Updated August 27, 2026 · 11 min read
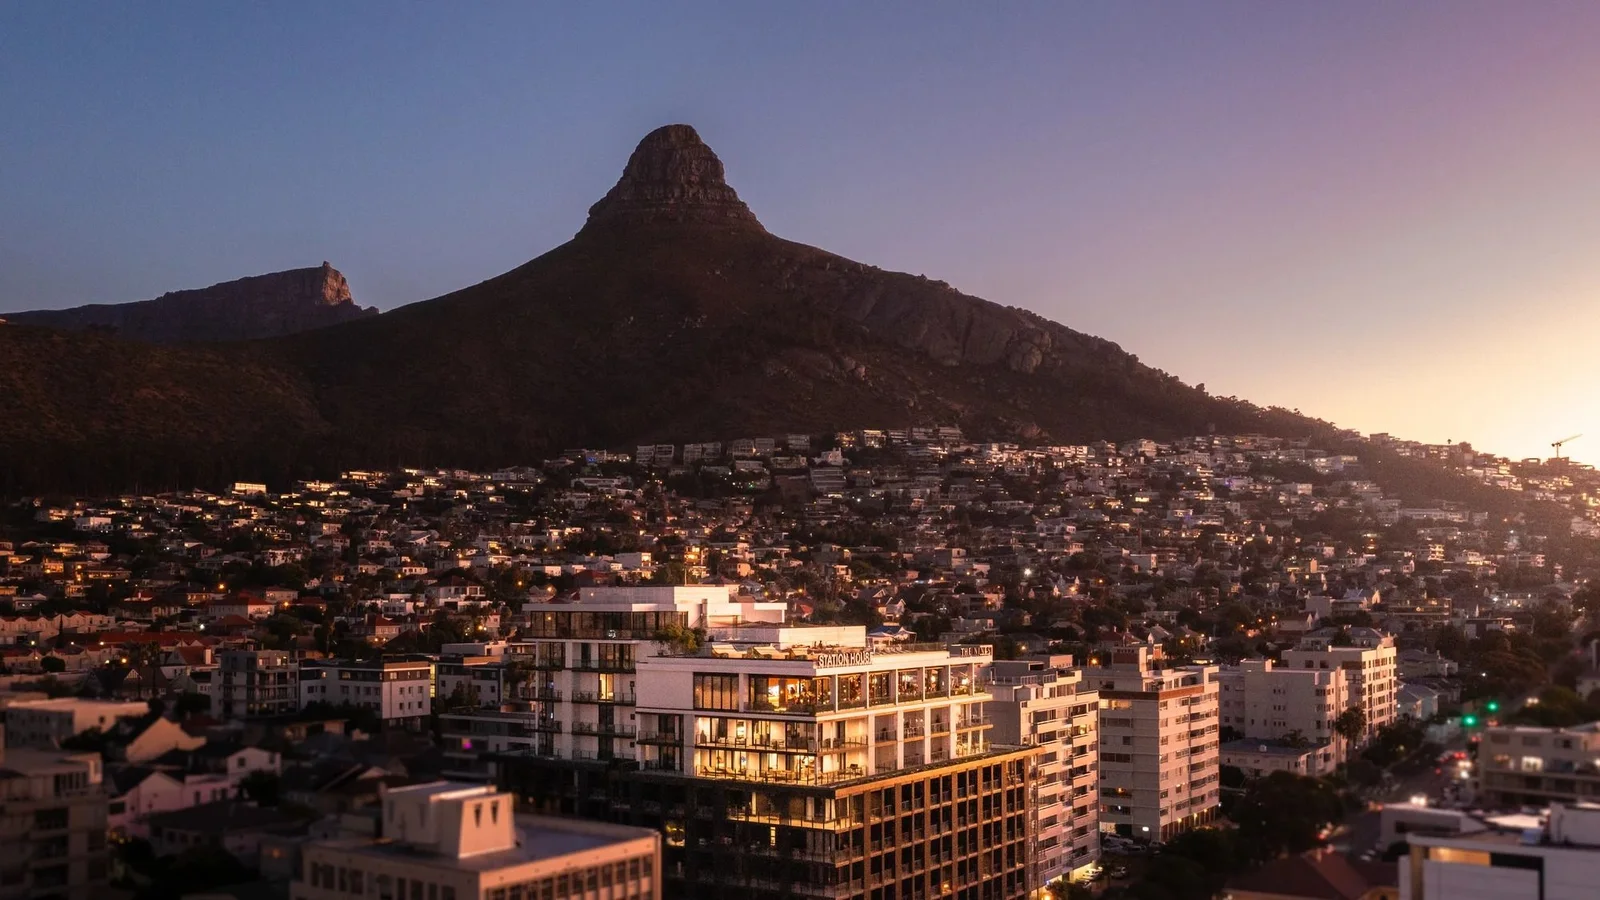
Quick answer: these are two different businesses sharing a coastline. Sea Point is an income asset that models about 7.5% net, re-lets in weeks and pays monthly. Camps Bay is a store of value that models about 4.4% net, earns most of any nightly revenue in a six-week window, and returns capital durability and a reliable exit instead of cash flow. Buying one while expecting the other is the most common mistake on this strip.
What does each one actually pay?
The yield gap between two suburbs eight minutes apart is the widest on the Atlantic Seaboard, and it is arithmetic rather than fashion.
| Measure | Sea Point one-bedroom | Prime Camps Bay |
|---|---|---|
| Gross yield, modelled | about 9.7% | about 6.8% |
| Net yield, modelled | about 7.5% | about 4.4% |
| Cost stack removes | about a fifth of gross | about a third of gross |
| Typical void when one opens | weeks | months outside summer |
The cause is the ratio between price and achievable rent. Levies, municipal rates, maintenance, letting commission and vacancy all scale with the property; rent scales with what a tenant earns. In Sea Point those two sit close together, so the stack takes a smaller bite from a higher base. In Camps Bay the entry price runs at multiples of the metro median and the rent does not, so the same costs take a third of a smaller number. The gross versus net guide works the arithmetic.
Why does Sea Point re-let so much faster?
Because it has a weekday. Sea Point holds enough people, shops, schools and services to work as an ordinary suburb from Monday to Thursday in July, and Camps Bay largely does not: its street life follows the season, and so does the market for a twelve-month lease on it.
That produces a tenant pool wider than anywhere else on the strip: professionals working in the CBD and the V&A, remote workers, students and retirees, renewing continuously rather than in a season. A Camps Bay long let meets a smaller and more specific market, so a vacancy that opens in May can run for months while the same vacancy in Sea Point fills in weeks. A bond instalment is paid by months that are let, not by the rent a let month could theoretically achieve, which is why a buyer carrying debt should read the vacancy gap here before the yield gap. The Sea Point page covers the suburb in detail.
How does the nightly-let question differ between them?
It changes Camps Bay’s economics and Sea Point’s risk profile, which is a distinction most comparisons miss.
- In Camps Bay nightly letting can lift gross revenue substantially and does so in a concentrated window: December and January carry most of the year, peak rates on prime stock reach about R4,500 a night, and the winter months can stand empty. Revenue arrives in a lump while a bond falls due monthly.
- In Sea Point the nightly calendar is flatter and the regulatory exposure is larger, because the draft City by-law now out for comment lands on a bigger stock of nightly units here than in any other suburb on the coast. What that draft proposes, and by when, is set out on the Sea Point page.
The asymmetry that matters is in who votes. A scheme’s own conduct rules can shut nightly letting down regardless of what the City decides, and the vote that does it is taken by the owners in the building. In a Camps Bay block where most owners let nightly, that vote is unlikely to pass; in a Sea Point block where most owners live in their units or hold long tenants, it can pass comfortably, and the buyer relying on nightly income is outnumbered from the day of transfer. Count the owner-occupiers before you count the nights. The mechanism, the threshold and what binds an owner who bought earlier are set out in the body corporate guide.
Which one is easier to leave?
Camps Bay, and that is the strongest argument for paying its premium. The suburb recorded 29 prime sales in 2025, the deepest transaction count on the Atlantic Seaboard, and it sells to buyers who have often never visited Cape Town, which widens the pool at exit beyond the local and semigration market.
Sea Point exits into a different market: buyers who have run the yield arithmetic and are comparing it against the City Bowl and the northern suburbs. That market is active and it prices on numbers, so a Sea Point apartment sells at what its income justifies. A Camps Bay apartment sells at what the address is worth to someone who wants it, which is a less predictable number and a more durable one. Both mechanics are set out in the Atlantic Seaboard guide, which ranks all eight strip suburbs on one basis.
What does each one demand from the owner?
Very different amounts of attention, and this is where foreign owners most often misjudge the purchase.
A Sea Point apartment on a twelve-month lease is close to passive: a tenant, an agent, a levy debit and an annual rates account. A Camps Bay apartment run nightly is an operating business with cleaning at roughly R450 a changeover, platform commission near 15%, management around 20% of collected revenue where an agent runs it, and a calendar that needs managing across perhaps 90 turnovers a year. The pros and cons split on temperament rather than on capital: the same property produces a good business for an owner who runs it personally and a thin one for an owner who outsources every part of it. The Camps Bay page works the nightly arithmetic against a long let on the same unit.
Which should you buy?
The choice is clean once the two are described as what they are rather than as better and worse versions of the same thing.
| Priority | Better fit | Why |
|---|---|---|
| Monthly income | Sea Point | About 7.5% net against 4.4% |
| Fast re-letting and low vacancy risk | Sea Point | The strip’s only dense tenant pool |
| Capital preservation and a reliable exit | Camps Bay | 29 prime sales in 2025, global recognition |
| A passive holding from abroad | Sea Point on a long let | A twelve-month tenancy needs little attention |
| Willing to run an operating business | Camps Bay nightly | Peak rates near R4,500 a night in season |
| Least regulatory exposure | Camps Bay long let | Neither by-law nor conduct rules bite on a long let |
Whichever way it lands, the entry cost is the same on both: an identical duty scale, no surcharge for a foreign passport, and the same rates formula on very different valuations. The pillar investment guide has that arithmetic.
Sources: Cape Region Atlantic Seaboard sales report for 2025 transaction counts; Sectional Titles Schemes Management Act 8 of 2011 for the 75% special resolution threshold; City of Cape Town draft short-term letting by-law published August 2026, comment open to 5 October 2026; Airbtics and AirROI platform bands for nightly rates. Yields are modelled from listing and platform data rather than audited accounts. Current as at 27 August 2026.
Frequently Asked Questions
They are not the same kind of asset, so the answer depends on what the money is for. Sea Point models about 9.7% gross and 7.5% net on a one-bedroom, re-lets in weeks and produces monthly cash. Camps Bay models about 6.8% gross and 4.4% net, and its return arrives as capital durability and resale liquidity rather than as income. An investor wanting yield should buy Sea Point; a buyer wanting a globally recognised store of value should buy Camps Bay and stop treating the yield as the case.
Because costs scale with the property while rent scales with what a tenant can pay. The same stack of levies, municipal rates, maintenance, letting commission and vacancy removes about a fifth of gross in Sea Point and closer to a third in prime Camps Bay, from a much lower starting gross. Entry prices in Camps Bay run at multiples of the metro median and rents do not follow proportionally.
It changes Camps Bay more than Sea Point, and it introduces two risks rather than one. Camps Bay's nightly market is intensely seasonal, with December and January carrying most of the year, so revenue arrives in a lump while a bond falls due monthly. Sea Point has the denser short-let stock and therefore more exposure to the City's draft letting by-law. Both are subject to a body corporate's conduct rules, which can prohibit nightly letting by 75% special resolution.
Sea Point, by a wide margin, because it is a suburb people live in rather than visit: it holds a working weekday population, and its tenant pool renews continuously instead of seasonally. A vacancy typically fills in weeks. Camps Bay's long-let pool is much smaller, and a vacancy outside the summer window can run for months.
Camps Bay, on the evidence of what its buyers are. It sells to international recognition and scarcity rather than to a rental calculation, and it recorded 29 prime sales in 2025, the deepest transaction count on the strip, which is what allows an owner to exit inside a normal marketing period. Sea Point's value is more closely tied to what the rental market will pay, which cuts both ways.
Sea Point, if the property is on a long let, because a twelve-month tenancy needs little attention and the pool is deep enough to replace a tenant quickly. Camps Bay run as a nightly let is an operating business needing someone to answer messages and manage turnovers, and our reading is that it produces a good return for an owner who runs it personally and a thin one for an owner who outsources everything.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.