
Cape Town Luxury Sales Hit R11.3bn Record in 2025
Atlantic Seaboard and City Bowl luxury sales hit R11.3bn in 2025, up 26%. Ross Levin data: 116 deals above R20m and a R157.55m Clifton record sale.
By Cape Town Invest Editorial · Updated August 21, 2026 · 4 min read
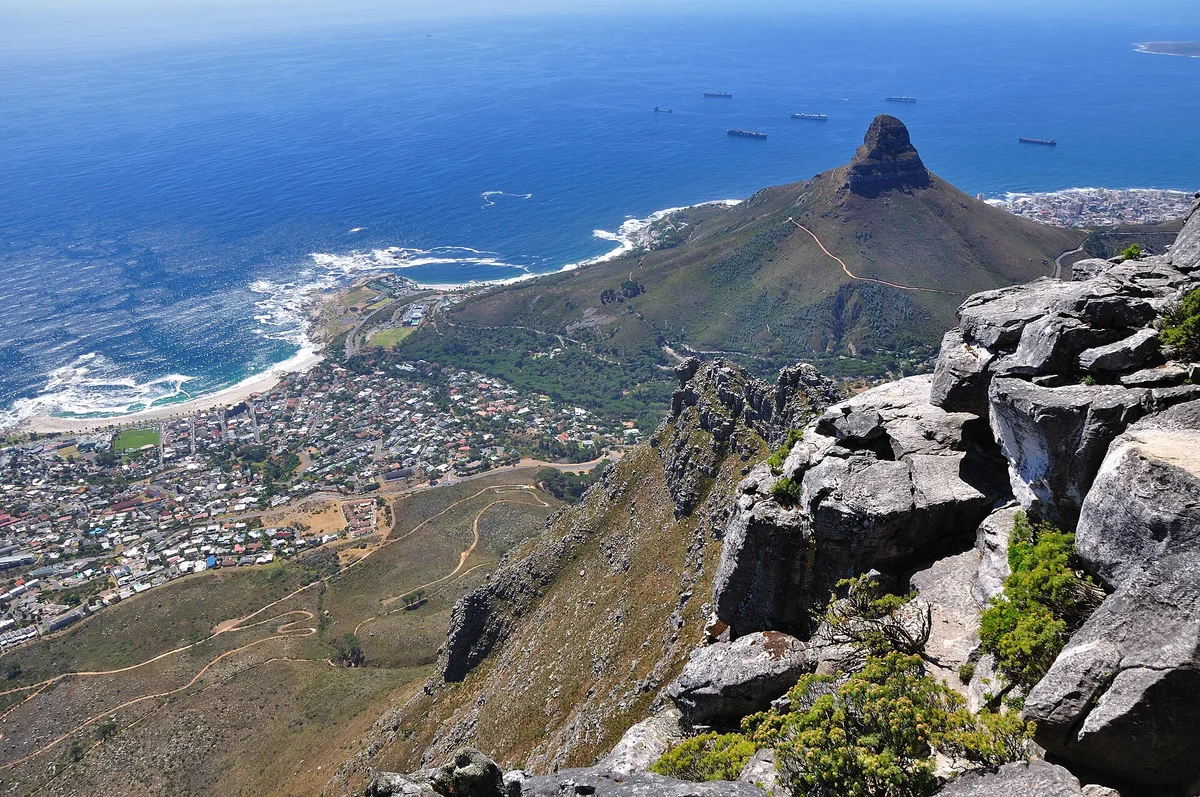
Cape Town’s prestige property market closed 2025 with a headline turnover figure that reframes how investors should read the Atlantic Seaboard and City Bowl. Combined sales in the two corridors reached R11.3bn, up 26% from R8.9bn in 2024, according to data compiled by Ross Levin estate agency and reported across Seeff, Property24, and local industry coverage.
The acceleration was not broad-based discounting. It was concentrated liquidity at the top. Sales above R20m generated R4.2bn in value, a 61% jump year on year, with 116 transactions clearing that threshold. Sixteen deals exceeded R50m, and two crossed R100m, a depth profile that matters for anyone underwriting exit risk in trophy stock.
Why did Clifton set the 2025 price record?
The stand-out transaction was a R157.55m sale in the Clifton Pentagon, a price point that resets buyer expectations for ultra-prime apartments with unobstructed Atlantic views. Clifton’s four-beach geography leaves almost no developable land, which is why trophy pricing here routinely leads the national ladder. Investors comparing suburbs should read our Clifton property investment area guide alongside the wider Atlantic Seaboard property investment guide for yield and foreign-buyer context.
Seeff’s luxury division noted that semigration from Gauteng and KwaZulu-Natal continued to support City Bowl and seaboard demand, while internationally mobile capital kept bidding on view-led stock with limited replacement supply.
Camps Bay leads transaction count above R20m
Suburb-level data shows where liquidity actually sat in 2025. Camps Bay recorded 29 sales above R20m, the highest count in the luxury bracket, ahead of quieter trophy nodes such as Bantry Bay and Fresnaye. That volume matters: a prestige market with headline prices but thin turnover is hard to exit; Camps Bay combined both in 2025.
| Segment | 2025 value | Year-on-year change |
|---|---|---|
| Atlantic Seaboard + City Bowl | R11.3bn | up 26% vs R8.9bn |
| Sales above R20m | R4.2bn | up 61% |
| Transactions above R20m | 116 deals | n/a |
| Transactions above R50m | 16 deals | n/a |
| Transactions above R100m | 2 deals | n/a |
Property24’s 2025 market summaries echoed the same pattern: semigration demand, constrained new supply on the coastal strip, and rising concentration of capital in suburbs where sea proximity cannot be replicated inland.
What the numbers mean for 2026 buyers
For investors, the lesson is structural rather than speculative. The R11.3bn figure is not a single-quarter spike; it reflects sustained competition for a finite pool of Atlantic-facing homes within commuting distance of the CBD. Ross Levin’s breakdown shows growth fastest above R20m, which suggests high-net-worth and foreign buyers are less rate-sensitive than the mainstream market when stock is irreplaceable.
| Buyer type | Typical focus in 2025 | Implication |
|---|---|---|
| Semigration households | City Bowl, Atlantic Seaboard family homes | Supports mid-to-upper pricing |
| Trophy buyers | Clifton, Bantry Bay, Fresnaye | Pushes ceiling values |
| Income-oriented investors | Sea Point, Green Point apartments | Lower price points, higher turnover |
Anyone building a Cape Town allocation should treat 2025 as a liquidity proof point, not a promise of repeat percentage gains. Prime suburbs can compress yields even as values rise, which is why suburb selection remains more important than timing alone. Read the concentration carefully as well. R4.2bn of the R11.3bn total, roughly 37% of all turnover in the two corridors, came from just 116 transactions above R20m, while the remaining R7.1bn spread across everything below that threshold. A market where more than a third of the value sits in barely a hundred deals rewards buyers who understand the specific street and view line, and punishes anyone who buys a suburb average. The metro investment guide frames the city-wide cost stack and growth bands that sit beneath these luxury headlines.
How do foreign buyers finance prime Cape Town purchases?
Non-residents typically face roughly 50% loan-to-value caps from South African banks, so headline sales like the R157.55m Clifton deal still rely heavily on equity or offshore financing. The sales record therefore reflects committed capital, not leveraged speculation at the margin.
Acquisition costs at this level are worth stating plainly, because they decide how much cash a foreign buyer must land in South Africa. Transfer duty on the SARS scale effective 1 April 2025 charges nothing on the first R1,210,000 and then steps through 3%, 6%, 8% and 11% to a top rate of 13%, so on a R20m purchase almost the entire price falls in the top band and the duty alone runs into the millions before conveyancing and Deeds Office fees. Plan the exit at the same time. Where a non-resident sells above R2m, the conveyancer withholds 7.5% of the price for an individual seller, 10% for a company and 15% for a trust as an advance against capital gains tax, with 40% of an individual’s gain included in taxable income.
| Cash line on a prime purchase | Who carries it | Note |
|---|---|---|
| Equity above the 50% bond cap | Non-resident buyer | Offshore capital, recorded at entry |
| Transfer duty, SARS scale from 1 April 2025 | Buyer | 13% top band on the bulk of the price |
| Conveyancing and Deeds Office fees | Buyer | Payable in rand before registration |
| Withholding on resale above R2m | Non-resident seller | 7.5% individual, 10% company, 15% trust |
Outlook from the 2025 baseline
Base effects are the first thing to price. A 26% advance off R8.9bn sets a comparison that gets harder to beat each year, and the 61% jump above R20m came from a bracket where a handful of transactions move the whole total. Two deals above R100m and sixteen above R50m mean the headline number is sensitive to whether a small number of trophy houses happen to change hands inside a given twelve months. A flat 2026 print would be a normal outcome, not evidence of a market turning.
What the data genuinely supports is a view about depth. 116 clearances above R20m, with 29 of those in Camps Bay alone, say the top of this market is not a single-bidder curiosity. There is a repeatable pool of buyers at that level, which lowers exit risk in trophy stock relative to what the price points alone would suggest. That is the useful conclusion for anyone underwriting a hold period rather than a trade.
Financing keeps this bracket insulated from the rate cycle in a way the mainstream market is not. With non-resident lending capped near 50% loan-to-value and prime around 10.5%, most of this turnover was equity-funded. Rate relief should therefore show up first in the bonded mid-market, not in Camps Bay or Clifton, where selection of the individual property continues to matter more than the cycle.
Frequently Asked Questions
Combined Atlantic Seaboard and City Bowl turnover reached R11.3bn in 2025, up 26% from R8.9bn in 2024, according to Ross Levin estate agency data cited by Seeff and industry press. The R20m-plus segment alone accounted for R4.2bn, a 61% increase, with 116 transactions above R20m.
Among the headline deals, a Clifton Pentagon apartment sold for R157.55m, setting a new benchmark for ultra-prime stock on the Atlantic Seaboard. The year also recorded 16 sales above R50m and two transactions above R100m, underscoring depth at the very top of the market.
Camps Bay recorded 29 sales above R20m, the highest suburb count in the luxury bracket. Bantry Bay and Fresnaye each logged strong trophy turnover alongside Clifton, where scarcity and foreign demand keep per-unit pricing at the top of the national ladder.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.