
Foreign Buyers Drive Atlantic Seaboard Sales in 2025
Foreign buyers took 25% of Atlantic Seaboard value in 2025, about R2.8bn. No SA buyer surcharge and 50% LTV rules keep UK, German, and US demand active.
By Cape Town Invest Editorial · Updated September 3, 2026 · 4 min read
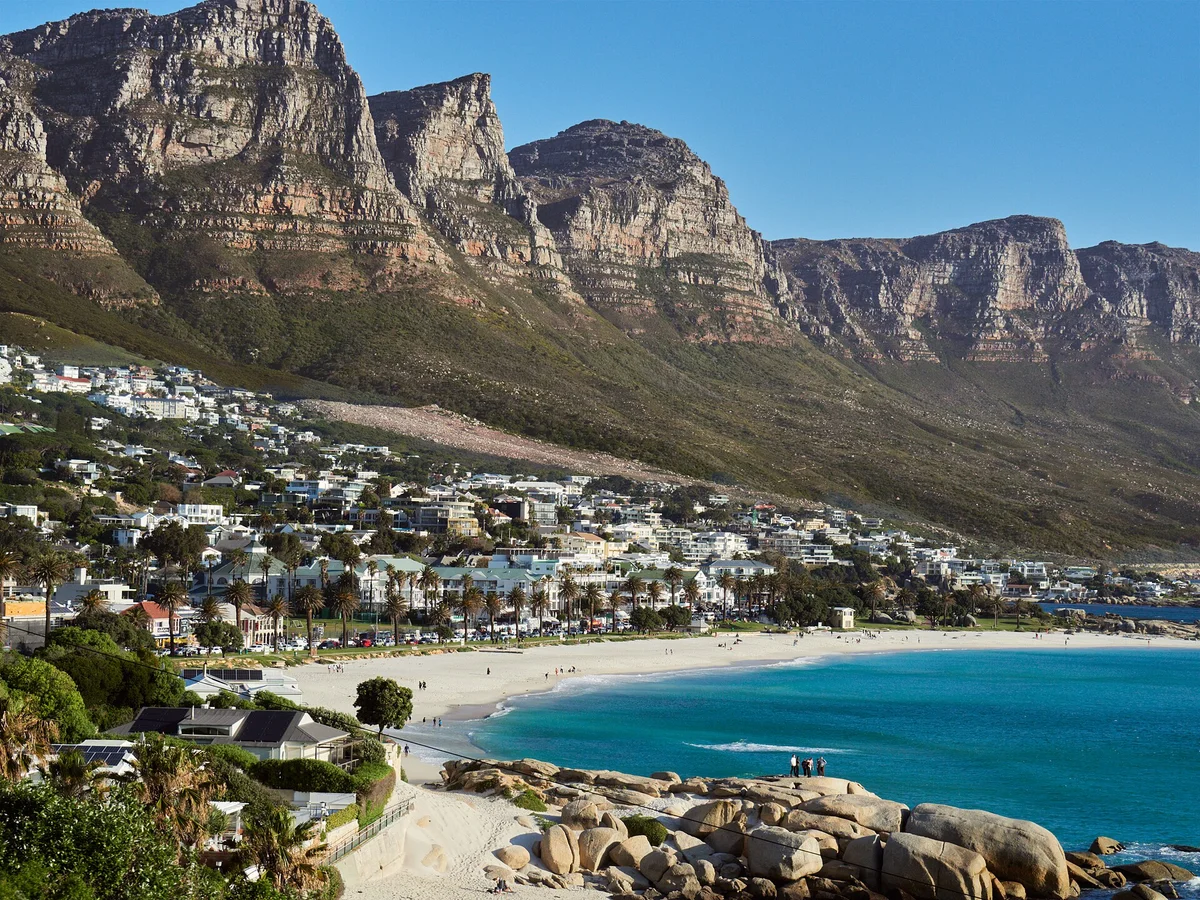
International capital remained a defining feature of Cape Town’s Atlantic Seaboard in 2025, with foreign buyers accounting for roughly 25% of combined Atlantic Seaboard and City Bowl value, about R2.8bn of the R11.3bn annual turnover reported by Ross Levin estate agency data and covered by Seeff and Property24.
The share is not accidental. South Africa imposes no foreign buyer surcharge on residential property, a policy gap that looks increasingly attractive when compared with the United Kingdom’s 2% non-resident stamp duty land tax premium and far higher acquisition taxes in Asian financial hubs.
Why the Atlantic Seaboard attracts offshore capital
Foreign demand concentrates on the Atlantic Seaboard partly because the tax entry is unusually plain. A non-resident buying a R12,000,000 seaboard house pays the same transfer duty as a South African: nothing on the first R1,210,000, then the 3%, 6%, 8%, 11% and 13% bands of the SARS scale in force since 1 April 2025. No surcharge is added for residence status, and no extra rate applies because the property is a second home. Municipal rates follow the same neutral logic, with the first R620,000 of municipal valuation exempt and roughly 0.64 cents in the rand charged annually on the balance. Measured against the United Kingdom’s 2% non-resident stamp duty premium, that neutrality is worth real money at seaboard price levels, and it is one reason foreign buyers took about 25% of the R11.3bn Atlantic Seaboard and City Bowl turnover recorded in 2025.
| Source market | Typical seaboard focus | Policy advantage in SA |
|---|---|---|
| United Kingdom | Clifton, Camps Bay, Sea Point | No 2% overseas SDLT equivalent |
| Germany | Sea Point apartments, Bantry Bay | Euro strength vs rand entry |
| Netherlands | Green Point, Fresnaye | No buyer surcharge |
| United States | Mixed: lifestyle + diversification | Freehold access, English contracts |
Financing rules keep demand equity-rich
Foreign participation at the top end is equity-led. South African banks generally cap non-resident lending at about 50% loan-to-value, meaning a buyer needs substantial offshore cash or cross-border financing arranged before transfer.
A 50% loan-to-value ceiling changes the arithmetic of a seaboard purchase more than any headline price does. On a R15,000,000 apartment the bank finances at most R7,500,000, so the buyer lands R7,500,000 of offshore equity, plus transfer duty that reaches into the top 13% band of the SARS scale, plus conveyancing and bond registration fees. At a prime rate near 10.5%, the local half of that structure is expensive debt by European standards, which is why a large share of R20m-plus deals close in cash. The practical consequence is timing rather than affordability: the inbound transfer, the FICA file, and the bank’s non-resident credit assessment run in parallel, and the slowest of the three sets the transfer date. Buyers who leave the offshore leg until after signing routinely add several weeks to registration.
The buy Cape Town property as a foreigner guide explains the full eligibility stack, while the non-resident mortgage pathway is detailed in our financing content. In practice, many R20m-plus deals close without local leverage, which is one reason luxury turnover rose 61% to R4.2bn even as global interest rates stayed elevated.
Property24 finance columns through 2025 reiterated the same rule: non-residents must register funds with the South African Reserve Bank’s Financial Surveillance Department if they intend to repatriate future sale proceeds cleanly.
Sea Point: where foreign income meets seaboard address
Sea Point combines Atlantic views, dense rental demand, and walkable restaurants, which suits European buyers seeking both lifestyle and lettable income. Short-letting regulation and body-corporate rules still require careful due diligence, but the suburb remains the income node within the prestige strip.
| Suburb | Foreign buyer appeal | Yield profile |
|---|---|---|
| Sea Point | Apartments, rental depth | Higher gross yields |
| Camps Bay | Trophy houses, views | Lower yields, high liquidity |
| Clifton | Ultra-prime scarcity | Lowest yields, highest psqm |
| Green Point | Urban convenience | Mid-band pricing |
Compliance and repatriation matter as much as price
Price negotiation absorbs most of a buyer’s attention and almost none of the actual risk. The expensive mistakes on seaboard purchases by non-residents happen in the paperwork layer, and they surface years after the deal closes.
Start with the inbound leg. Funds should arrive through an authorised dealer bank with the transaction reported to the Financial Surveillance Department, and the deal receipt should be filed permanently, not left with the agent. That document is the evidence that capital was introduced from offshore, and it is what allows the same capital plus the gain to leave again on sale. Reconstructing it a decade later, after a bank has migrated systems and the conveyancer has retired, is the scenario that costs money.
The title deed carries a second requirement: where the purchase is funded with introduced foreign capital, the deed should be endorsed to record non-resident ownership, which supports repatriation at exit.
Price the exit withholding into the model at purchase rather than discovering it at sale. On a disposal by a non-resident above R2 million the conveyancer withholds against the purchase price, 7.5% for an individual, 10% for a company, 15% for a trust. That is an advance against capital gains tax rather than an extra tax, but it holds back cash you may already have committed. The exchange control guide sets out the sequence.
What is the 2026 outlook for international buyers?
Three things carry forward from the 2025 data. The absence of a buyer surcharge is a policy position rather than a fixed feature of the market, and it is the single variable that would reprice foreign demand fastest if it changed. Nothing currently suggests it will, but a buyer underwriting a ten-year hold should note that the United Kingdom introduced its 2% non-resident premium from a comparable starting point.
Currency, not local price growth, remains the real driver of this cohort. A German or Dutch buyer measuring a Sea Point apartment in euro is running two positions at once, the property and the rand. A year of solid rand-denominated gains and a weakening currency nets out to nothing in home currency. Read the 25% foreign share as a statement about relative entry pricing rather than conviction about South African fundamentals.
The 50% loan-to-value ceiling keeps these buyers equity-funded, which means South African rate cuts move local demand more than foreign demand. What moves foreign demand is the cost of capital at home, since a large share of this money is raised or released against offshore assets. When forecasting whether the R2.8bn contribution holds through 2026, watch source-market rates alongside the local ones.
Pros and cons for Cape Town investors
Pros: Atlantic Seaboard stock gives non-residents freehold title, contracts in English, and no acquisition surcharge, so the entry cost is transfer duty on the SARS scale alone. Rand pricing means a euro or dollar buyer effectively sets the entry point, and the 25% foreign share recorded in 2025 points to genuine resale depth at the top end rather than a thin buyer pool.
Cons: Levies, rates, and void weeks compress modelled net yield below portal gross claims; winelands and trophy coastal stock trades liquidity for lifestyle, not income-first returns.
Related reading:
Frequently Asked Questions
Industry data cited in the Atlantic Seaboard investment guide puts foreign buyers at roughly 25% of Atlantic Seaboard and City Bowl value in 2025, about R2.8bn of the combined R11.3bn turnover. Germany, the United Kingdom, and the Netherlands ranked among the leading source markets.
No. South Africa does not levy an additional acquisition tax or stamp-duty surcharge on non-resident buyers. That contrasts with the United Kingdom's 2% non-resident SDLT surcharge and much higher foreign buyer taxes in markets such as Singapore.
Yes, subject to compliance. South African banks typically lend up to about 50% loan-to-value to non-residents, with the balance brought from offshore and recorded through the Financial Surveillance Department. Buyers should budget for transfer duty, bond registration, and FICA documentation.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.