
On Park Century City: Cape Town Resale Investor Review
On Park Century City review: Rabie 121-unit EDGE-target scheme on Ratanga Park, backup power, pavilion design, modelled yields, and resale due diligence.
By Cape Town Invest Editorial · Updated August 21, 2026 · 11 min read
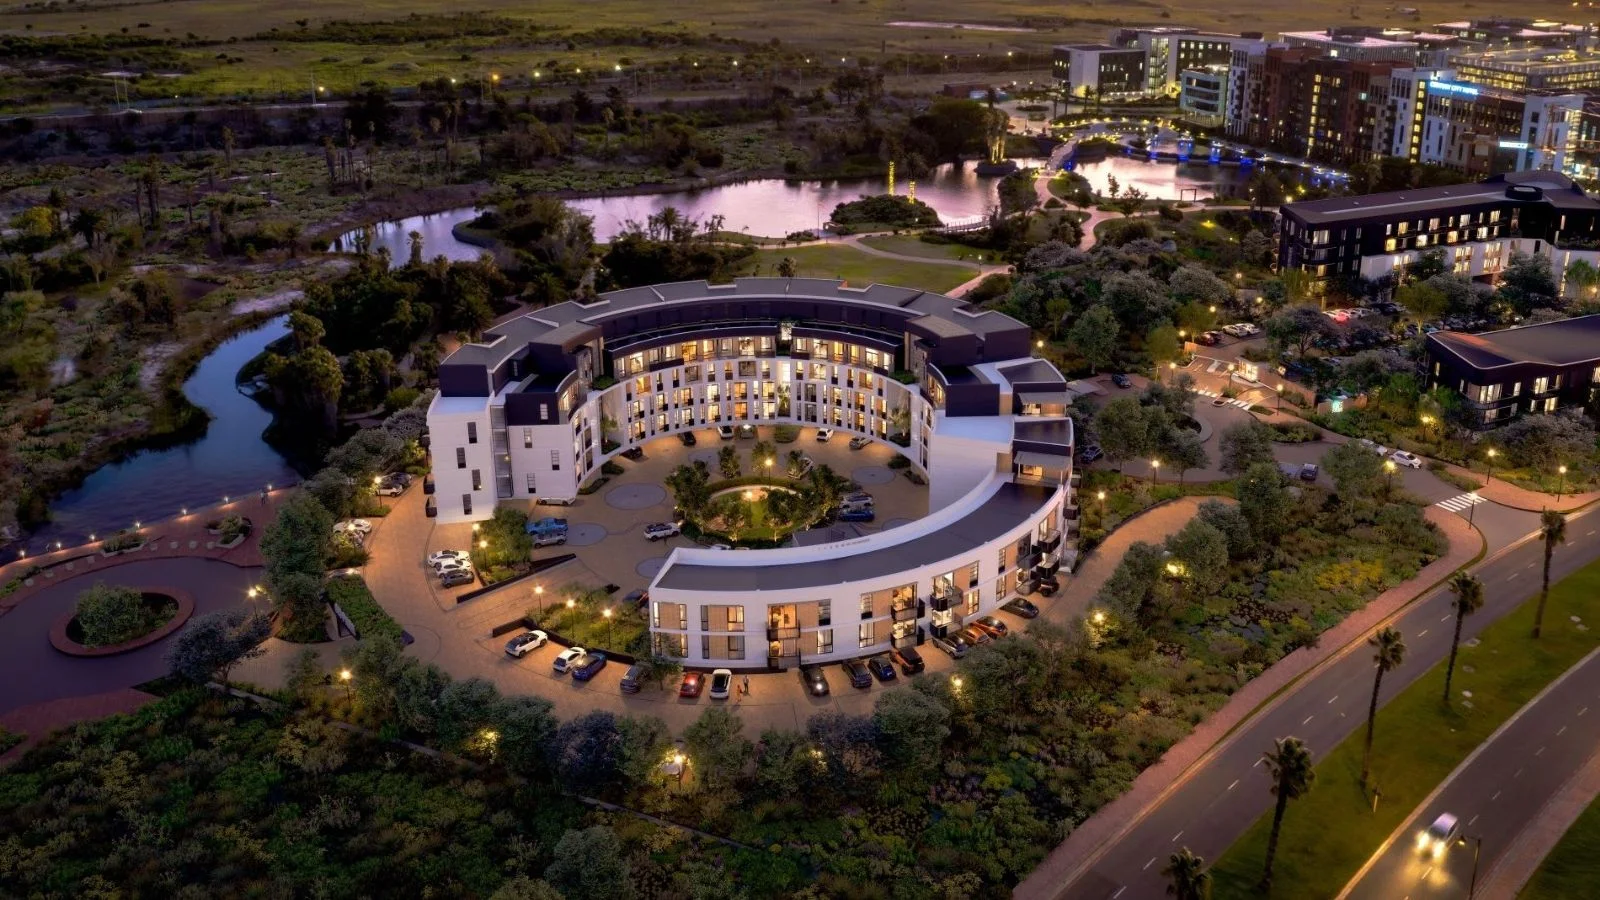
Quick answer: On Park is a completed, occupied 121-apartment scheme by Rabie Property Group on the edge of Ratanga Park in Century City, built as a circular pavilion with backup power to every unit and an EDGE green-certification target. Because it is occupied, you can underwrite it on documents that exist rather than projections, and when you do, the net yield the precinct is usually credited with does not survive the arithmetic. That is the most useful thing this page can tell you.
What occupied stock lets you check
The case for On Park is not the pavilion or the park frontage. It is that the scheme has been standing and let for long enough to have a paper trail, and a paper trail is the only thing that turns a rental yield from a claim into a measurement.
Off-plan asks you to accept four estimates: the completion date, the first levy, the reserve plan and the rent. On Park has replaced all four with records. The body corporate has audited financial statements. The levy has a history, which means it has a trend. The reserve fund is either provisioned or it is not, and the balance says which. The rents achieved in the building are knowable, and so is the vacancy actually experienced rather than the vacancy assumed.
For a buyer underwriting from abroad, that is the difference between a model and a guess. It is also the reason the rest of this page can do something no off-plan review can: put real numbers in and see what comes out.
| Metric | Indicative figure | What it signals |
|---|---|---|
| Developer | Rabie Property Group | Master developer in the precinct since 1997 |
| Total units | 121 apartments | Mid-size scheme, documented body corporate |
| Location | Edge of Ratanga Park, Century City | Park frontage within the precinct |
| Design | Circular pavilion | Distinctive, identifiable building |
| Green credential | EDGE certification target | A target is not a rating, verify status |
| Power resilience | Backup power, all units | Load-shedding defence, with a levy cost |
| Status | Sold out, occupied | Resale only; transfer duty applies |
| Distance to CBD | About 10km, 15 to 25 minutes | Commuter-friendly, inland |
| Retail anchor | Canal Walk, around 400 stores | Footfall, amenity, tenant draw |
The yield this precinct is credited with does not reconcile
Century City stock is routinely described as modelling around 7.7% gross and settling into a mid 5% to low 6% net range after levies, rates, management at 8% to 10% and a vacancy allowance. The gross figure is defensible at the top of the rent range. The net figure is not, and the gap is not small.
Take the inputs the precinct’s own listings supply: one-bedroom flats of about 50 square metres resell between R2,500,000 and R2,900,000, and let at R14,000 to R17,000 a month. Add the costs that are not in dispute, a sectional title levy of R2,000 to R2,500 a month, City of Cape Town rates at 0.0064 in the rand above the R620,000 rates-free portion, letting management at 8% to 10% of collected rent, and one vacant month a year.
Run every combination of those and the picture is this:
| Measure | Across the full assumption grid |
|---|---|
| Gross yield | 5.79% to 8.16% |
| Net yield, full range | 3.19% to 5.39% |
| Net yield, middle half | 3.76% to 4.55% |
| Net yield, median | 4.18% |
The mid 5% to low 6% band is reachable, but only by leaving out management and the vacant month, the two costs the sentence explicitly says have been deducted. Take a R2,750,000 flat at R16,000 a month: R192,000 gross, less roughly R41,600 of levy and rates, gets you to 5.5% and looks like the published claim. Then take off R17,300 of management and R16,000 for the empty month, and you are at 4.2%.
That is about R41,000 a year of difference on one flat. Over a five-year hold it is the deposit on the next one.
None of this makes On Park a bad asset. A 4.2% net return on a low-vacancy, professionally tenanted, remotely manageable flat in a precinct managed by the same developer since 1997 is a reasonable income return. It is simply not the return the marketing arithmetic implies, and a buyer who models at 5.5% and collects 4.2% will spend the hold wondering what went wrong.
The two features that are really questions
EDGE is a target, not a rating. EDGE is an international standard for reduced energy and water consumption, and a certified building genuinely does cost a tenant less to run and carries a credential that supports resale to sustainability-minded buyers. A scheme that is targeting certification has stated an intention. Ask for the certificate. If it exists, you have an asset; if it is still a target three years after occupation, you have a marketing line, and you should stop paying for it in the price.
Backup power has a running cost, and you pay it. Power to every unit through load-shedding is a real driver of tenant choice in South Africa, and it does support the low vacancy the income case rests on. But a backup system is fuel, maintenance and eventual replacement, and all three arrive through the levy. Ask three questions: what does it actually power, for how long, and what does it add per month. A scheme that answers those crisply is well run. A scheme that cannot is telling you the reserve fund may meet the replacement cost as a surprise.
Both features are genuine. Both are also the sort of headline that gets capitalised into an asking price before anyone checks whether it was delivered.
What the resale route costs
On Park is occupied, so every unit trades as a resale between private parties. That means transfer duty on the SARS sliding scale, payable in rand before registration and financeable by nothing:
| Purchase price | Transfer duty | Effective rate |
|---|---|---|
| R2,500,000 | R67,200 | 2.69% |
| R2,750,000 | R87,200 | 3.17% |
| R2,900,000 | R99,200 | 3.42% |
Conveyancing of roughly R28,000 to R32,000 sits on top, before any bond registration cost. On a R2,750,000 purchase, duty and conveyancing together come to about R115,000 to R119,000, or 4.2% to 4.3% of the price, which at a 4.2% net yield is very close to a full year of net rent, spent before you collect any.
This is the honest counterweight to everything good about occupied stock. You are buying certainty, and certainty is priced. Compare it against the off-plan route in the same precinct, where a developer sale carries VAT inside the price and no duty at all, the SkyWater review works that comparison through, with the complication that SkyWater’s release sold out and the developer route is no longer open there either.
What belongs on your checklist
Everything worth asking about On Park already exists in a file somewhere, which is the entire point of buying occupied. A seller who cannot produce these within a few working days has told you something about how the scheme is run.
- The body corporate’s audited financials, the levy history, the reserve fund balance and any special-levy record. Read the levy trend against inflation, not the current figure.
- The EDGE certificate, or written confirmation that it remains a target.
- The backup system’s coverage, runtime, running cost and how it is funded through the levy.
- Achieved rents in the scheme and the real vacancy experience, not the precinct average.
- The sectional title register and scheme rules, including how the section, parking and common-property share are defined.
- The forward supply pipeline for Century City, because Rabie is still releasing phases and yours competes with them for tenants.
- Your own net model, built from the grid above rather than the headline band, with management and vacancy actually deducted.
Where this leaves On Park
It is a well-built, well-located income flat in a precinct that works, and its occupied status is a genuine advantage that most Cape Town stock cannot offer. The return is around 4% net rather than the 5% to 6% the precinct is usually credited with, the two headline features need a certificate and a levy line to confirm them, and the entry cost is roughly a year of net rent.
Priced accordingly, that is a sound purchase. Priced on the published yield band, it is an overpayment of about a percentage point a year, compounding for as long as you hold it.
For the same precinct at a different point in its life cycle, Nine Palms has been occupied since late 2023 and has the longest trading history of the three. The Century City guide covers the precinct case, and the Milnerton area overview the alternatives just outside it.
What to verify next
Start with the accounts, because they are the reason to buy occupied stock at all: audited financials, levy history, reserve balance. Then rebuild the net yield yourself from achieved rents in this building, with management and one vacant month deducted, and compare it against the 4.2% median rather than the published band. Confirm the EDGE status and the backup-power levy line in writing. Read the sectional title register, check the precinct pipeline, and get the total acquisition cost, duty, conveyancing, bond registration, confirmed by a conveyancer before you offer. The cost of buying guide, the rental yield guide and the foreign buyer hub carry the general mechanics.
Sources: SARS transfer duty rates for the 2026/27 year of assessment; City of Cape Town 2026/27 rates policy for the R620,000 rates-free portion and the 0.0064 rate in the rand. Prices, rents, unit count, design and feature claims are as published by the developer and on portal listings. The yield grid is computed from those inputs and is modelled and directional, not a forecast. Current as at 3 September 2026.
Frequently Asked Questions
On Park is a Rabie Property Group apartment scheme of 121 units on the edge of Ratanga Park in Century City, Cape Town. It is known for a circular pavilion-style design, a target of EDGE green-building certification, and backup power across all units, which addresses load-shedding resilience. The scheme is sold out and occupied, so for investors today it trades as a resale and completed-stock case study rather than an off-plan opportunity, inside Rabie's master-planned precinct in the Milnerton area, about 10km north of the Cape Town CBD.
On Park is an income-led, completed-stock buy. As Century City apartment stock it models a gross yield of around 7.7%, settling to about 4.2% net after levies, rates, management at roughly 8% to 10% of rent, and one vacant month a year. The mid 5% to low 6% band usually quoted for Century City is that same model with management and vacancy left out. These figures are modelled and directional, not a forecast or a guaranteed return. Because the scheme is occupied, you can underwrite on actual rents and real body corporate accounts rather than projections, which is a key advantage of resale stock.
Backup power across all units directly addresses South Africa's load-shedding risk, which protects tenant appeal and reduces vacancy in a market where reliable electricity is a genuine differentiator. The EDGE certification target signals lower projected energy and water consumption, which can mean lower running costs for tenants and an ESG credential for resale. For an investor, both features support rental demand and defensibility, but you should still verify the certification status and the actual backup-power coverage and running costs before relying on them.
It can be, because completed and occupied stock lets a foreign buyer underwrite on real numbers. South Africa places very few restrictions on foreign ownership, with no buyer surcharge, unlike the UK 2% surcharge or Singapore's roughly 60% additional duty, and a non-resident can usually finance up to 50% with a local bond and fund the rest offshore. The advantage over off-plan is that you can review the actual body corporate accounts, the levy history, and live tenancy before you commit, removing most estimate risk.
The main risks are sectional title governance, supply, and price. Your real net yield depends on the body corporate's levy trend and reserve fund, so review the latest accounts and any special-levy history. Century City is a master-planned precinct where Rabie keeps releasing new phases, so future stock can pressure rents. And a popular completed scheme can trade at a price that compresses yield, so rebuild net yield on conservative rent and confirm all costs in writing with a conveyancer before you offer.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.