
Security Estates Cape Town Foreign Buyers Guide 2026
How foreign buyers purchase in Cape Town security estates: gated communities, HOA levies, due diligence on management, lifestyle vs yield, and where to buy.
By Cape Town Invest Editorial · Updated August 21, 2026 · 15 min read
Quick answer: can a foreign buyer purchase in a security estate
Yes, and on the same footing as any other Cape Town property. South Africa places no nationality restriction on residential ownership, so a foreign buyer can own a home inside a gated security estate, take registered title, and become a member of the estate’s homeowners’ association exactly as a South African resident would. There is no visa requirement to own and no foreign-buyer surcharge.
What changes inside an estate is not the ownership rules but the layer of community governance sitting on top of them. You are buying both a house and a stake in a managed community, with shared security, shared facilities and a rulebook. That layer is where the value, and the risk, of estate buying really sits, and it is what this guide focuses on. For the underlying purchase mechanics that apply to every foreign buyer, the foreigner buying hub is the place to start.
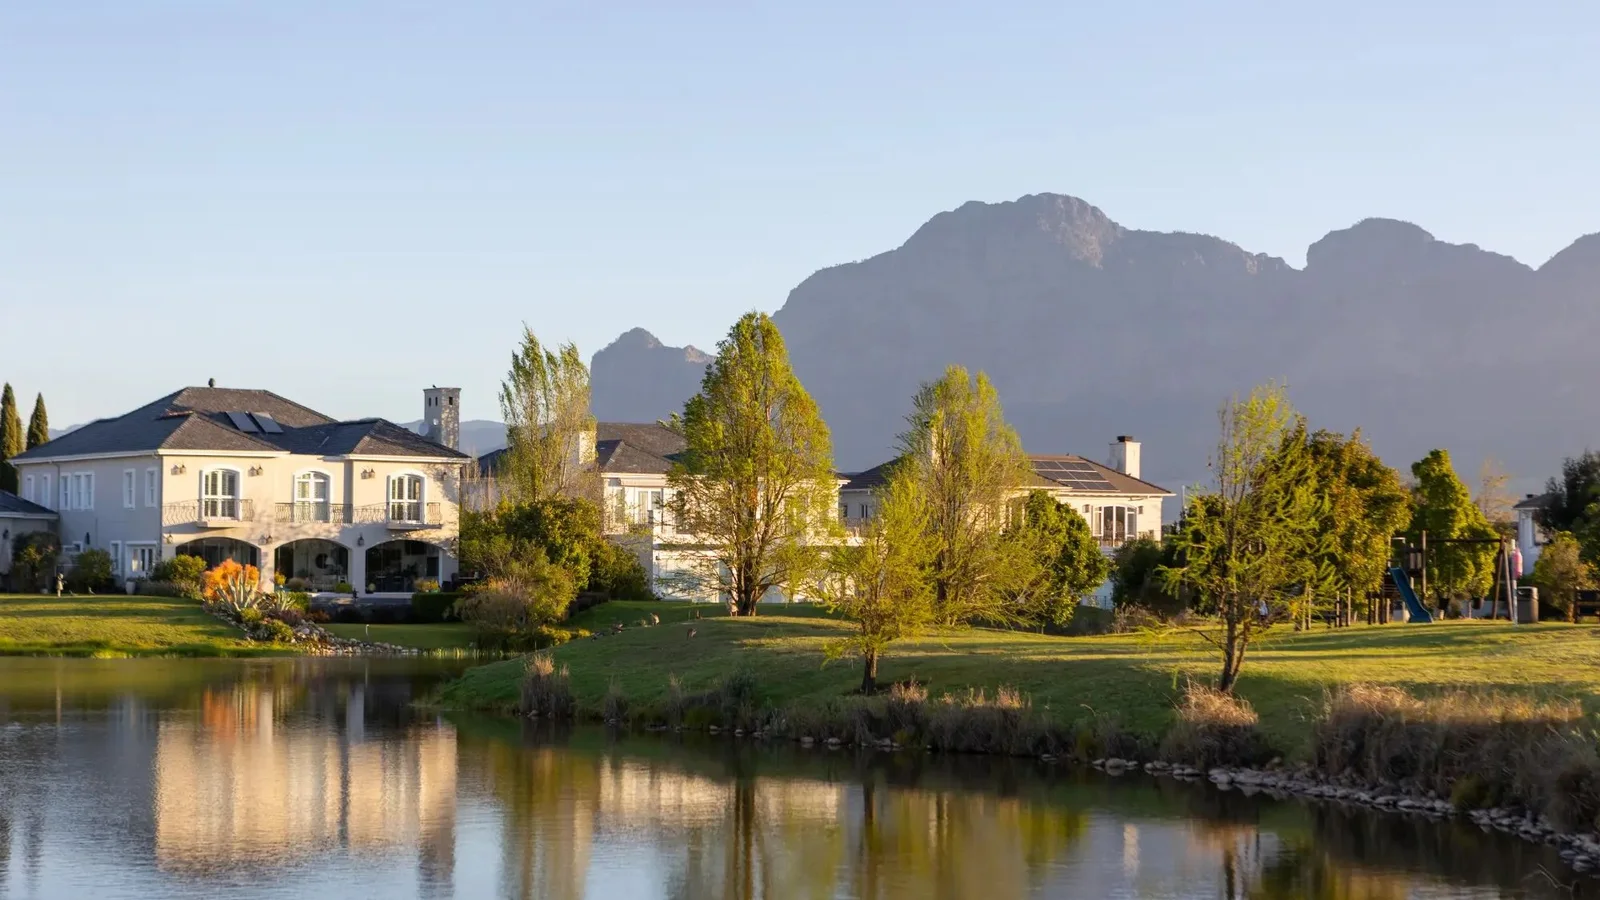
Security estate covers a spectrum from compact townhouse and cluster developments with a wall, single controlled gate, and patrolling guards enclosing a few dozen homes, through leafy family estates of the Southern Suburbs with biometric access and managed common areas, to large lifestyle estates spanning hundreds of hectares with golf courses, clubhouses, equestrian facilities, private security forces, and extensive amenities charging R8,000 to R15,000 monthly levies in luxury golf precincts. What they share is a governance structure through a homeowners association or body corporate that collects levies commonly R2,500 to R8,000 per month, enforces rules governing exterior paint colours to pet ownership and building work, maintains common areas, and contracts the security provider. When you buy you automatically join and agree to be bound by its constitution and conduct rules, so that membership is the defining feature of estate living and the reason due diligence on HOA financials, reserve fund, special levy history, and conduct rules matters more here than on a standalone freehold house.
“Security estate” covers a broad range of gated communities, and it helps to know the spectrum before you shop.
At one end are compact townhouse and cluster developments, where a wall, a single controlled gate and patrolling guards enclose a few dozen homes. At the other are large lifestyle estates spanning hundreds of hectares with golf courses, clubhouses, equestrian facilities, private security forces and biometric access. In between sit the leafy family estates of the Southern Suburbs and the modern mixed-use precincts that combine apartments, houses, offices and retail behind controlled access.
What they share is a governance structure. Almost every estate runs through a homeowners’ association (HOA), a body corporate, or both, which collects levies, enforces rules, maintains common areas and contracts the security provider. When you buy, you automatically join, and you agree to be bound by its constitution and conduct rules. That membership is the defining feature of estate living, and the reason due diligence matters more here than on a standalone freehold house.
The same ownership rules, the extra governance layer
Ownership rules for a foreign buyer are identical inside an estate; the addition is the homeowners’ association. Before transfer the estate issues a levy clearance certificate confirming the seller is paid up, much as the City of Cape Town issues rates clearance, and you sign on to conduct rules plus a levy commonly running R2,500 to R8,000 a month.
Estate rules can govern exterior paint colours, pet ownership, building work, parking and noise. For most foreign buyers that is a benefit rather than a burden, because it is what keeps presentation consistent and protects resale values. It does mean you are buying a set of obligations alongside a house, so the rulebook is part of the deal.
- Levy clearance certificate from the HOA, alongside municipal rates clearance
- Conduct rules and constitution, binding from registration day
- Monthly levy of R2,500 to R8,000, separate from rates and utilities
How do HOA levies affect the true cost of security estate ownership?
The homeowners association levy funds 24-hour security and access control, maintenance of roads, gardens, and common buildings, insurance of common property, and management itself, commonly running R2,500 to R8,000 per month in Cape Town estates with large luxury golf or lifestyle estates charging well beyond that depending on facilities, estate size, and security quality. Crucially the levy sits alongside other costs you still pay including municipal rates on the property billed by the City of Cape Town, utilities for water and electricity often metered per home, and special levies which are one-off charges the HOA can raise for major projects or shortfalls and act as the wildcard in estate budgeting. When you model yield the levy is the line that most often turns an attractive 6 percent gross figure into a modest 4 percent net once the levy, rates, and maintenance are deducted, which is the honest trade-off of estate living. Foreign buyers should price the levy carefully because it is on top of, not instead of, the usual outgoings and directly reduces net rental yield by 1.0 to 1.5 percentage points on a typical R4 million home depending on levy quantum.
The levy is the single recurring cost that distinguishes estate ownership, and foreign buyers should price it carefully because it is on top of, not instead of, the usual outgoings.
A homeowners’ association levy funds the things that make an estate an estate: 24-hour security and access control, maintenance of roads, gardens and common buildings, insurance of common property, and the management itself. In Cape Town estates the monthly levy commonly runs from around R2,500 at the modest end to R8,000 or more, and large luxury golf or lifestyle estates with extensive facilities can charge well beyond that. The figure scales with the facilities, the size of the estate, and the quality of security.
Crucially, the levy sits alongside other costs you still pay:
- Municipal rates on the property, billed by the City of Cape Town.
- Utilities, water and electricity, often metered per home.
- Special levies, one-off charges the HOA can raise for major projects or shortfalls, which are the wildcard in estate budgeting.
When you model yield, the levy is the line that most often turns an attractive gross figure into a modest net one. A home that grosses 6% before costs can net closer to 4% once the levy, rates and maintenance are deducted. That is the honest trade-off of estate living, covered next.
| Cost line | Who charges it | Typical Cape Town range |
|---|---|---|
| HOA levy | Homeowners’ association | R2,500 to R8,000+ a month |
| Municipal rates | City of Cape Town | Scales with property value |
| Utilities | Municipality or estate | Metered per home |
| Special levy | Homeowners’ association | One-off, project-dependent |
Lifestyle versus yield: what estates are really for
Security estates are a lifestyle and capital-preservation play rather than a yield play, and the numbers say so plainly. Estate homes let to families on long leases, so vacancy stays low and demand holds, but gross yields sit near 4% to 6% against the 7% to 10% a small Atlantic Seaboard apartment can model on short lets.
- Estate home, long lets, low vacancy: roughly 4% to 6% gross
- Coastal apartment, short lets, seasonal vacancy: roughly 7% to 10% gross
- Levy drag unique to estates: R2,500 to R8,000 a month before rates
The tenant pool is families and long-term residents who value safety, schools and space, so vacancy tends to be low and demand resilient, but the homes are not geared for holiday letting. What you gain in exchange is stability: steadier occupancy, slower but durable capital growth, and a buyer pool on resale that prizes the security and finish an estate guarantees.
For a foreign buyer the decision usually comes down to intent. If the goal is a family home, a semigration base or a safe place to park capital with predictable costs, an estate fits well. If the goal is to maximise rental income from tourism, a sea-facing apartment is the better tool, and the Southern Suburbs guide and the broader area guides help weigh the two. Many buyers end up doing both: an estate home to live in, and a separate coastal unit to rent.
Due diligence on the estate, not just the house
Estate due diligence runs on documents the seller’s agent rarely volunteers, and the HOA file matters more than the house itself. A weak association shows up as a thin reserve and repeated special levies, which can add tens of thousands of rand to a first year of ownership on a home whose levy already runs R2,500 to R8,000 a month. Work through six items before you sign:
- HOA financial statements. Ask for the last two to three years. A healthy association runs a surplus, maintains a funded reserve, and is not leaning on debt.
- The reserve fund. This is the savings pot for major future works such as roads, roofs and security upgrades. A thin reserve is a red flag, because the shortfall lands on owners as special levies.
- Levy history and increases. Steady, inflation-tracking increases are normal. Sharp jumps or a string of special levies suggest underfunding or poor planning.
- The conduct rules and constitution. Read what you can and cannot do, especially around letting, renovations and pets, so there are no surprises after transfer.
- Special levies, raised or planned. Ask directly whether any special levy is in discussion. A pending levy for a major project can add tens of thousands of rand to your first year.
- Management and security track record. Who runs the estate, is it self-managed or professionally managed, and what is the security provider’s record?
A well-run estate with a healthy reserve and disciplined management protects your capital and is the whole point of paying the levy. A poorly run one, with deferred maintenance and reactive special levies, can quietly erode value no matter how nice the individual house is. The Cape Town due diligence guide sets out the wider checklist that applies to any purchase, and the estate-specific items above sit on top of it.
Where are the strongest Cape Town security estates for foreign buyers?
Three areas anchor the Cape Town estate market, each with a distinct character, price point and tenant profile. Constantia and the Southern Suburbs sell schools and old-money privacy, the Stellenbosch Winelands sell scale and golf, and Century City sells walkable convenience at the most accessible entry price of the three. Levies of R2,500 to R8,000 a month appear across all three, so compare what each one actually buys.
Constantia and the Southern Suburbs. Cape Town’s leafy old-money belt, Constantia and neighbouring suburbs such as Bishopscourt and Tokai, hosts established family estates set among vineyards and tree-lined avenues, close to the city’s leading schools and universities. These suit relocating families and buyers wanting space, privacy and capital stability over rental income. Western Cape house prices rose roughly 179.6% over the decade to 2025 versus about 79.7% in Gauteng, and the Southern Suburbs have ridden that growth. The Constantia area guide and the wider Southern Suburbs property guide cover the suburb-by-suburb picture.
The Cape Winelands around Stellenbosch. A short drive inland, the Winelands offer the largest lifestyle and golf estates in the region, with vineyard settings, world-class restaurants and a strong international-buyer following. Prices can match or exceed the city for trophy homes, and the appeal is space, scenery and a slower pace within secure boundaries. The Stellenbosch property investment guide breaks down the estate and town markets.
Century City. On the city’s northern edge, Century City is a modern, master-planned mixed-use precinct combining apartments, houses, offices and the Canal Walk retail centre behind managed access. It suits buyers who want contemporary estate living with everything, work, shopping, schools and security, in one walkable area, often at more accessible price points than Constantia. The Century City guide details the precinct and its rental dynamics.
| Estate area | Character | Best for |
|---|---|---|
| Constantia / Southern Suburbs | Leafy, family, near top schools | Relocating families, capital stability |
| Stellenbosch / Winelands | Large golf and vineyard estates | Lifestyle buyers, trophy homes |
| Century City | Modern mixed-use, walkable | Convenience, accessible entry price |
Letting a home inside a security estate
Letting rules inside a Cape Town security estate are set by the homeowners’ association, not by the open market. Most estates welcome long-term tenants and underwrite to 4% to 6% gross, while many restrict or ban Airbnb-style short lets outright, because a churn of short-stay guests undermines the security residents pay R2,500 to R8,000 a month to fund.
- Long lets: usually permitted, family tenants, 4% to 6% gross
- Short lets: restricted or banned in many estates, confirm in writing
- Rule source: the estate constitution and conduct rules, not the agent’s brochure
For a foreign buyer this is a make-or-break check. Confirm the letting rules in writing before you commit, especially if your model relies on short-let income. If the estate allows only long lets, plan for the steadier 4% to 6% gross yield profile rather than the higher numbers a coastal short-let apartment can target.
What are the pros and cons of estate buying for foreigners?
Estate buying hands foreign buyers the same ownership rights as a local, with high security and low vacancy attached. The cost is yield: levies of R2,500 to R8,000 a month sit on top of rates and utilities, gross yields run 4% to 6% against 7% to 10% on coastal short-let stock, and conduct rules trim what you may renovate or let.
Advantages
- Same ownership rules as any property: no nationality restriction, no visa, no surcharge.
- High security and controlled access, a genuine draw given crime concerns.
- Low vacancy and resilient long-term family rental demand.
- Maintained common areas and consistent presentation that protect resale value.
- Steady, durable capital growth in established estates.
- A strong resale buyer pool that values the security and finish.
Disadvantages
- HOA levies of R2,500 to R8,000+ a month add to rates and utilities.
- Special levies can land unexpectedly if the reserve fund is thin.
- Lower yield than coastal short-let stock, typically 4% to 6% gross.
- Conduct rules limit renovations, pets and often short-term letting.
- Value depends heavily on management quality, demanding real estate-level due diligence.
- Remote foreign buyers must verify HOA finances they cannot easily inspect in person.
How should foreign buyers start a security estate purchase?
Foreign buyers should start a security estate purchase with ownership and exchange-control basics, narrow by area second, and read the estate’s books last but before signing. Two document requests are non-negotiable: two to three years of HOA financials and the conduct rules in writing. A levy of R2,500 to R8,000 a month decides affordability more than the asking price does.
- Lock down ownership, FICA and exchange control with the foreigner buying hub.
- Narrow by area: the Southern Suburbs guide for Constantia-style family estates, the Stellenbosch guide for Winelands lifestyle stock, the Century City guide for modern mixed-use living.
- Request HOA audited financials, reserve fund balance and special levy history before offer.
- Get letting rules in writing if rental income forms part of the case.
What security estate red flags should foreign buyers treat as deal-breakers?
Three security estate red flags are deal-breakers for foreign buyers: HOA financials withheld before offer, an undisclosed special levy for perimeter or security upgrades, and letting restrictions surfacing after signature. Estate value rests on governance, so a thin reserve behind a levy already running R2,500 to R8,000 a month is the clearest signal of the next special levy.
- HOA financials not shared before offer; special levies for perimeter upgrades are common.
- Foreign ownership caps or rental restrictions in estate rules discovered late.
- Marketing conflates “estate living” with guaranteed capital growth without sales data.
Which buyer profiles fit security estates versus coastal apartments?
Family semigrators win on school access and uniform security but should compare levy plus HOA fees against suburban freehold with private security. Foreign investors must verify short-term letting rules in the management association constitution because many estates restrict Airbnb-style use. Retirement holds should prioritise single-level units and medical access over yield, with Constantia and Winelands estates differing sharply on liquidity.
Family semigrator: Estates win on schools access and uniform security; compare levy plus HOA fees against suburban freehold with private security.
Foreign investor: Some estates restrict short-term letting; verify rental rules in the management association constitution.
Retirement hold: Single-level units and medical access matter more than yield; Constantia and Winelands estates differ sharply on liquidity.
Insider tip: underwrite the homeowners’ association before you underwrite the house, because the estate’s balance sheet will outlive your renovation choices. Cape Town Invest sees HOA levies across Cape Town estates run from about R2,500 to R8,000 a month on top of municipal rates and utilities, and that line is what pulls estate gross yields of roughly 4% to 6% down to a lifestyle-grade net. The number that predicts future pain is the reserve fund. An estate with a thin reserve and a history of special levies for roads, gatehouse upgrades or perimeter systems keeps reaching into owners’ pockets, while a well-funded one charges more monthly and surprises you less. Ask for two years of financials, the special-levy history and the conduct rules, then compare estates on total monthly cost rather than on asking price per square metre.
Frequently Asked Questions
Yes. The same rules apply as for any South African property: no nationality restriction, no visa requirement, and no foreign-buyer surcharge. A foreign buyer owns the home on the same title and joins the homeowners' association exactly as a local resident does.
A homeowners' association levy is the monthly fee that funds security, common-area maintenance, landscaping and management. In Cape Town estates it commonly runs from around R2,500 to R8,000 a month depending on the estate's size and facilities, with luxury golf or lifestyle estates charging more. It is separate from municipal rates and utilities.
Mostly lifestyle, with steadier capital growth than spectacular yield. Estate homes attract long-term family tenants rather than holiday lets, so gross rental yields typically sit near 4% to 6%, below an Atlantic Seaboard apartment. The trade-off is security, low vacancy and resilient demand.
Review the homeowners' association financials, the levy history, the reserve fund, the conduct rules and any special levies that have been raised or are planned. A well-run estate with a healthy reserve protects your value; a poorly managed one with deferred maintenance and rising special levies can erode it.
Constantia and the wider Southern Suburbs offer leafy family estates near top schools, the Cape Winelands around Stellenbosch offer larger lifestyle and golf estates, and Century City offers modern mixed-use estate living with on-site amenities. Each suits a different balance of space, convenience and price.
Usually yes for long-term lets, but the estate's conduct rules govern short-term and holiday letting, and many estates restrict or ban Airbnb-style use to protect security and privacy. Always confirm the letting rules in writing before buying if rental income is part of your plan.
Get a Cape Town property shortlist
Share your budget, target area (Atlantic Seaboard, City Bowl, Winelands), and goal. We reply within one business day with matched stock and next steps.